
Q3 Earnings Beat Could Be A Game Changer For Herbalife Stock (HLF)
- Herbalife reported third quarter 2026 results with sales of US$1,350.2 million and net income of US$58.8 million, both above the prior year.
- The nine month figures show higher sales but lower net income and earnings per share, which highlights pressure on profitability despite top line progress.
- We will examine how Herbalife's improving third quarter earnings per share may influence the broader investment narrative around the business.
Scan Herbalife's latest earnings shift alongside other companies facing similar profit pressure by reviewing the hand picked 34 high quality undervalued stocks.
Herbalife Investment Narrative Recap
To own Herbalife, you need to believe the current push on personalized nutrition, subscriptions and digital tools can turn steady sales into healthier earnings. The latest quarter helps that case in the short term, with higher Q3 net income and EPS showing the cost base is not completely boxing the business in.
The bigger swing factor still sits in margins and regional mix. Q3 strength does not erase pressure from weaker China and EMEA volume or the recent drop in net margin over the last year. The key risk remains that higher costs and interest expenses keep absorbing revenue progress before it reaches the bottom line.
The latest Q3 report is the update that matters most right now. Herbalife booked US$1,350.2 million of sales and US$58.8 million of net income for the quarter, both above the prior year, with diluted EPS from continuing operations at US$0.55 compared with US$0.42. That suggests recent product and pricing actions are gaining some traction.
The nine month story looks tougher, with US$3,994.2 million of sales but net income at US$94.4 million compared with US$142.9 million a year ago. For catalysts like digital upgrades and emerging market expansion to really show through, future quarters will need to convert that higher top line into more consistent EPS progress without relying on one off items.
Herbalife's current analyst storyline points to revenues of US$5.6b and earnings of US$465.5 million by 2029, based on a projected 2.6% yearly revenue growth rate and a move in earnings from US$164.2 million today, which implies an increase of about US$301 million in profit over that period.
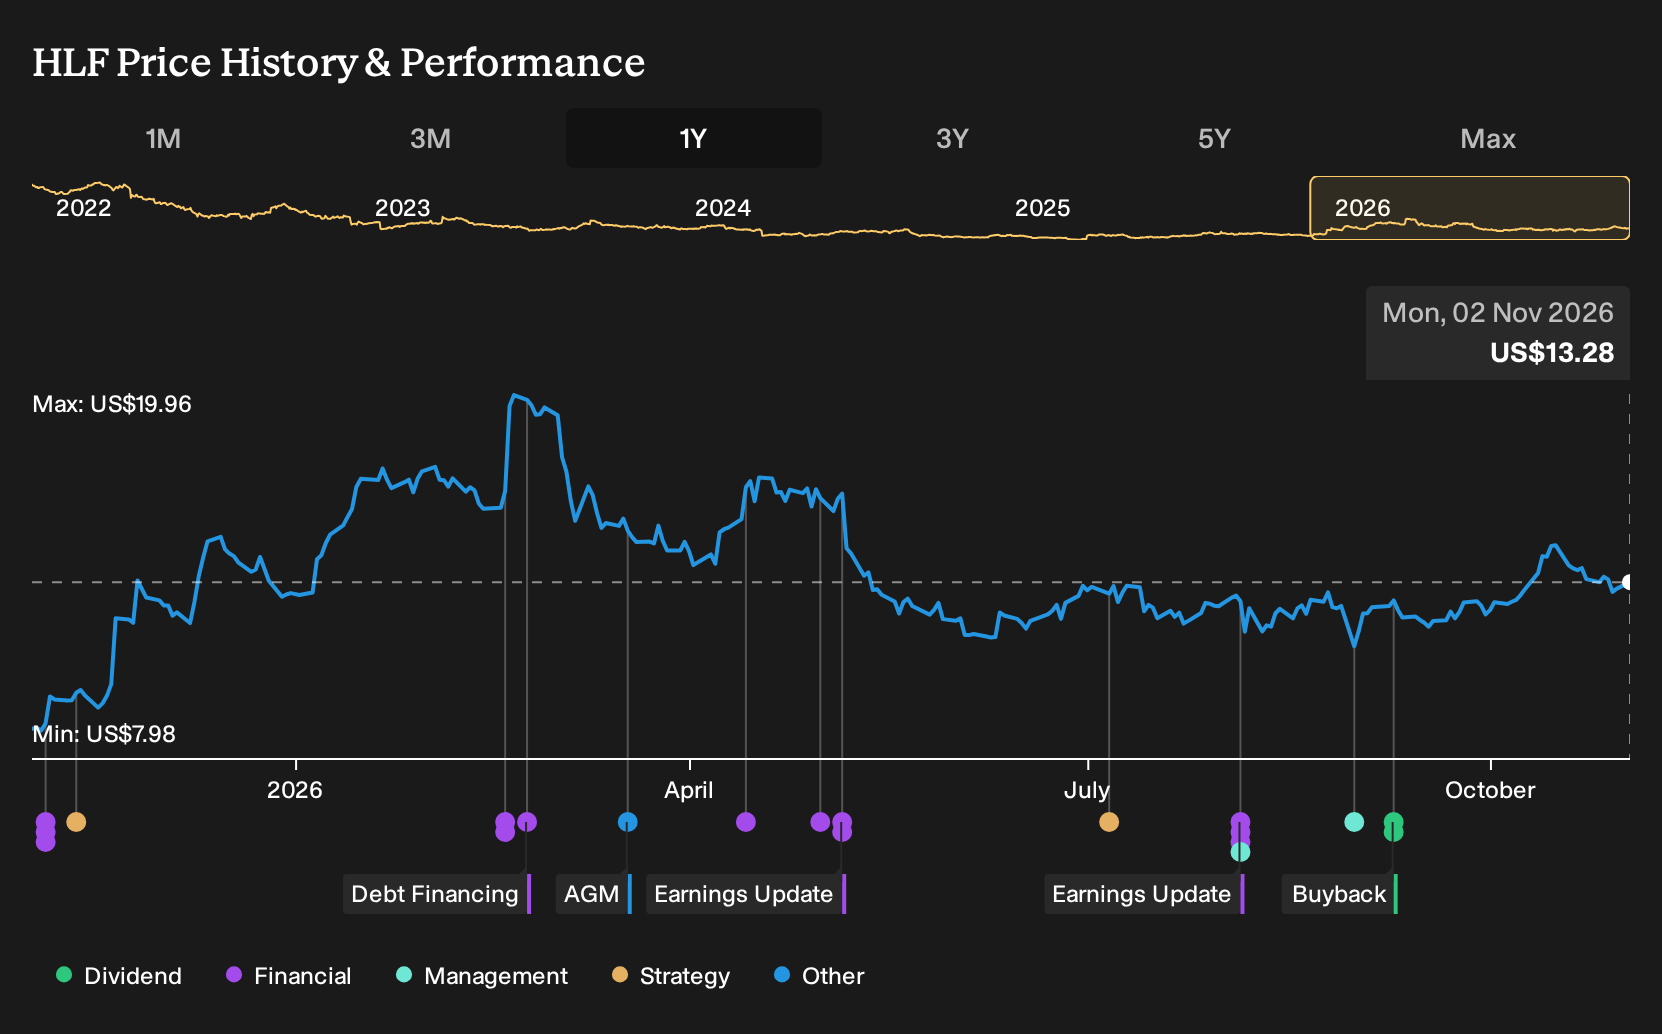
Uncover how Herbalife's fair value indicates a 28% potential upside to its current price before that valuation gap starts to close.
Exploring Other Perspectives
Some of the most optimistic analysts frame India as the real swing factor for Herbalife. Before this Q3 release, that bullish group was working off revenue forecasts of about US$5.7b and earnings near US$469.1 million by 2029. Your view on whether this latest quarter reinforces or softens that India focused growth story may differ a lot. This is exactly why it helps to compare several analyst cases side by side.
Explore 4 other Herbalife fair value estimates, including one that suggests as much as 228% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Herbalife research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Herbalife. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Herbalife's overall financial health at a glance.
Looking for more Herbalife style investment ideas?
If Herbalife's story has you thinking about what else might fit your watchlist, it helps to scan a wider field of opportunities that match different risk and return preferences.
- For investors who want to focus on value combined with quality fundamentals, use the 34 high quality undervalued stocks to see which companies fit that profile right now.
- If capital preservation and steadier profiles appeal more, filter for resilient businesses through the 29 resilient stocks with low risk scores and see which stocks pass those checks.
- When you want to widen the search beyond the usual large caps, the 19 high quality undiscovered gems can help surface under the radar ideas with stronger financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com