
What Hope Bancorp (HOPE)'s Stronger 2026 Outlook Means For Shareholders
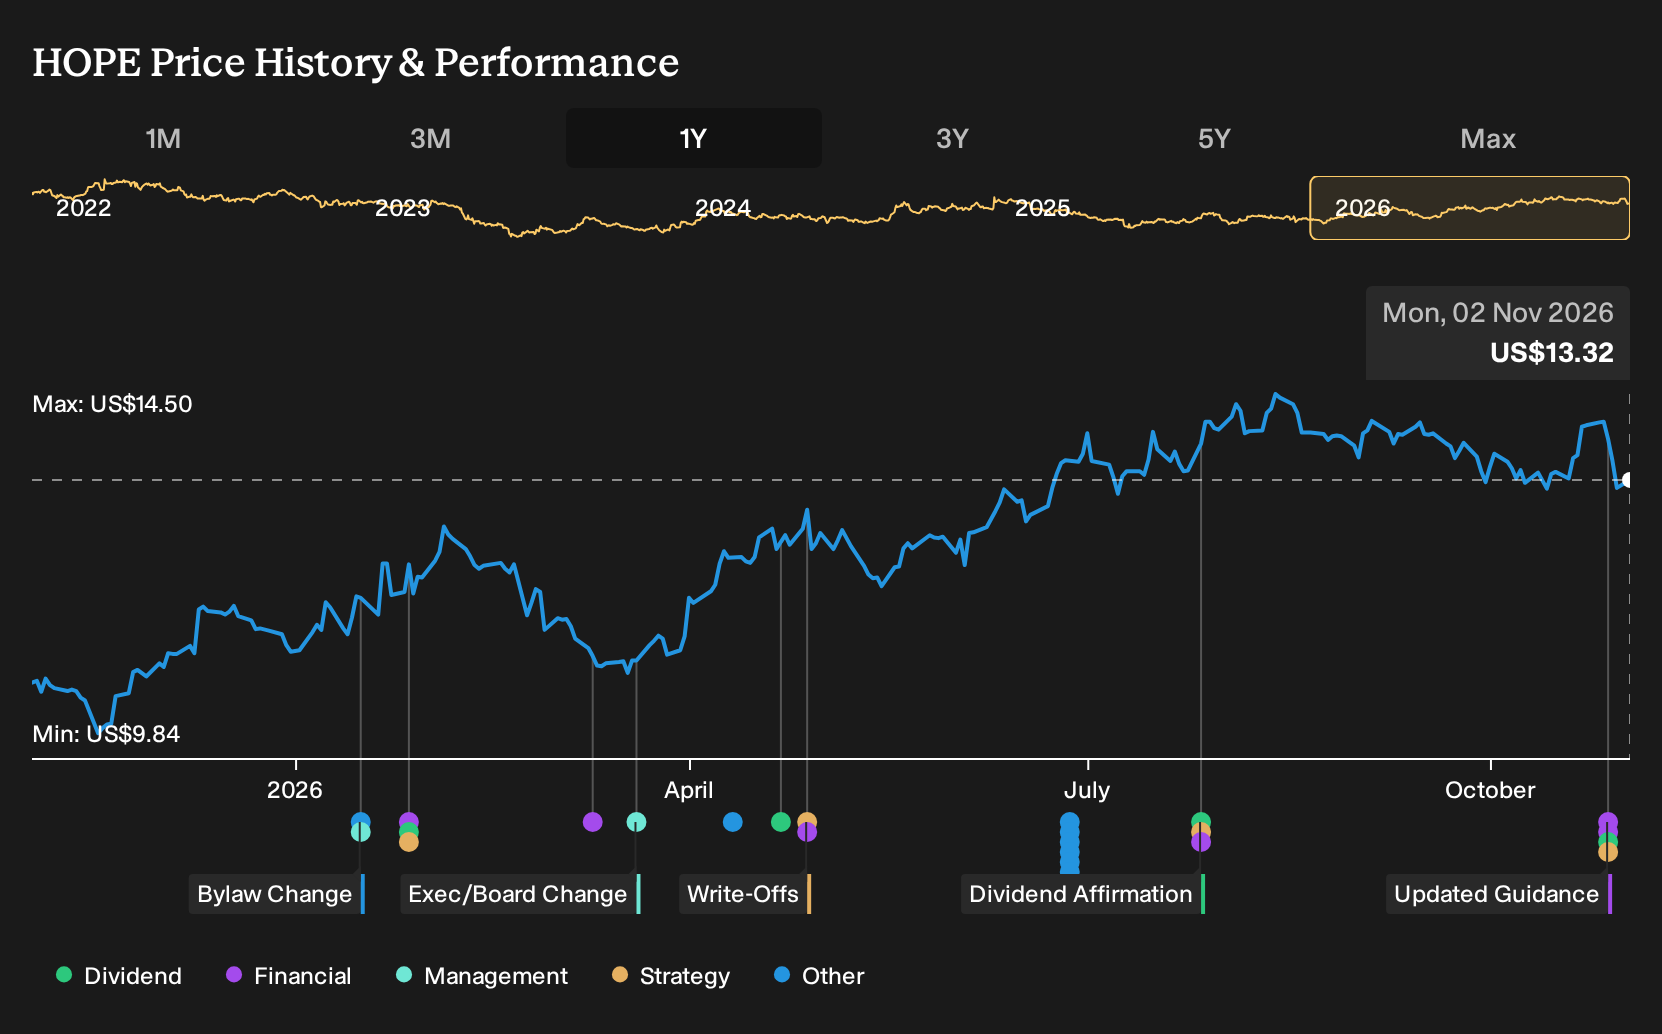
- Hope Bancorp reported higher net interest income and net income for the third quarter and first nine months of 2026, issued full year guidance that points to double digit loan and revenue expansion, and its board declared a quarterly cash dividend of US$0.14 per share payable in November 2026.
- The guidance for approximately 15% year over year loan growth and mid teens revenue expansion, together with rising pre provision net revenue expectations tied to MANUBANK integration, highlights how management is leaning on both organic lending and recent deals to reshape the earnings mix.
- The potential impact of Hope Bancorp's stronger pre provision earnings guidance for 2026 on its overall investment narrative will now be in focus.
Scan beyond Hope Bancorp and compare this guidance-driven story with a curated 34 high quality undervalued stocks that also pairs revenue momentum with stronger balance sheets.
Hope Bancorp Investment Narrative Recap
For an investor to stay with Hope Bancorp, the core belief is that management can turn recent lending and revenue momentum into consistently better profitability. The 2026 outlook, with guided loan, revenue and pre provision net revenue growth, leans into that story and keeps the near term focus on integrating acquired books cleanly.
The biggest short term swing factor remains credit quality in a balance sheet that still leans on commercial real estate and small business borrowers. Rising net charge offs in the third quarter show why this is front of mind, although the latest guidance does not materially alter that risk profile yet.
The most relevant update tied to this story is the full year 2026 guidance, which links the MANUBANK deal to higher pre provision net revenue expectations. For investors, that guidance frames how much of Hope Bancorp’s recent earnings strength is expected to come from underlying trends versus acquisition uplift.
On the positive side, management is pointing to double digit revenue expansion and even faster pre provision profit growth, which speaks directly to operating leverage as a near term catalyst. At the same time, any acceleration in loan growth, including from acquired portfolios, keeps execution on credit selection and integration firmly in focus.
What Consensus Expectations Assume for Hope Bancorp
Analysts are effectively asking you to picture a different Hope Bancorp by the end of the decade. The working model is that acquisitions like MANUBANK and Territorial Savings combine with organic lending to lift revenue, improve efficiency and gradually widen profit margins from where they sit today.
In the stock analysis reports, the core assumptions are fairly explicit. Revenue is projected to grow by 25.2% each year on average over the next three years. Profitability is modeled to shift from a 23.9% margin today to 26.7% in roughly three years, which would mean a larger share of each dollar of revenue dropping through to the bottom line if those estimates play out.
Earnings are a big swing factor in that story. The consensus view has Hope Bancorp’s net income moving from US$127.8 million today to US$279.6 million by around 2029, with earnings per share at US$2.18 on those numbers. That implies earnings a little more than doubling over the period on the analyst math, supported by both higher margins and modest share count reduction of about 0.35% per year.
Valuation assumptions sit alongside those operating targets. To line up with the consensus price target, the bank would be trading on a P/E of 8.6x those 2029 earnings, compared with 13.6x today and an industry level quoted at 11.5x for US banks. The scenario effectively prices in higher profits paired with a lower valuation multiple than both the current Hope Bancorp level and the broader peer group.
Discount rates also shape that framework. The underlying Simply Wall St work applies a 7.24% rate to bring future cash flows back to today, while the summary of the price target discussion references a 7.2% rate in the example where revenues reach US$1.0b and earnings hit US$279.6 million by 2029. Small differences in that input can change the modeled fair value, so it is worth checking whether that hurdle rate lines up with your own view of risk.
Hope Bancorp's narrative projects US$1.0b revenue and US$279.6 million earnings by 2029. This assumes 25.2% yearly revenue growth and implies earnings a little more than doubling from US$127.8 million today.
Discover why Hope Bancorp's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster in a tight US$15.50 to US$18.15 range, so you are not seeing extreme outliers on Hope Bancorp yet. Consider this alongside rising net charge offs, fresh 2026 guidance and acquisition related catalysts, and it becomes worth exploring more Community perspectives before forming your own stance.
Explore another Hope Bancorp fair value estimate, including one that suggests up to 36% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hope Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hope Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Hope Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond Hope Bancorp?
Once you have a handle on Hope Bancorp, it can be useful to benchmark its risk, income and balance sheet profile against other opportunities on the Simply Wall St Screener.
- If you want resilient holdings that aim to limit downside, start by reviewing 29 resilient stocks with low risk scores that score well on our risk framework.
- For investors who care most about getting paid while they wait, scan the income opportunities in our 4 dividend fortresses that focus on higher yielding payouts.
- If balance sheet strength is your anchor, line up Hope Bancorp against a list of solid balance sheet and fundamentals (24 results) to see which businesses pair financial resilience with sound fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com