
Upstart Holdings (UPST) Stock Dropped, So What Is Drawing Attention Now?
Why Upstart Holdings Is Back in Focus Before Earnings
Upstart Holdings (UPST) is drawing attention as traders look ahead to its upcoming quarterly update and weigh a fresh data point from the lending side of its business.
MIT Federal Credit Union recently expanded its relationship with Upstart into indirect auto lending, adding a secured product on top of the personal loan partnership that began in 2024 and broadening how members can borrow.
Despite the fresh MIT Federal Credit Union expansion and the upcoming earnings update, Upstart Holdings’ recent trading has been weak, with the share price down 7.4% over the past day and 29.7% over 90 days. This has contributed to a 55.2% slide in 1 year total shareholder return and a 93.6% decline over 5 years, which signals fading momentum as investors reassess both growth prospects and risk around its AI lending model.
Scan beyond Upstart Holdings and spot other AI driven lenders that may be setting up for sharper moves in the same theme with the curated 40 profitable AI stocks that aren't just burning cash.
After a 1 year slide and a market value near US$2.2b, the question around Upstart Holdings is simple: Is most of the recovery already in the past, or is the valuation still leaving real upside on the table?
Most Popular Narrative: 44% Undervalued
Upstart Holdings closed at $21.31 while the most followed narrative anchors fair value near $38.38. The gap between price and modeled outcome is wide and puts the focus on whether its AI driven underwriting and funding access can support that valuation over time.
Expanding committed capital relationships, including up to US$10.8b of new capacity year to date, renewed institutional partnerships, recent securitizations and new credit union agreements, points to a deeper funding base that can support higher originations with limited balance sheet usage and potentially stronger contribution margins and earnings.
See why 144 investors see Upstart Holdings as 44% undervalued.
Result: Fair Value of $38.38 (UNDERVALUED)
Still, if borrower defaults stay elevated or Upstart Holdings’ AI models misjudge new loan vintages, funding partners could pull back and squeeze fee economics.
Find out about the key risks to this Upstart Holdings narrative.
Another View On Upstart Holdings’ Valuation
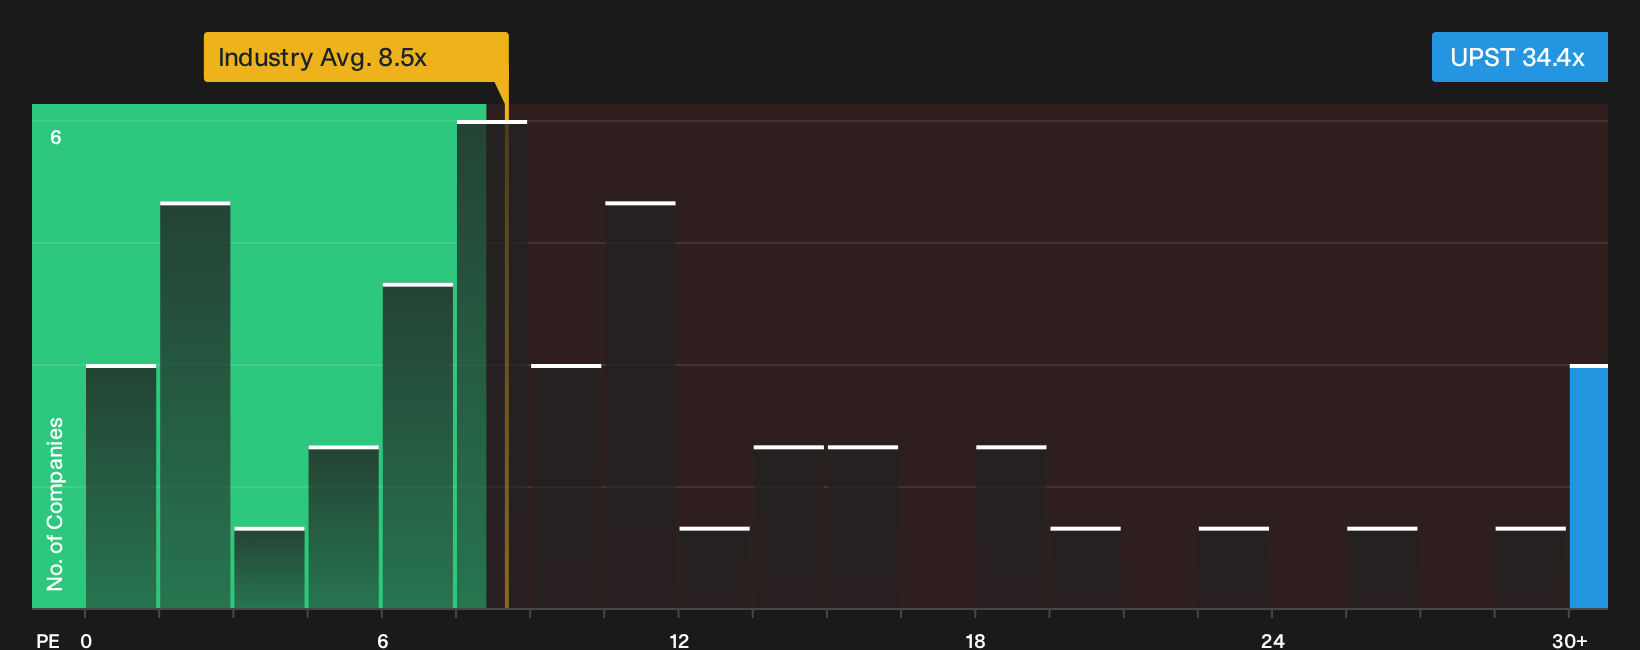
The earlier narrative leans on a fair value of $38.38, yet on simple P/E math Upstart Holdings screens as expensive. The shares trade on roughly 34.4x earnings versus about 8.5x for the US Consumer Finance group, 11.6x for peers and a fair ratio closer to 32.5x.
That premium suggests investors are already paying up for execution on the AI lending story rather than getting it at a clear discount. This raises the question of how much mispricing, if any, is really left on the table for patient holders.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these rarely stay unresolved for long, so review the data, weigh both sides, and decide quickly where you stand on Upstart Holdings. To pressure test that view against the key issues investors are watching, check out the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Upstart Holdings?
If you want a fuller opportunity set alongside Upstart Holdings, use focused stock lists to pressure test your thesis and avoid leaving compelling ideas on the table.
- Hunt for mispriced quality and see where strong fundamentals line up with attractive entry points through the 34 high quality undervalued stocks.
- Anchor your portfolio with income ideas and use the curated 4 dividend fortresses to spot higher yield payouts with defensive profiles.
- Dial down potential shocks by leaning on the 29 resilient stocks with low risk scores to surface companies that pair resilience with more measured risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com