
CNH Industrial (CNH) Could Be 17% Below Fair Value On Earnings Beat Hopes
Why CNH Industrial’s Upcoming Earnings Matter
CNH Industrial (CNH) heads into its November 9 earnings release with expectations of an earnings beat, as analysts grow more optimistic and traders position around the potential reaction in the shares.
Recent trading has been choppy for CNH Industrial. The stock has a 7 day share price return of 4.98% but is down 12.32% over 30 days. At the same time, a 26.31% year to date share price return and 14.54% 1 year total shareholder return point to momentum that is moderating rather than breaking.
Scan how CNH Industrial compares with other machinery and capital goods players that analysts rate highly on quality and valuation by checking the hand picked 34 high quality undervalued stocks.
For CNH Industrial, that mix of a strong year to date gain and a weaker recent stretch raises a simple question: Are investors reacting to the business itself or just resetting sentiment ahead of earnings, and what does current pricing suggest?
Most Popular Narrative: 17% Undervalued
Against a last close of $11.81, the most followed narrative pegs CNH Industrial’s fair value at $14.25, which frames today’s pullback as a potential discount rather than just pre earnings nerves.
The integration of advanced connectivity and precision technologies such as the FieldOps platform and AI enabled tools continues to position CNH Industrial to draw more recurring, higher margin revenue from software, data and tech based services, which can support net margins and earnings.
Persistent focus on manufacturing quality, process improvements and multi wave strategic sourcing programs, which are reported to have already produced US$230 million of Agriculture cost savings in 2025 and are targeted to add 100 to 150 basis points of margin improvement from sourcing by 2030, can support higher net margins and earnings power as these actions flow through.
See why 21 investors see CNH Industrial as 17% undervalued.
Result: Fair Value of $14.25 (UNDERVALUED)
Still, tariff headwinds on Agriculture and Construction margins and elevated South American credit risk could quickly weaken the case that CNH Industrial is undervalued.
Find out about the key risks to this CNH Industrial narrative.
Another View: CNH Industrial Looks Expensive On Earnings
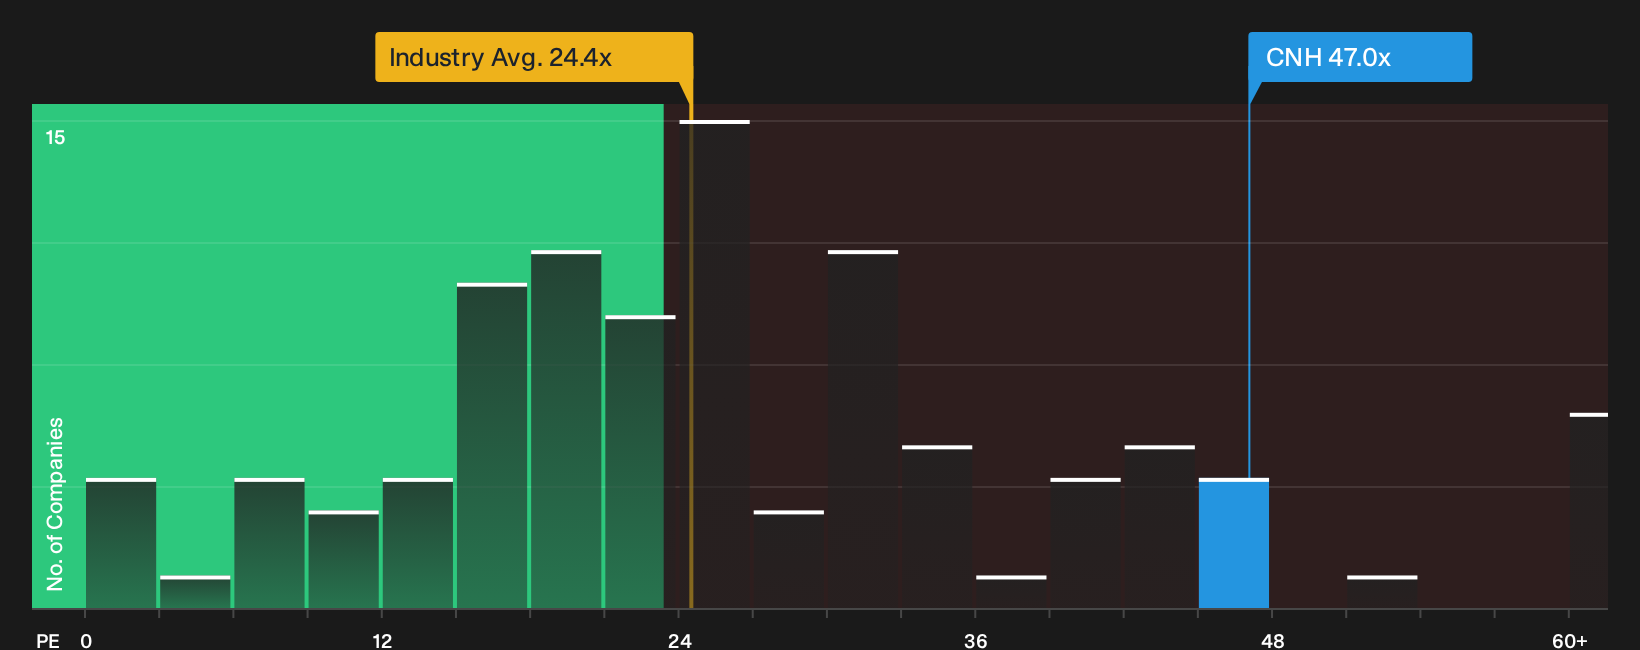
On the flip side of that fair value of $14.25, CNH Industrial trades on a P/E of 47x. The wider US Machinery group sits at 24.4x and similar peers average 27.9x, while the fair ratio is 40.8x. That gap points to valuation risk if high growth expectations slip.
Before leaning too heavily on the earnings multiple, it is worth checking how the numbers stack up against cash flows and other checks in our valuation breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on CNH Industrial’s valuation and expectations leave plenty of room for interpretation. Act while the information is fresh and pressure test the story for yourself using the 1 key reward and 2 important warning signs.
Looking For More Investment Ideas Beyond CNH Industrial?
Do not stop with CNH Industrial. Broaden your watchlist now, because some of the strongest opportunities often sit just outside the headlines you are already tracking.
- Target stability and income by checking a curated group of higher yield opportunities through the 4 dividend fortresses.
- Focus on financial resilience by scanning the list of solid balance sheet and fundamentals (24 results) for candidates with sturdier fundamentals and cleaner balance sheets.
- Identify potential opportunities early by reviewing the 19 high quality undiscovered gems that combine quality traits with lower visibility among investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com