
Cactus (WHD) Earnings Growth And New Plant Put Valuation Back In Focus
Cactus (WHD) is back in focus after its Q3 2026 earnings release, which paired higher sales and net income with an approved quarterly dividend and fresh investment in a new Middle East spoolable pipe plant.
Despite the solid Q3 report and the approved dividend, Cactus shares have eased recently, with the 1-day share price return down 5.3% and the 90-day share price return lower by 7.4%. However, the year-to-date share price return of 32.3% and 1-year total shareholder return of 41.7% indicate that longer term momentum has still been positive overall.
Scan how Cactus compares with other energy equipment players by reviewing hand-picked 43 power grid technology and infrastructure stocks that could also be reacting to capacity expansions and earnings momentum.
Cactus is reporting stronger earnings and funding new capacity, yet the share price still slipped on the latest report. Does that pullback offer a reasonable entry point, or does it argue for patience until the valuation looks cleaner?
Most Popular Narrative: 13% Undervalued
Cactus last closed at $62.22, while the most followed narrative estimates fair value at $71.56. The story hinges on whether that gap reflects opportunity or overly optimistic forecasts.
The earlier FlexSteel acquisition has evolved into the current Spoolable Technologies segment, where Cactus is adding about 20% Baytown capacity and evaluating an Eastern Hemisphere plant while booking over US$80 million of new international orders. Together, these developments point to future spoolable pipe revenue growth and potentially higher segment level earnings.
See why 9 investors see Cactus as 13% undervalued.
Result: Fair Value of $71.56 (UNDERVALUED)
Still, execution setbacks on Cactus International synergies or renewed tariff pressure on steel imports could quickly challenge the current undervalued narrative.
Find out about the key risks to this Cactus narrative.
Another View: Cactus Through The P/E Lens
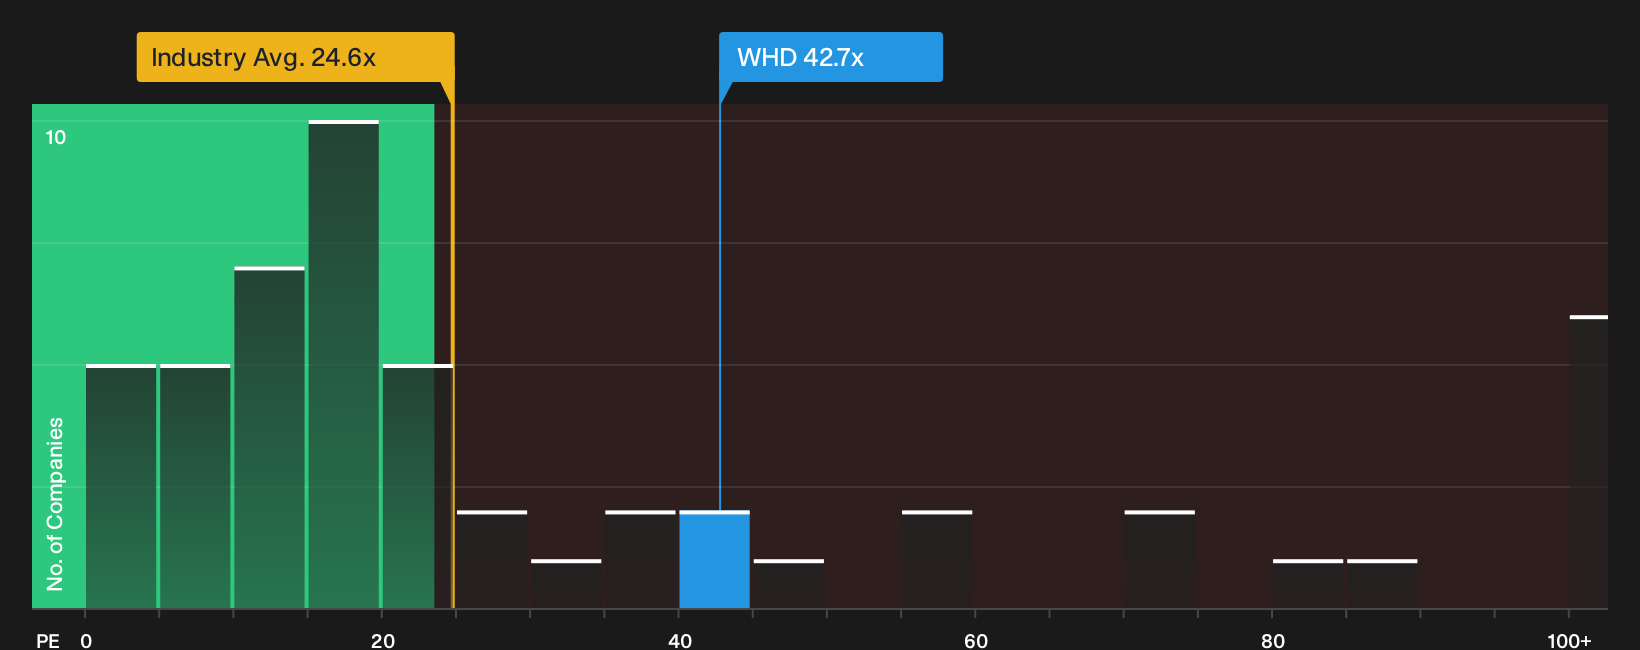
Cactus might look inexpensive based on a narrative fair value of $71.56, yet the current P/E of 42.7x tells a different story. That multiple is well above the US Energy Services industry at 24.6x and the fair ratio of 23.6x, which suggests investors are paying a premium that could limit upside if expectations cool.
To see how that pricing compares with the underlying numbers and alternative scenarios, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Cactus so far, right, with valuation, earnings and sentiment all pulling in different directions while investors debate where risk and reward really sit. Act quickly, review the full data set, weigh both sides carefully, then anchor your own stance using the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Cactus?
Do not park everything in a single story. Use the data to widen your opportunity set and pressure test Cactus against other potential candidates.
- Target growth at a discount by scanning a curated 34 high quality undervalued stocks that filters for quality businesses priced below their estimated worth.
- Build a steadier income stream by reviewing a focused 4 dividend fortresses that highlights companies offering higher yields with supporting fundamentals.
- Dial down portfolio risk by screening a 29 resilient stocks with low risk scores that concentrates on resilient balance sheets and lower historical volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com