
Is Raised Sales Guidance Altering The Investment Case For Carrier Global (CARR)?
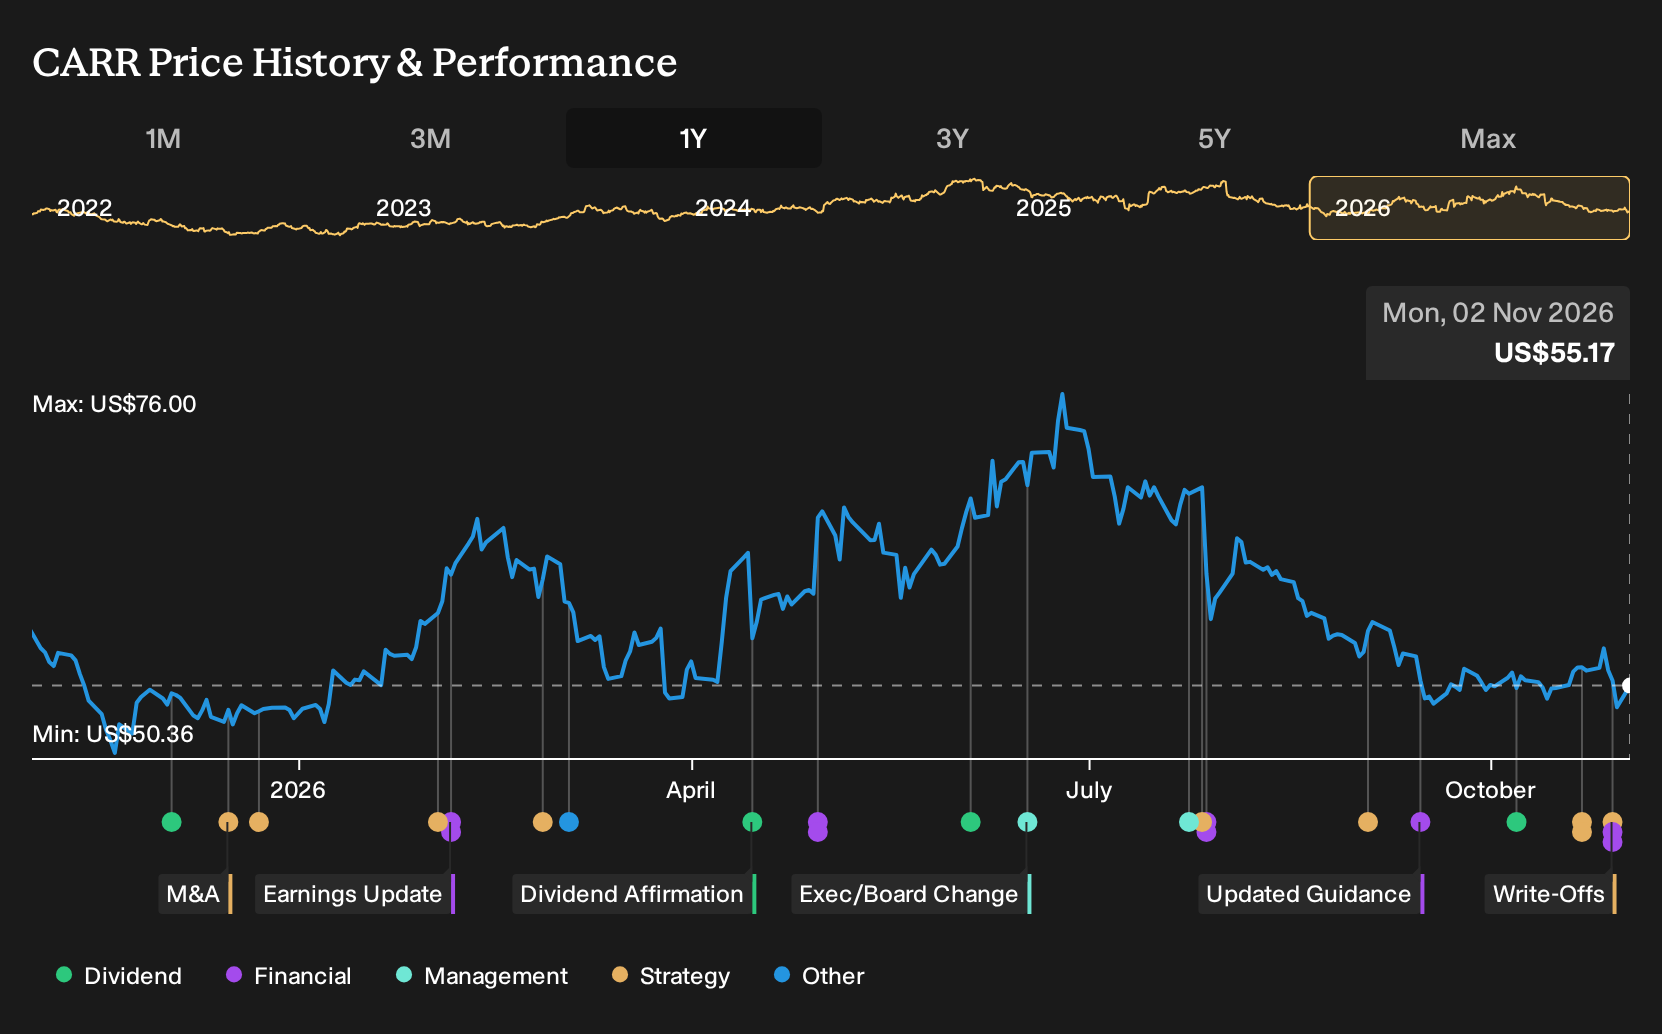
- Carrier Global has reported higher third quarter and year to date 2026 sales versus a year earlier, absorbed a US$3.1b non cash goodwill impairment in its European Climate Solutions unit, raised full year revenue guidance to US$23.8b to US$24.0b, and issued new callable senior unsecured fixed rate notes due 2029 and 2033.
- The combination of a heavier data center push, a record order backlog above US$8.5b, and expanded Fort Worth manufacturing investment indicates that Carrier Global is focusing on long term demand for advanced thermal management and intelligent energy solutions despite current reported losses.
- We will now look at how Carrier Global's raised 2026 sales guidance reshapes the broader investment narrative around growth and risk.
Scan beyond Carrier Global to compare how other infrastructure focused HVAC and energy efficiency players are positioned with our hand picked 43 power grid technology and infrastructure stocks.
Carrier Global Investment Narrative Recap
To own Carrier Global, you need to believe the core HVAC, data center cooling and energy efficiency businesses can turn a record backlog and raised 2026 sales guidance into cleaner earnings after a very heavy goodwill impairment. The immediate swing factor is execution on high demand areas like data center and North American residential while absorbing cost inflation.
The sharp move from prior profit to a reported net loss, driven largely by the US$3.1b non cash goodwill impairment, keeps the biggest risk squarely on margins and balance sheet flexibility. Any stumble in Europe margin work, or further pressure from tariffs and input costs, would make that profitability path much harder.
The fresh fixed rate senior unsecured notes due 2029 and 2033 now sit alongside higher capital spending plans and the more than US$600m Fort Worth expansion. That combination underlines how much Carrier Global is leaning on external borrowing rather than internal cash alone to fund capacity for data center and commercial cooling projects.
For you as a shareholder, the link to catalysts is straightforward. The new bonds can provide funding runway to build out the Fort Worth facility, meet the roughly US$2b data center sales commitment and work through the more than US$8.5b backlog. The trade off is that higher debt makes cost control, pricing power and consistent cash generation even more important.
Carrier Global Forecasts And What They Imply
Analysts are effectively asking you to underwrite a bigger Carrier Global by 2029, with their models pointing to US$27.3b of revenue and US$2.6b of earnings in that year. That profile rests on an assumed 7.2% yearly revenue growth rate and a move in profit from US$1.2b today to US$2.6b, an increase of about 2.2x in earnings over the period, using 2029 as the anchor forecast year.
Discover how Carrier Global's fair value indicates a 33% potential upside to its current price that may not be available for long.
Exploring Other Perspectives
One alternate take on Carrier Global is much less excited about data center demand. The most cautious analysts were only modeling roughly US$26.3b of 2029 revenue and US$2.2b of earnings before this goodwill hit and fresh bond funding. You can treat that sceptical view as a useful counterweight and explore how the new guidance and debt raise might shift those low end expectations.
Explore 4 other Carrier Global fair value estimates, including one that suggests as much as 9% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Carrier Global research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Carrier Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carrier Global's overall financial health at a glance.
Looking For More Investment Ideas Beyond Carrier Global?
Once you have formed a view on Carrier Global, it can help to line that thesis up against other opportunities using the Simply Wall St Screener so you see where the risk and reward profile feels most comfortable for you.
- If you care most about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) and see which businesses pair sturdy finances with consistent fundamentals.
- If you want potential mispricing opportunities, compare your view on Carrier Global with our 34 high quality undervalued stocks that filters for companies combining quality with attractive valuations.
- If reliable income is a priority, scan the 4 dividend fortresses to spot high yielding stocks that still pass basic strength and sustainability checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com