
European Registration Surge Could Be A Game Changer For Tesla (TSLA)
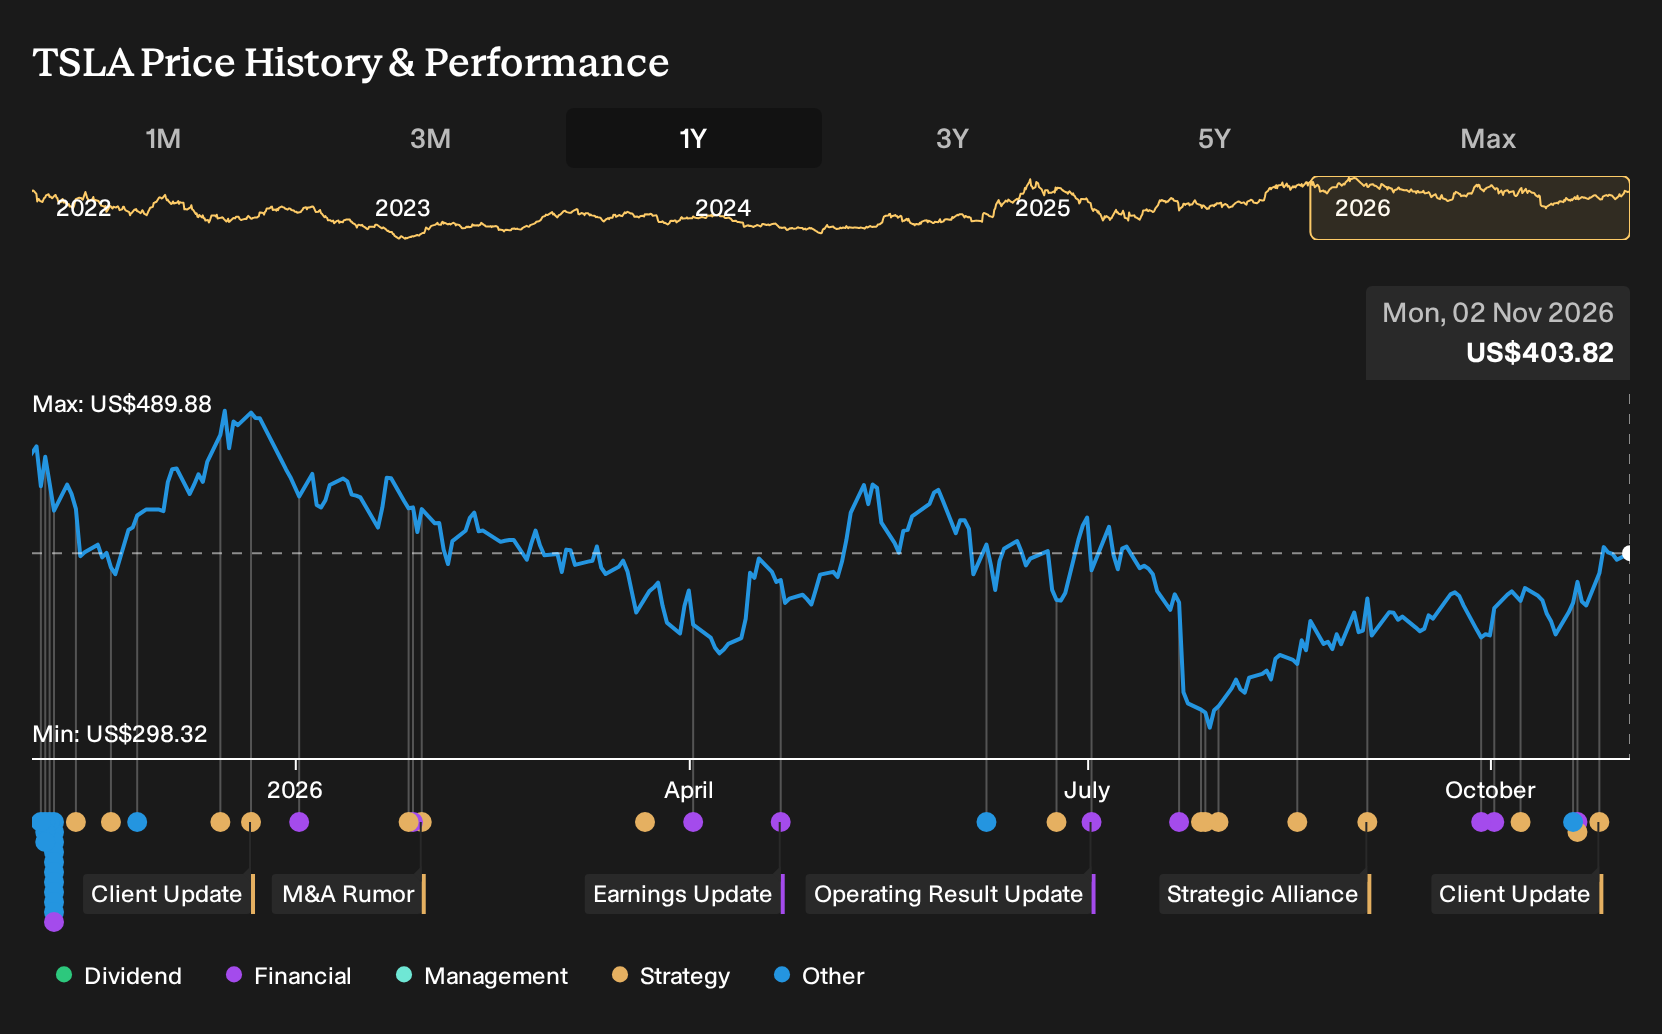
- Tesla reported mixed Q3 2026 results, with revenue at US$28.0b and net income at US$787m, while recent order data show a large four year high passenger vehicle backlog and sharp year over year gains in registrations across Sweden, Norway, and Denmark.
- Alongside this demand signal, Tesla is widening access to its autonomy stack through Cybercab expansion and Turo’s verified FSD (Supervised) rentals, which shifts more of the business toward higher margin software and services rather than only vehicle hardware.
- The focus now turns to how Tesla's stronger European registrations may reshape the investment narrative built around autonomy, software, and heavy capex.
Compare Tesla’s autonomy and EV developments with other potential breakouts in the space by reviewing our hand picked list of 53 AI infrastructure stocks.
Tesla Investment Narrative Recap
Tesla still asks investors to believe that heavy spending on autonomy, AI chips, and energy can turn into higher margin software and services layered on top of the EV base. Q3 results reflected some strain. Net income of US$787m on US$28.0b of revenue and thinner margins keeps the near term focus on how quickly these newer lines can support earnings.
The most important short term catalyst remains execution on Cybercab and FSD at scale, since these offerings are meant to justify the large capital expenditure and margin narrative. The biggest risk is that elevated spending above US$25b this year continues while core automotive volumes and profitability in the U.S. and China remain under pressure.
The Turo launch of verified Tesla FSD rentals in the U.S. speaks directly to that thesis. It puts FSD (Supervised) in front of travelers who might never own a Tesla, using API verified listings and offering free one month FSD trials for eligible hosts. That is a pure product in hand experience rather than a slide in an earnings deck.
This move also highlights the operational tension. Wider exposure can support FSD subscription adoption and recurring revenue if users are satisfied, yet recent reports of FSD v14.3.13 regressions and safety complaints underline the execution risk. For investors, Turo functions both as a potential demand catalyst and as a live test of whether Tesla’s autonomy software is ready for broad use.
Tesla’s Long Range Earnings Story
Tesla’s narrative projects US$185.3b in revenue and US$17.8b in earnings by 2029. That profile reflects analyst assumptions of 21.4% yearly revenue growth and an earnings increase of about US$14.6b from US$3.2b today.
Discover why Tesla's fair value suggests that Tesla is currently priced fairly in the market.
Exploring Other Perspectives
One alternate view puts regulatory risk front and center. The most cautious Tesla analysts worry that fresh scrutiny of Cybercab approvals and FSD safety could slow autonomy rollouts and keep 2029 earnings closer to US$4.6b on about US$136.0b of revenue, rather than the US$17.8b story. These forecasts were set before the Turo FSD launch, so you can expect opinions to evolve as new data arrives.
Explore 31 other Tesla fair value estimates, including one that suggests as much as 69% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Tesla research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Tesla. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tesla's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tesla?
If the Tesla story has sharpened your thinking about risk, reward, and time horizon, it can be useful to compare that with other opportunities. The Simply Wall St Screener lets you scan for companies that fit very specific criteria so you can build a watchlist that actually matches your own thesis rather than someone else’s.
- If you want potential mispricing on your side, you could start with companies that combine strong fundamentals with a discount to their estimated worth by reviewing our hand picked 34 high quality undervalued stocks.
- If capital preservation ranks high for you, you might narrow the field to businesses with sturdier balance sheets by scanning our focused list of solid balance sheet and fundamentals (24 results).
- If you are hunting for under the radar ideas, you could broaden your research with our curated 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com