
This Data Center and Storage Stock Just Raised Its Dividend by Nearly 17%
Western Digital’s (WDC) strong quarter is bringing shareholders a bigger payout. The storage company raised its quarterly dividend by nearly 17% after reporting 55% revenue growth and a 161% jump in adjusted earnings per share for fiscal Q1 2027.
The company expects sales to keep growing, projecting revenue of $5.1 billion at the midpoint for the current quarter as customer demand stays strong and margins improve. CEO Irving Tan said the higher payout reflects confidence in the business and a commitment to returning cash to shareholders.
That gives shareholders more income, but buying the stock means betting on more than a bigger payout. Can Western Digital keep growing enough to make its shares worth buying? Let’s get into the details.
Can Western Digital’s Numbers Support the Increase?
Western Digital, based in San Jose, California, has a market value of $137 billion and sells data center drives, storage platforms, and internal and external hard drives to cloud providers, businesses, and consumers in markets around the world.
Despite some recent volatility, WDC stock has still gained 100% year-to-date (YTD) and 130% over the past 52 weeks.
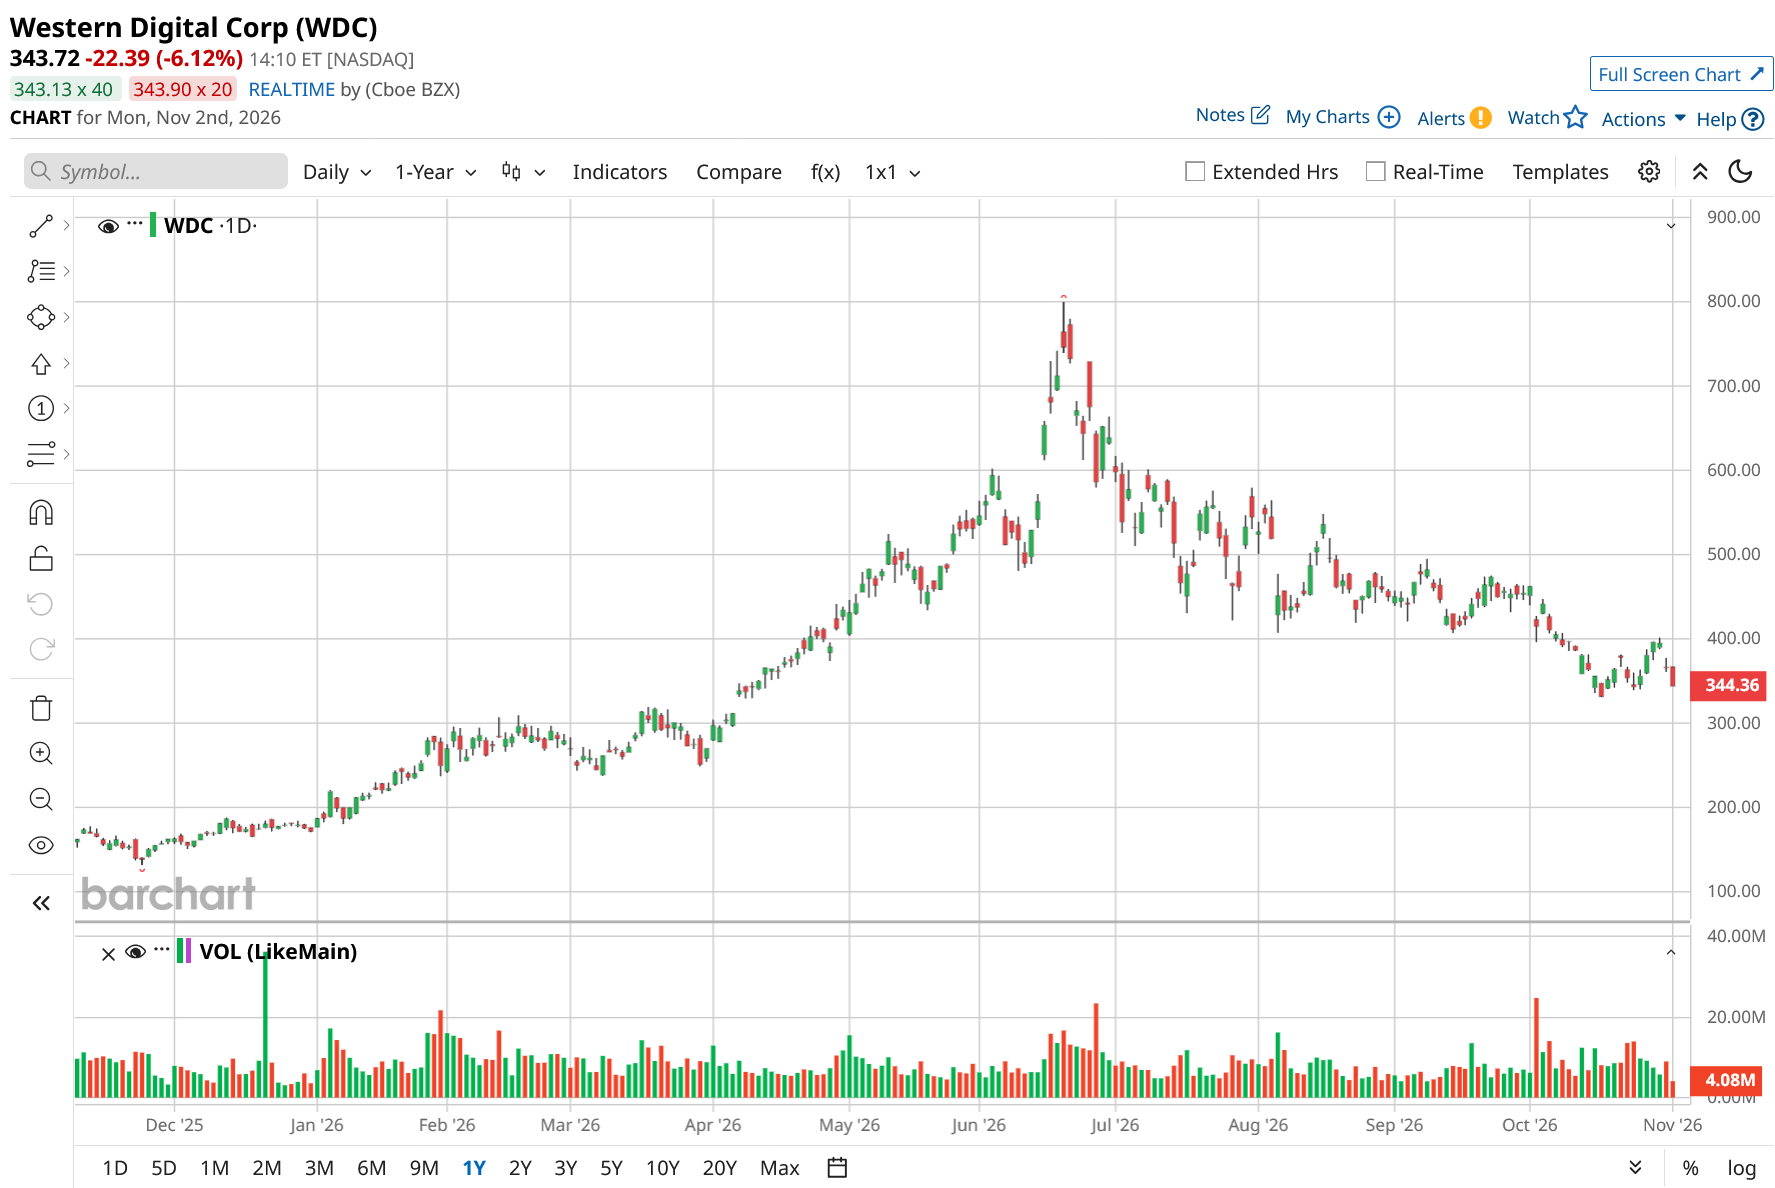
Those gains have made the stock pricier than its sector. WDC trades at 31.61x trailing earnings and 32.28x cash flow, above sector medians of 23.13x and 18.71x, respectively.
Western Digital announced a 16.7% dividend increase on Oct. 22, lifting its quarterly payment from $0.15 to $0.175 per share and its annualized payout from $0.60 to $0.70. Its most recent dividend was $0.15 per share, listed with a Sept. 8, 2026 date. The new dividend is payable on Dec. 17 to shareholders of record at the close of business on Dec. 4.
Western Digital reported fiscal Q1 2027 results on Oct. 22, with revenue rising 55.5% from a year earlier to $4.38 billion. That exceeded the $4.16 billion consensus by 5.2% and gave the company a stronger sales base.
CEO Irving Tan said demand was spreading beyond cloud and hyperscale customers into enterprises, neocloud providers, and AI frontier labs.
WDC’s adjusted EPS reached $4.64, beating expectations of $4.10 by 13.3%. The adjusted operating profit of $2.15 billion also surpassed the $1.92 billion estimate by 12.3%, producing a 49.1% margin.
This improvement extended beyond adjusted results, as the reported operating margin rose to 46.7% from 28.1% a year earlier.
Western Digital expects that momentum to continue, forecasting next quarter's revenue to reach $5.1 billion at the midpoint, comfortably above the $4.58 billion analysts anticipated. It also guided for an adjusted EPS of $5.80, compared with expectations of $4.82.
What Keeps Business Growing
Western Digital stands to benefit as customers store more data. In May, management said it expected storage capacity demand to grow more than 25% annually over three to five years, up from its earlier forecast in the mid-teens. That is a demand forecast, not a revenue forecast, but it suggests AI is increasing the need for storage.
To meet that need, the company is developing drives that hold more data. Its plans include 40-terabyte drives using enhanced perpendicular magnetic recording, which packs more information onto each disk. That lets customers add storage without requiring as much extra equipment or space.
Western Digital also plans to introduce 44-terabyte drives in 2027 using heat-assisted magnetic recording. This method uses heat to help fit more data onto a disk. Longer term, the company aims to move beyond 100 terabytes per drive, though those capacities are still development targets.
These upgrades could encourage customers to replace older drives as their storage needs grow. Getting the products out on time could help Western Digital sell more storage and generate more cash to reinvest and return to shareholders.
Wall Street Weighs WDC’s Upside
Western Digital is expected to report earnings on Feb. 4, 2027, and analysts see a big increase ahead. They expect earnings of $5.63 per share for the December 2026 quarter, up 182.91% from $1.99 a year earlier.
That growth outlook has kept analysts positive, although concerns about future supply have tempered some expectations. Wells Fargo cut its price target on WDC stock by $280, or 38.36%, from $730 to $450, though the revised target still implies 22.91% upside on Oct. 16, and its analysts kept their “Overweight” rating.
Still, Wells Fargo expects revenue growth of 25% to 30% or more, with gross margins reaching 60% to 65% or higher. Those estimates suggest the firm still expects strong business performance despite seeing less upside in the shares.
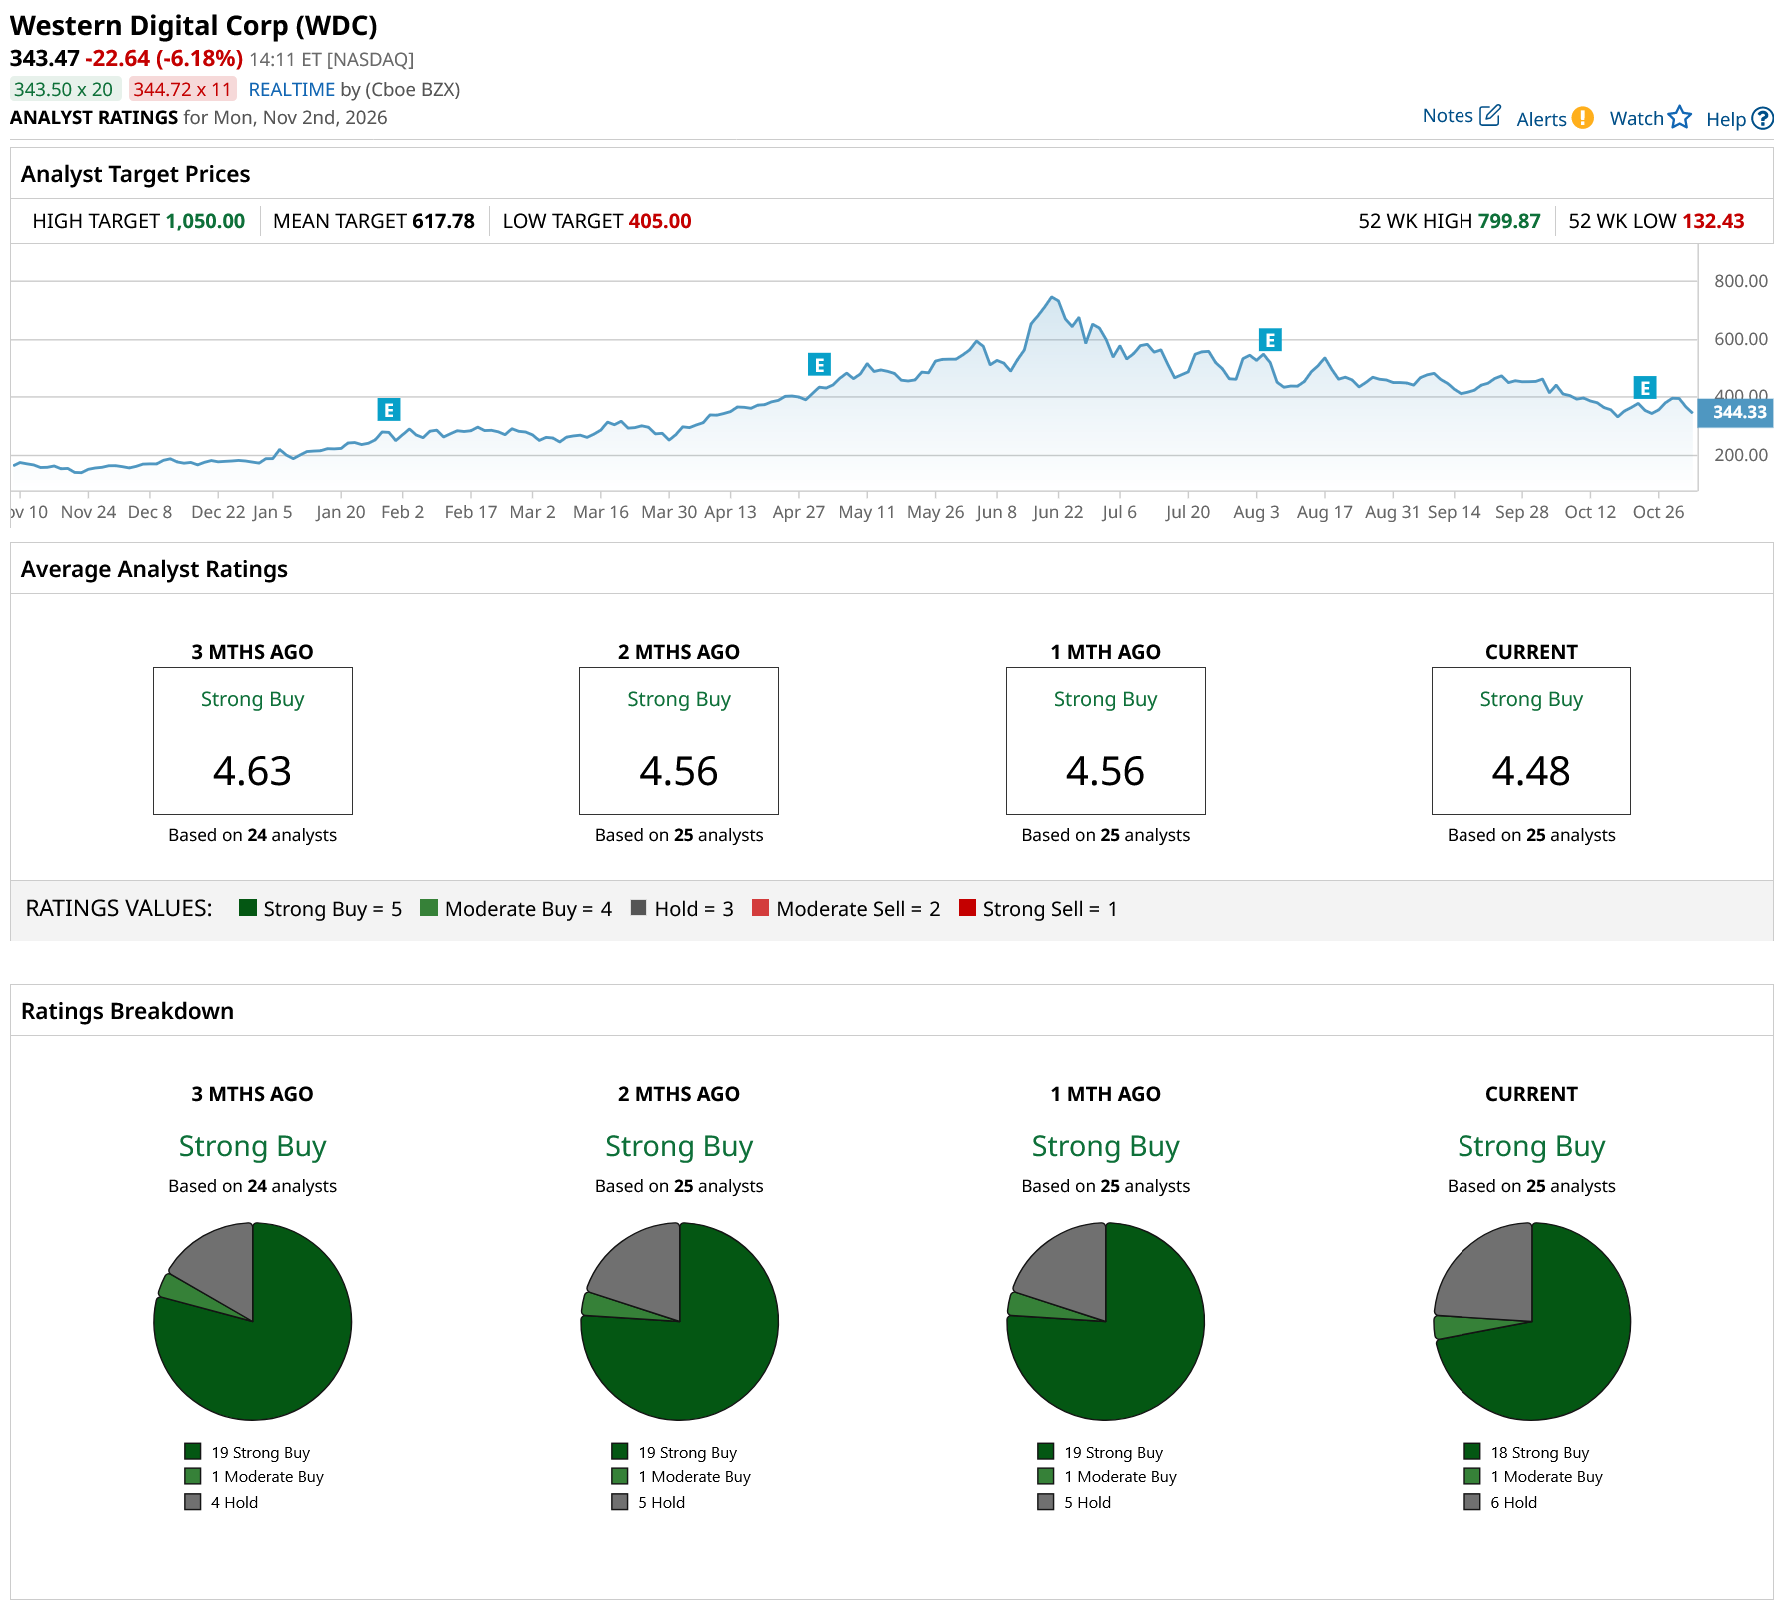
That confidence extends beyond Wells Fargo. The consensus among 25 analysts remains “Strong Buy,” with an average price target of $617.78. That implies an 80% upside from WDC stock's Monday afternoon price of 343.47.
Conclusion
Western Digital’s dividend raise is welcome, but the real prize is selling more storage without building proportionately more factories. That could leave more cash available for shareholders as demand grows. WDC stock looks worth considering, although its premium valuation makes the entry price important. Higher capacity drives and customer commitments indicate the business is more likely to keep expanding than lose momentum. The dividend sweetens the deal, but the stock needs earnings to keep doing the heavy lifting from here onward.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.