
Earnings Update Might Change The Case For Investing In ConnectOne Bancorp Stock (CNOB)
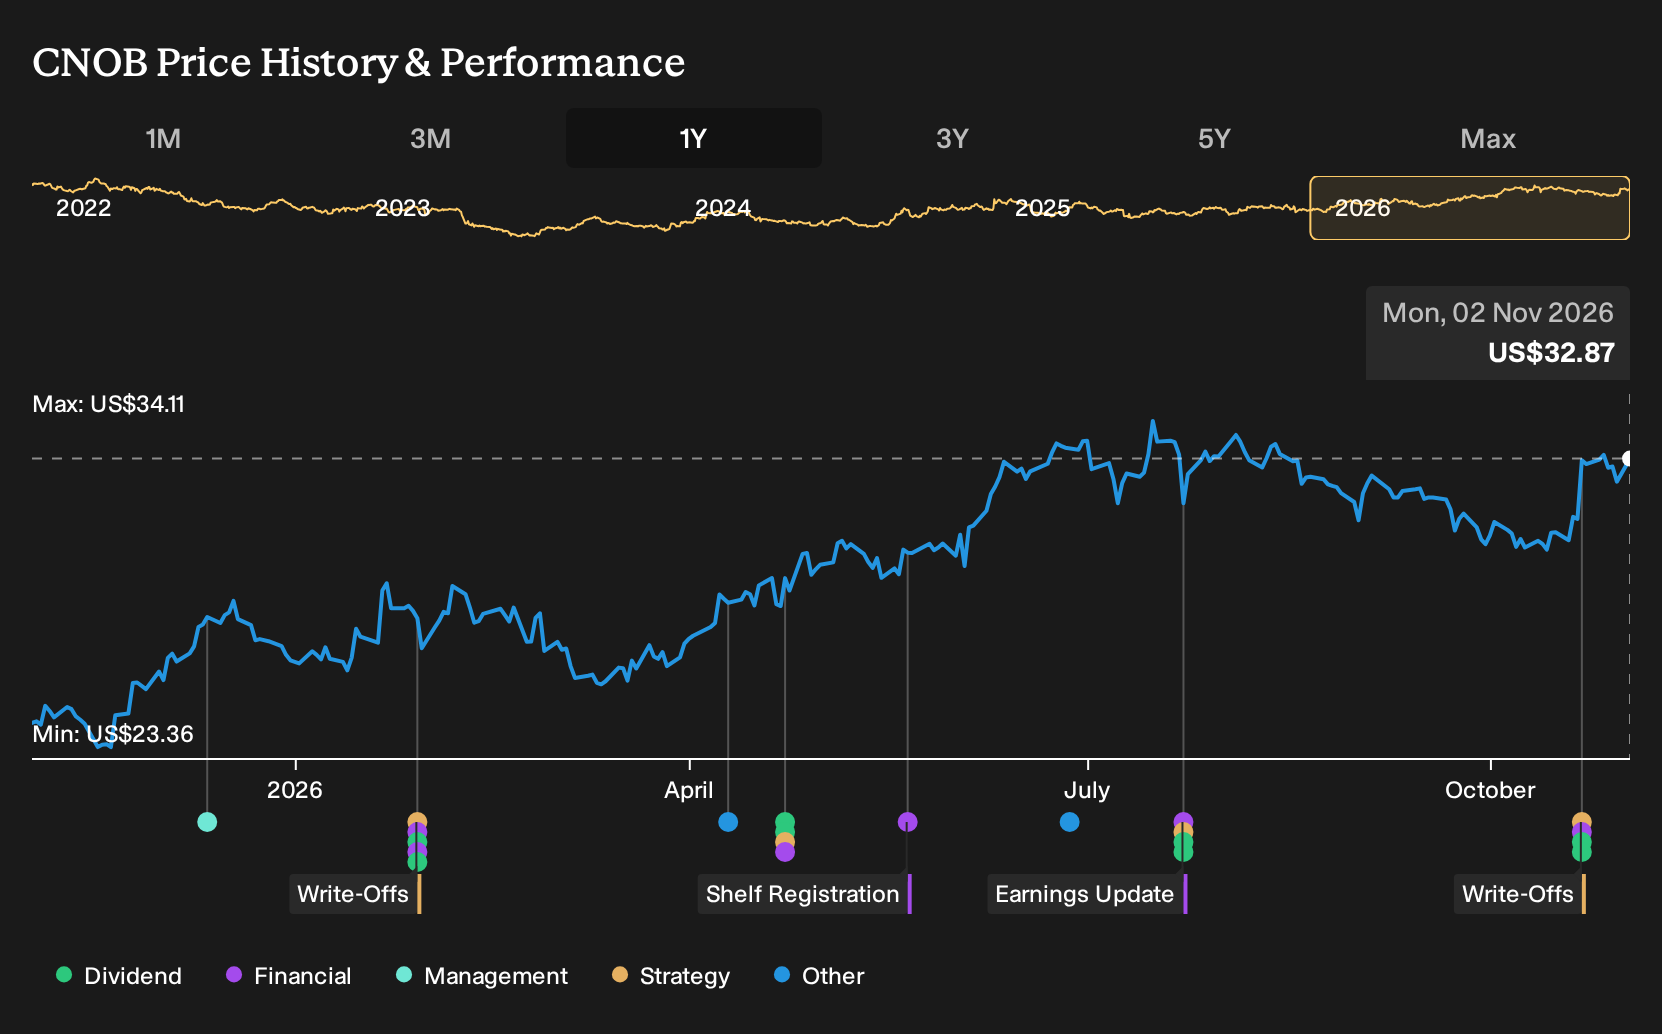
- ConnectOne Bancorp reported third quarter 2026 results with net interest income of US$117.3 million, net income of US$31.4 million, lower net loan charge offs of US$2.24 million, and affirmed dividends on both common and Series A preferred shares, alongside continued share repurchases.
- Despite reduced quarterly net income compared with a year earlier, ConnectOne Bancorp reported much higher nine month net income of US$110.89 million, while still recording loan charge offs and actively returning capital through cash dividends and a long running buyback program.
- The focus now turns to how ConnectOne Bancorp’s mixed earnings profile, including higher net interest income, fits within its existing investment narrative.
Compare ConnectOne Bancorp’s capital returns and credit costs with a curated 29 resilient stocks with low risk scores built around resilient balance sheets and disciplined risk management.
ConnectOne Bancorp Investment Narrative Recap
For ConnectOne Bancorp, you essentially need to believe the bank can keep turning its larger balance sheet, loan repricing pipeline and efficiency focus into resilient earnings while managing credit and funding pressure in its New York metro footprint. The latest quarter supports that story around net interest income, while the slight drop in quarterly profit keeps attention on execution rather than changing the thesis.
The clearest near term swing factor remains credit quality in commercial real estate and rent stabilized multifamily. Lower net loan charge offs in the third quarter help, but they do not remove that risk. Deposit pricing and competitive funding costs appear to be the other key watchpoint over the next few quarters.
The most relevant recent signal for that thesis is the common dividend affirmation at US$0.195 per share for payment on 1 December 2026. Management is choosing to keep returning cash to equity holders while credit costs, though reduced, still matter, which highlights confidence in current earnings power and capital levels.
For shareholders, that payout policy ties directly into the main catalysts around loan repricing, cost discipline and capital build. If those levers keep working and credit losses remain contained, the combination of regular cash dividends with selective buybacks adds another layer to the ConnectOne Bancorp story, even as the rent stabilized book and funding competition remain active risks.
ConnectOne Bancorp's narrative projects US$619.8 million revenue and US$226.0 million earnings by 2029. This assumes 11.8% yearly revenue growth and an earnings increase of about US$72.4 million from US$153.6 million today.
Uncover why ConnectOne Bancorp's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$36.75 to about US$59.27 per share, so retail opinions on ConnectOne Bancorp already stretch from cautious to optimistic. Considering that spread alongside ongoing credit risk in commercial real estate and recent preferred and common dividends, you are looking at genuinely different playbooks. Explore those contrasting viewpoints before deciding where your own conviction sits.
Explore 2 other ConnectOne Bancorp fair value estimates, including one that suggests it could be worth just $36.75.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ConnectOne Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ConnectOne Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ConnectOne Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond ConnectOne Bancorp?
Once you have a view on ConnectOne Bancorp, it helps to compare that thesis with other companies that share similar qualities or offer very different risk and return profiles. The Simply Wall St screener can surface a range of opportunities so you can stress test your thinking rather than anchoring on a single stock.
- For investors who care most about quality at a reasonable entry point, compare ConnectOne Bancorp with a curated list of 34 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- If income reliability is your anchor, contrast ConnectOne's payout profile with 4 dividend fortresses that focus on higher yields and consistency of distributions.
- When balance sheet strength is the priority, set ConnectOne Bancorp alongside a list of solid balance sheet and fundamentals (24 results) to see which businesses carry the most robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com