
What Clarivate (CLVT)'s Copilot Integration Means For Shareholders
- Clarivate announced that its CompuMark trademark data and insights are now accessible within Microsoft Copilot through the IPOne connector, bringing curated IP intelligence directly into AI-supported workflows for corporate IP teams and law firms.
- The IPOne integration, developed with input from 15 Fortune 500 IP departments and leading law firms, highlights Clarivate's focus on embedding subscription-style data services directly into everyday legal and corporate decision tools.
- We will now examine how Clarivate's investment narrative could be influenced by embedding CompuMark data directly into Microsoft Copilot workflows.
See how Clarivate's Copilot move fits into the wider AI workflow race by reviewing a curated set of 53 AI infrastructure stocks that are already wiring data directly into enterprise decision tools.
Clarivate Investment Narrative Recap
An investor in Clarivate needs to believe the shift toward AI centric, subscription heavy workflows can offset pressure in legacy research products and a forecast revenue decline of 6.2% per year over the next 3 years. The Copilot integration fits that story but, on its own, does not materially change the near term earnings picture or the fact that Clarivate remains loss making.
The biggest near term swing factor is execution on portfolio simplification and cost discipline, while servicing debt from higher risk funding. The key risk is that divestitures, university budget constraints and free data alternatives weigh on renewals faster than AI powered tools like IPOne and CompuMark can support pricing power and retention.
The Copilot announcement connects most directly to Clarivate's broader push into AI driven analytics across Web of Science, Derwent and Cortellis. Management is trying to put curated IP data directly into customer workflows. This lines up with the catalyst of tighter workflow integration and more recurring SaaS style revenue rather than transactional services.
For you, the practical question is whether integrations like IPOne can meaningfully differentiate Clarivate against AI powered competitors before commoditisation and Open Access pressures bite harder. If that integration gains traction with the 15 Fortune 500 IP teams already engaged, it could support renewal resilience in the IP segment, which matters given revenue is currently expected to contract.
Clarivate's current loss of $334.0 million is set against analyst expectations for earnings of $133.8 million by 2029. This implies an earnings improvement of about $468 million, alongside a forecast 6.9% yearly revenue decline that would still leave the business at roughly $2.0b of revenue in that same year.
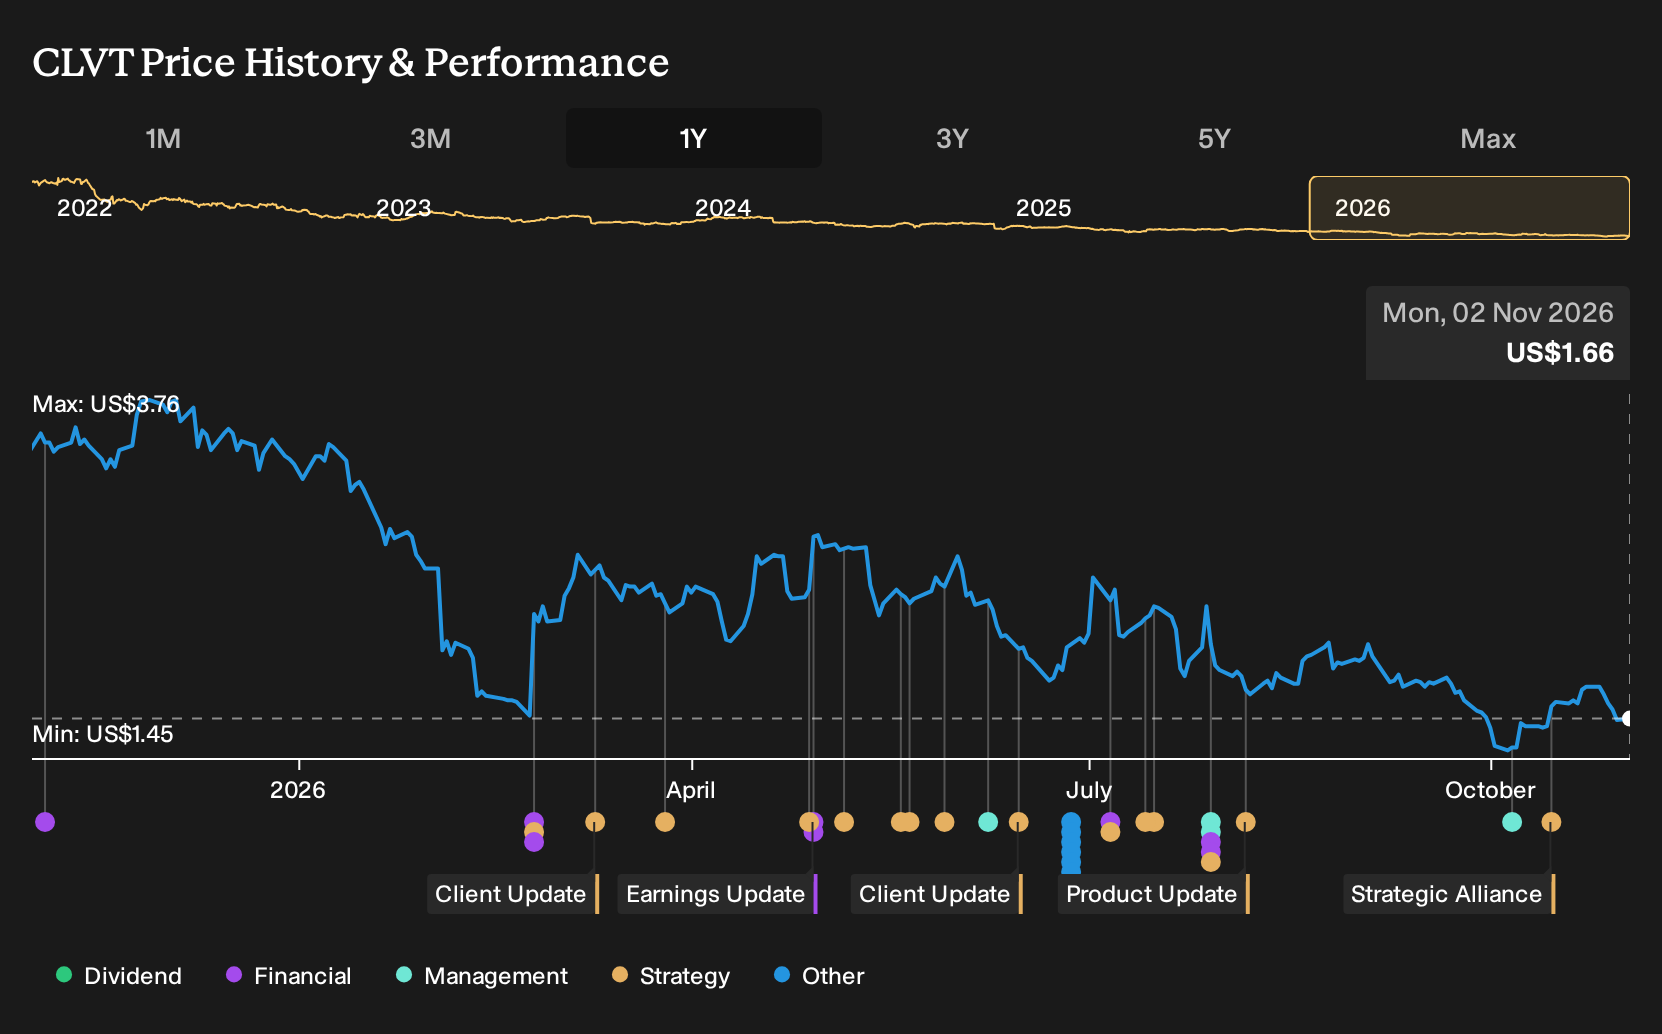
Uncover why Clarivate's fair value indicates a 79% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You might see the Copilot news and focus on upside, yet the lowest Clarivate forecasts lean hard into cash strain. Those analysts were assuming revenue would fall about 7.0% a year and still only reach earnings of about US$131.4 million by 2029. That is a more cautious story. Use it as a prompt to compare several viewpoints before deciding how this AI integration might reshape your own expectations.
Explore 3 other Clarivate fair value estimates, including one that suggests it could be worth just $2.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your Clarivate research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Clarivate. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Clarivate's overall financial health at a glance.
Looking For More Ideas Beyond Clarivate?
If this Clarivate story has you rethinking where AI, cash flow resilience and balance sheet strength fit in your portfolio, it can help to line it up against other stocks with very different profiles.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) that can handle shocks without constant refinancing risk.
- If long term compounding is the priority, scan a 33 high quality undervalued stocks that combine quality fundamentals with prices that still sit below many intrinsic value estimates.
- Income focused readers can zero in on a 4 dividend fortresses that aim to balance yield with balance sheet strength rather than just chasing the highest payout.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com