
Could Pen Gold Expansion Just Shift Barrick Gold's (TSX:ABX) Investment Narrative?
- Barrick Gold has agreed to expand its 2027 exploration work at the Pen Gold Project under an earn in deal with GFG Resources, committing at least C$4.0 million including 5,000 meters of drilling over three years.
- The decision to fund property wide geophysics, systematic till sampling, mapping and late 2027 diamond drilling highlights that Barrick Gold is willing to front load exploration spending to secure longer term resource options in its pipeline.
- We will now examine how Barrick Gold’s multi year C$4.0 million Pen Gold commitment could influence the investment narrative around its project pipeline.
Scan other gold producers that could be setting up their next resource pipeline with targeted exploration, starting with the curated list of 34 elite gold producer stocks.
Barrick Mining Investment Narrative Recap
To own Barrick Mining, you need to believe its mix of Tier 1 gold and copper assets, measured project pipeline and technology roll out can keep cash generation resilient through cycles. The Pen Gold commitment sits on the fringes of that story. It adds long dated optionality but does not alter the near term production or cost profile.
In the short term, the key swing factor remains execution at large existing operations and projects such as Lumwana and Pueblo Viejo, along with cost control in a still inflationary input backdrop. The main operational risk stays concentrated in higher risk jurisdictions and in balancing dividend and buyback ambitions against heavy project spending, rather than in early stage Canadian exploration.
The most relevant reference point for Pen Gold is Barrick Mining’s broader organic growth work, especially Fourmile in Nevada, where drilling has expanded and pre feasibility work targets completion by 2028. That program already signals a preference for adding ounces within existing hubs, using known infrastructure and geological models to support the next phase of production.
Pen Gold fits beside this as another exploration shot, not a core near term catalyst. The earn in spend sits alongside big ticket capital items such as the Lumwana Super Pit expansion and any future decision on Reko Diq. For you as a shareholder, the practical question is whether Barrick maintains discipline across these parallel commitments so operating performance, balance sheet strength and shareholder returns remain aligned.
How Pen Gold Sits Inside the Barrick Mining Consensus Story
Analysts are already baking a fairly clear roadmap into their Barrick Mining models, and Pen Gold slots in as an extra call option on top of that rather than the main event. The current consensus assumes that revenue grows at 8.5% a year over the next three years, that profit margins tighten a little from 31.6% today to 29.9% by 2029, and that earnings rise from US$6.5b now to US$7.9b by that same 2029 yardstick. That US$1.4b earnings uplift, along with a planned 2.46% annual reduction in share count, is what underpins the expected earnings per share of US$4.96.
Against those metrics, the Pen Gold earn in looks small in dollar terms but useful in portfolio terms. It gives Barrick Mining another option to support future tonnes without analysts needing to assume any specific production or cash flow from the project in the US$26.4b revenue and US$7.9b earnings figures tied to 2029. The core model already leans on assets like Lumwana, Pueblo Viejo, Nevada Gold Mines and the copper projects, then layers on technology, mine planning discipline and capital allocation choices as the key drivers of whether those numbers hold.
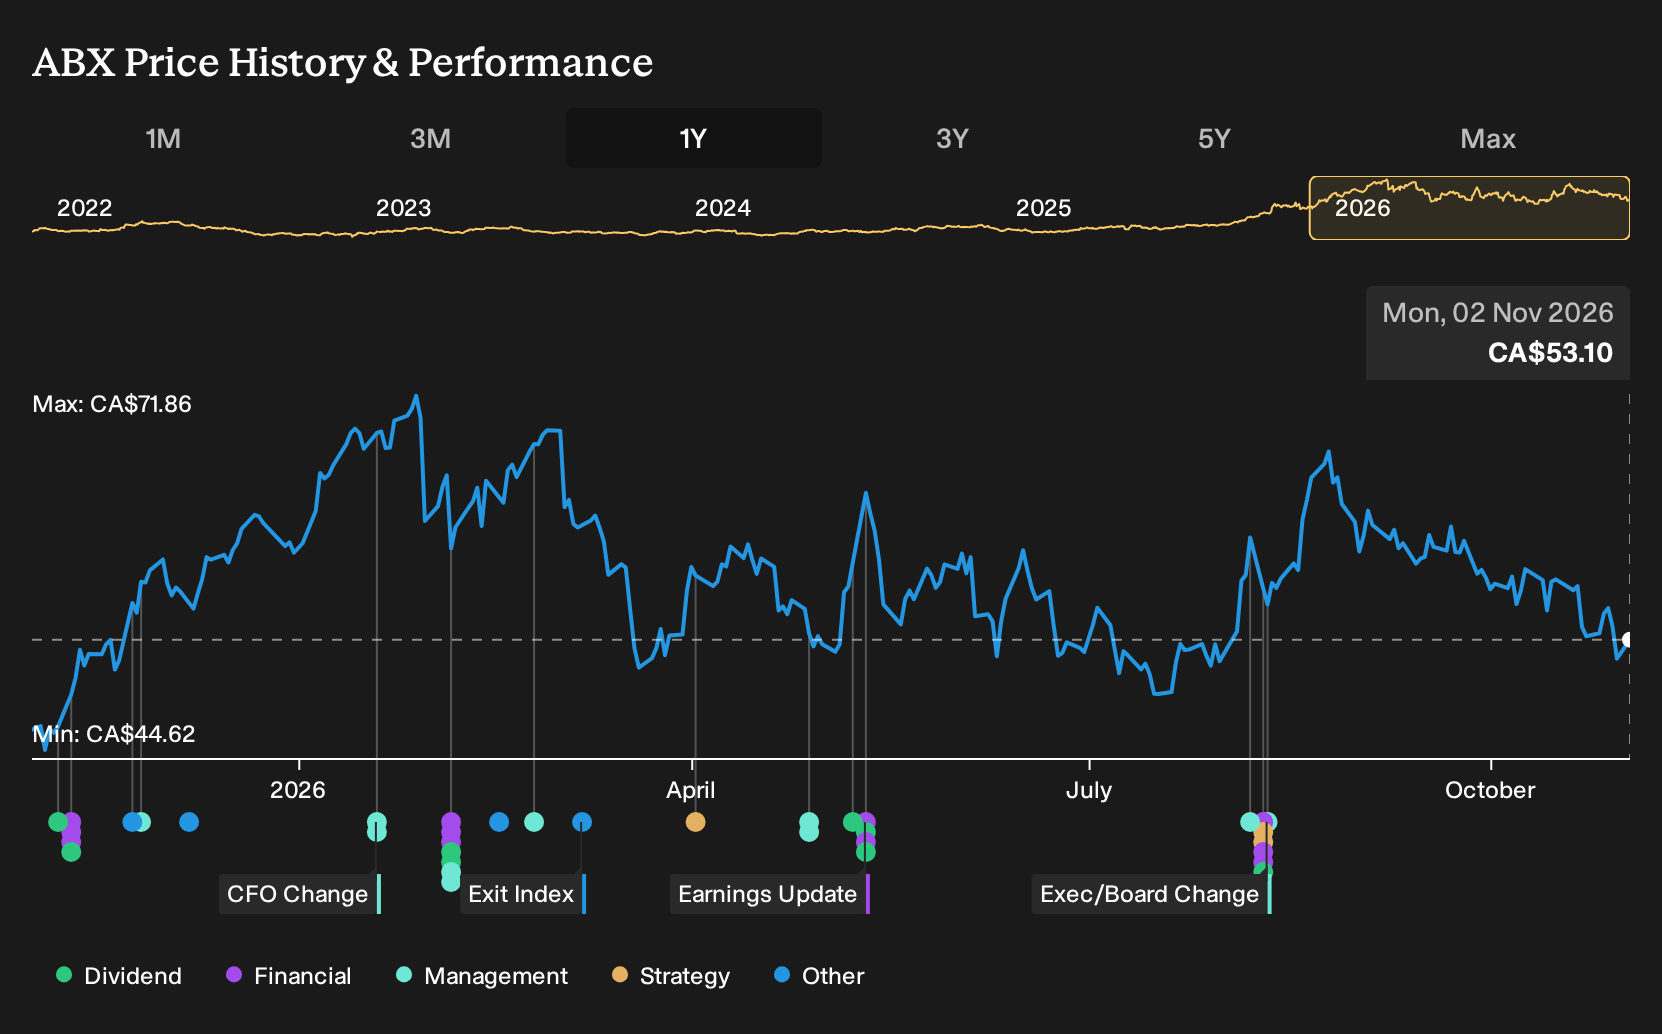
What Pen Gold really does is slightly fatten the tail of possible outcomes. It increases the range of ways Barrick Mining might reach or reshuffle that forecast production mix if some other initiative underdelivers or project timing moves. That flexibility can matter if you are weighing up the analysts’ consensus price target of CA$65.43 against the current share price of CA$53.60 and asking how much optionality is quietly embedded in the project list that sits behind those headline figures.
Analysts are also assuming the market is willing to pay a higher multiple on those forecast earnings. To reach their target, Barrick Mining would need to trade on a P/E of 11.4x by 2029 compared with 9.6x today, still below the current 14.2x for the broader Canadian metals and mining group. That gap gives you one simple cross check. If you think the exploration pipeline, including Pen Gold, improves the quality and durability of future cash flows, then a modestly higher P/E on those earnings is not an especially aggressive stretch. If you take a more cautious view on execution, jurisdiction risk or project complexity, the 11.4x assumption may feel full enough already.
Barrick Mining's narrative projects US$26.4b revenue and US$7.9b earnings by 2029. This rests on 8.5% yearly revenue growth and an earnings increase of about US$1.4b from US$6.5b today.
Uncover how Barrick Mining's fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Barrick Mining focuses less on exploration risk and more on how cash returns could evolve. Before this Pen Gold news, the most optimistic analysts were already pencilling in revenue of about US$29.1b and earnings of US$8.6b by 2029. You might see this new C$4.0 million exploration spend as either a small distraction from those cash return hopes, or an extra way to support them over time. Both readings are valid, which is why it helps to compare several viewpoints rather than lean on a single forecast.
Explore 6 other Barrick Mining fair value estimates, including one that suggests potential upside of up to 57% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Barrick Mining research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Barrick Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Barrick Mining's overall financial health at a glance.
Looking For More Investment Ideas Beyond Barrick Mining?
If the Barrick Mining story has sharpened your focus on project quality, balance sheet strength and capital discipline, it can help to line it up against other opportunities using the Simply Wall St Screener. You can quickly filter for different styles of stocks that fit your own risk tolerance and income goals, then compare their fundamentals side by side.
- For investors who want potential mispricing combined with solid fundamentals, start by scanning a curated set of 5 high quality undervalued stocks that pass tight quality checks.
- If resilience matters more to you than excitement, you can focus on companies that have weathered past cycles well by reviewing our 9 resilient stocks with low risk scores as a filter for sturdier balance sheets and earnings profiles.
- Income focused readers who care about reliability as much as yield can review 3 dividend fortresses that aim to pair higher payouts with more robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com