
Q3 Revenue Miss Might Change The Case For Investing In RenaissanceRe Holdings (RNR)
- RenaissanceRe Holdings reported third quarter 2026 revenue of US$1.69b and a net loss of US$152.54m, with management pointing to planned casualty pullbacks, softer property catastrophe rates, and large specialty losses tied to the Middle East conflict and a gas facility explosion in Qatar.
- The reinsurance group combined this weaker quarter with a completed US$1.37b buyback that retired 10.5% of its shares. This tighter equity base comes at a time when earnings are becoming more dependent on disciplined underwriting and investment income rather than top line expansion.
- We will look at how RenaissanceRe Holdings' investment narrative is affected by the Q3 specialty losses and revenue shortfall.
See how RenaissanceRe Holdings compares with other insurers facing similar underwriting and catastrophe risks by reviewing our curated list of 29 resilient stocks with low risk scores.
RenaissanceRe Holdings Investment Narrative Recap
To stay invested in RenaissanceRe Holdings, you need to be comfortable with a business that leans heavily on disciplined catastrophe underwriting and investment income, rather than chasing premium volume. The short term swing factor is whether recent large losses and softer property rates stay contained enough for the three driver model of underwriting, fee income, and portfolio returns to work together.
The biggest operational risk is that catastrophe clusters or social inflation in casualty lines push loss ratios higher just as operating expenses step up to a 5.0% to 5.5% expense ratio. The Q3 loss, driven by Middle East and Qatar events plus mark to market hits, directly illustrates how sensitive earnings remain to severe events.
The most relevant fresh data point is the Q3 2026 report itself. Revenue for the quarter came in at US$1.69b compared with US$3.20b a year earlier, and the firm moved from net income of US$916.51m to a net loss of US$152.54m. That shift, paired with a basic loss per share of US$4.02 from continuing operations, puts execution risk around underwriting and portfolio positioning into sharper focus.
Across the first nine months of 2026, RenaissanceRe Holdings reported revenue of US$6.65b and net income of US$803.92m, with basic earnings per share from continuing operations of US$18.47. Those figures sit alongside a completed US$1.37b buyback that retired 10.5% of shares, which means future catalysts, good or bad, now flow through a meaningfully smaller equity base.
What The Current Analyst Narrative Implies For RenaissanceRe Holdings
RenaissanceRe Holdings' current analyst narrative is anchored on a view that both revenue and profitability step down from today's levels over the next few years. Consensus models point to revenue of US$7.3b and earnings of US$1.3b by 2029, using a discount rate in the low 7% range and a higher future P/E multiple to bridge from earnings power to today’s quoted price.
Across those same models, analysts assume revenue will fall by 13.1% per year and that profit margins contract from 22.9% today to 17.7% by 2029. Earnings are projected to move from US$2.6b today to US$1.3b by that date, which is a decline of about US$1.3b in absolute terms, even before factoring in the forecast 7% annual reduction in share count over the next three years.
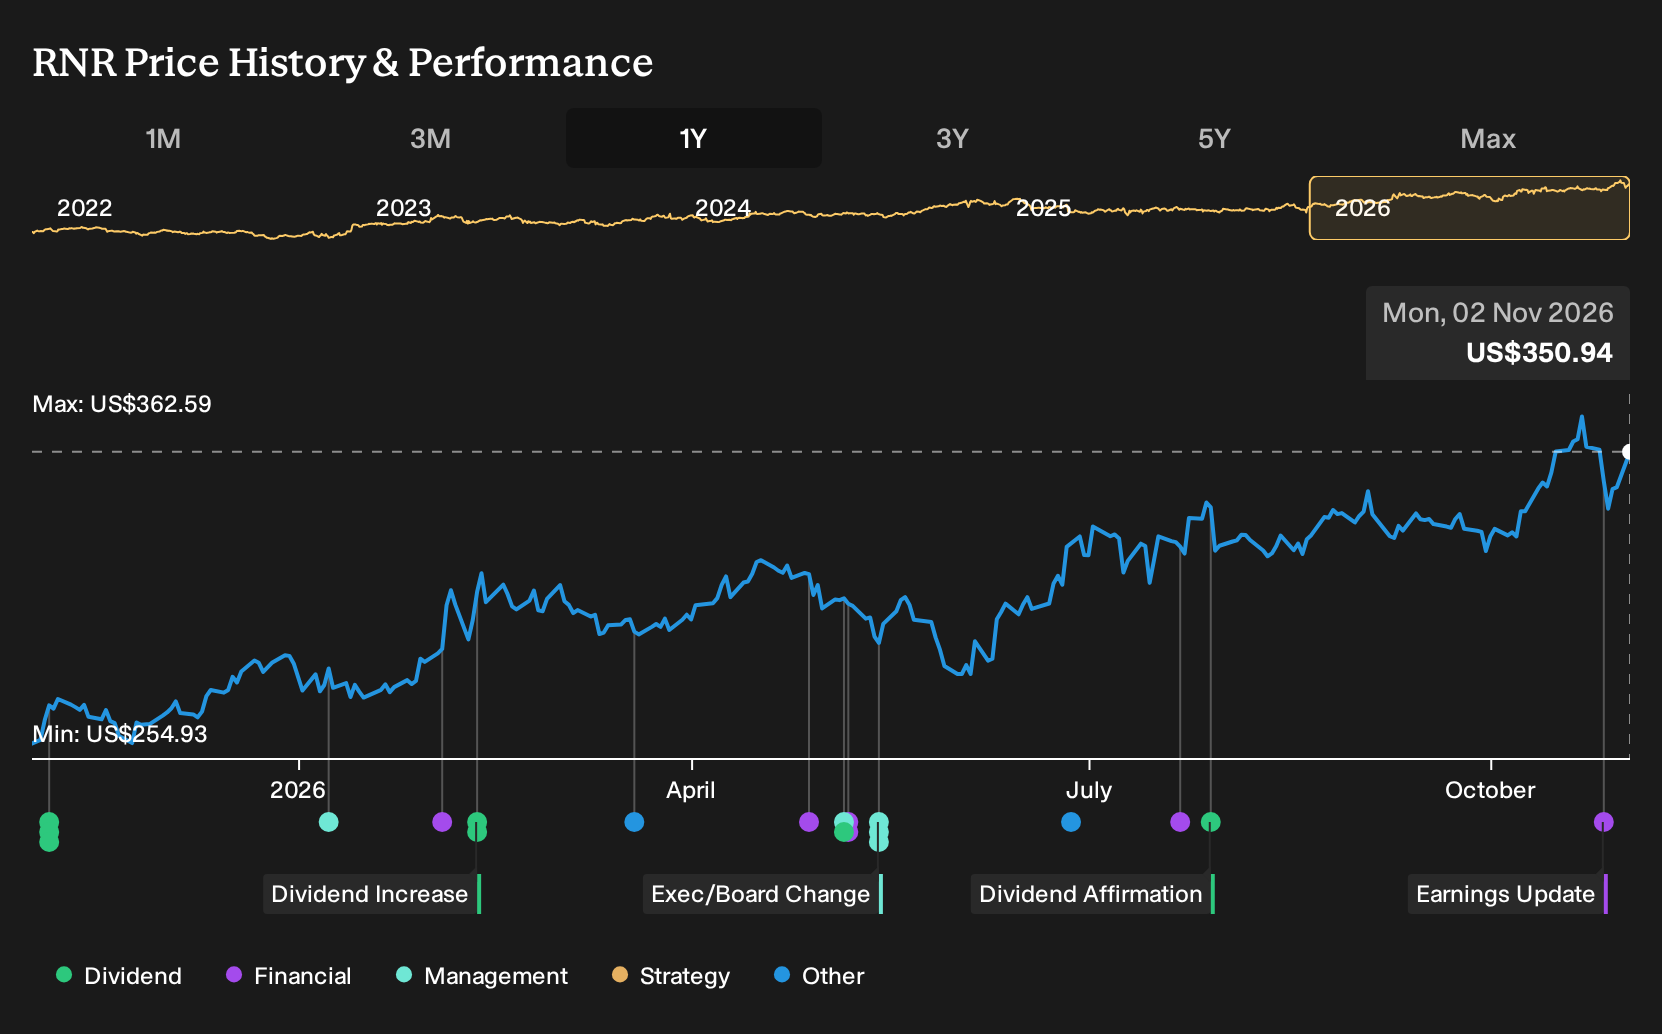
Put together, RenaissanceRe Holdings is framed as a reinsurer where future upside depends less on top line expansion and more on how investors value a shrinking earnings base, thinner margins, and a smaller equity float. The consensus price target of US$347.31 versus a spot share price of US$322.99, with a range from US$312 to US$422, reflects a view that the stock is broadly in line with these assumptions. That leaves you to judge whether the embedded 2029 story feels conservative, aggressive, or about right.
RenaissanceRe Holdings is expected to generate US$7.3b in revenue and US$1.3b in earnings by 2029, based on current analyst models. That framework includes a forecast annual revenue decline of 13.1% and an earnings decrease of about US$1.3b from current earnings of roughly US$2.6b.
Discover why RenaissanceRe Holdings' fair value appears to be largely consistent with its current price.
Exploring Other Perspectives
The most optimistic analysts focus on capital management at RenaissanceRe Holdings as the key upside catalyst. Before this Q3 setback, the bullish camp was assuming revenue of about US$8.5b and earnings near US$1.8b by 2029, helped by ongoing buybacks. You can see how far views differ and decide whether this quarter shifts your own narrative.
Explore 2 other RenaissanceRe Holdings fair value estimates, including one that suggests as much as 210% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RenaissanceRe Holdings research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for RenaissanceRe Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RenaissanceRe Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond RenaissanceRe Holdings?
If the latest results at RenaissanceRe Holdings have you rethinking concentration risk, it can help to widen your field of vision and compare it with other businesses screened on consistent, rules based criteria. The Simply Wall St screener lets you filter for different qualities in a clear way so you can line up alternatives and see where RenaissanceRe Holdings really fits in your portfolio.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with stronger cushions against shocks.
- If you are hunting for mispriced opportunities, broaden your watchlist with a 36 high quality undervalued stocks that may highlight candidates trading below what their fundamentals suggest.
- Income focused readers who want steadier cash flows from their holdings can scan a curated set of 5 dividend fortresses that meet a minimum yield threshold.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com