
Atlas Energy Solutions (NYSE:AESI) surprises with Q3 2026 sales
Proppant sand producer Atlas Energy Solutions (NYSE:AESI) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 3.1% year on year to $267.8 million. Its GAAP loss of $0.36 per share was 40.9% below analysts’ consensus estimates.
For more on Atlas Energy Solutions, read the full research report for free.
Atlas Energy Solutions (AESI) Q3 2026 highlights:
- Revenue $267.8 million vs S&P analysts’ consensus estimates of $265.3 million (3.1% year-on-year growth, 0.9% beat)
- EPS (GAAP) -$0.36 vs analysts’ consensus estimates of -$0.26 (40.9% miss)
- Adjusted EBITDA $30.32 million vs analysts’ consensus estimates of $34.83 million (11.3% margin, 13% miss)
- EBITDA guidance $45 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $50.08 million
- Operating margin -14.9%, down from -7.1% in the same quarter last year
- Free cash flow $25.34 million, up from -$1.36 million in the same quarter last year
- Market capitalization $1.15 billion
Revenue growth
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can perform well for a year or so, but a top-tier one should exhibit resilience through cycles. Over the last five years, Atlas Energy Solutions grew its revenue at a strong 49.1% compounded annual growth rate. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
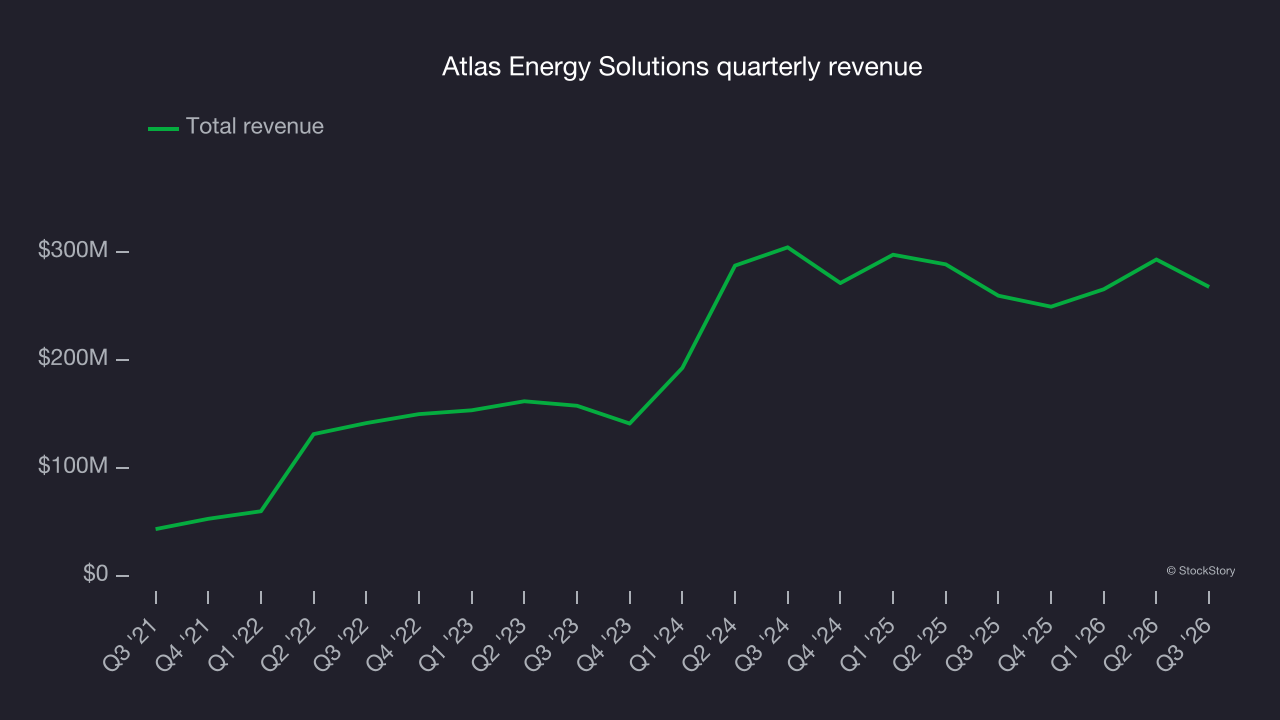
This quarter, Atlas Energy Solutions reported modest year-on-year revenue growth of 3.1% but beat Wall Street’s consensus estimates by 0.9%.
Adjusted EBITDA margin
Adjusted EBITDA margin measures the operating profitability of an energy producer by removing accounting effects related to depletion and capitalized drilling costs. It reveals how much cash the asset base generates before capital structure and reinvestment requirements shape reported earnings.
Atlas Energy Solutions was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 29.9% was weak for an upstream and integrated energy business.
Atlas Energy Solutions’s EBITDA margin decreased by 40.8 percentage points over the last year. Its performance was poor, indicating that costs were rising and it couldn’t pass them on to its customers.
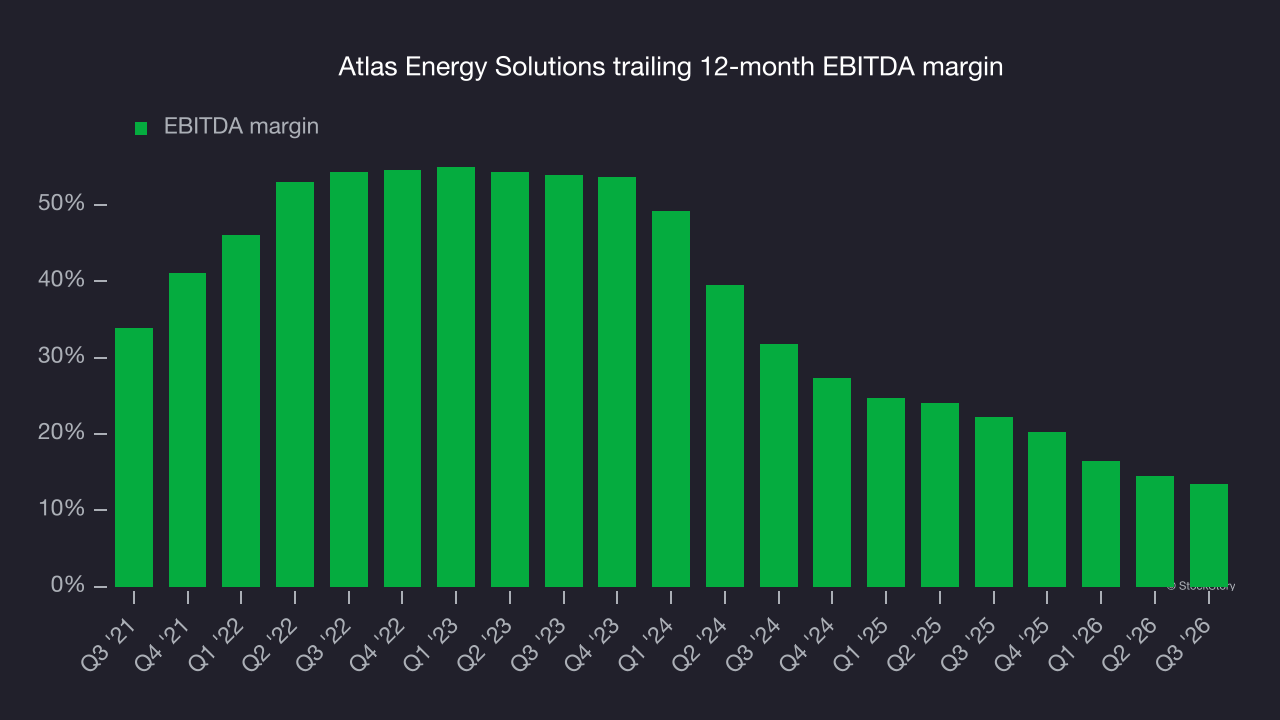
In Q3, Atlas Energy Solutions generated an EBITDA margin of 11.3%, down 4.2 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Adjusted EBITDA fell short of Wall Street’s consensus estimates.
Free cash flow
As mentioned above, adjusted EBITDA ignores capital structure and drilling expenditure decisions. These are two major aspects of an energy producer, so investors need to account for both to get a comprehensive picture of business quality. In other words, adjusted EBITDA margins could be solid but free cash flow weak because asset decline rates are high and drilling is expensive. Free cash flow tells you not only about the economics of past production but also how much it costs to stay in business through further drilling or extraction.
While Atlas Energy Solutions posted positive free cash flow this quarter, the broader picture has been less favorable. Atlas Energy Solutions’s heavy reinvestment needs have drained its resources over the last five years, straining its finances and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 5.8%, meaning it used $5.81 of cash for every $100 in revenue.
The level of free cash flow is important, but its durability across cycles is just as critical. Consistent margins are far more valuable than volatile swings driven by commodity prices.
Atlas Energy Solutions’s ratio of quarterly free cash flow volatility to volatility in West Texas Intermediate, or WTI, crude prices over the past five years was 26.4 (lower is better), indicating that its cash generation is far more sensitive to commodity-price swings than most peers. This elevated volatility limits its access to capital in downturns and makes it unlikely to act as a consolidator when weaker competitors come under pressure.
Why assess stability against commodity prices using free cash flow rather than compare revenue or EBITDA with WTI prices for Atlas Energy Solutions? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
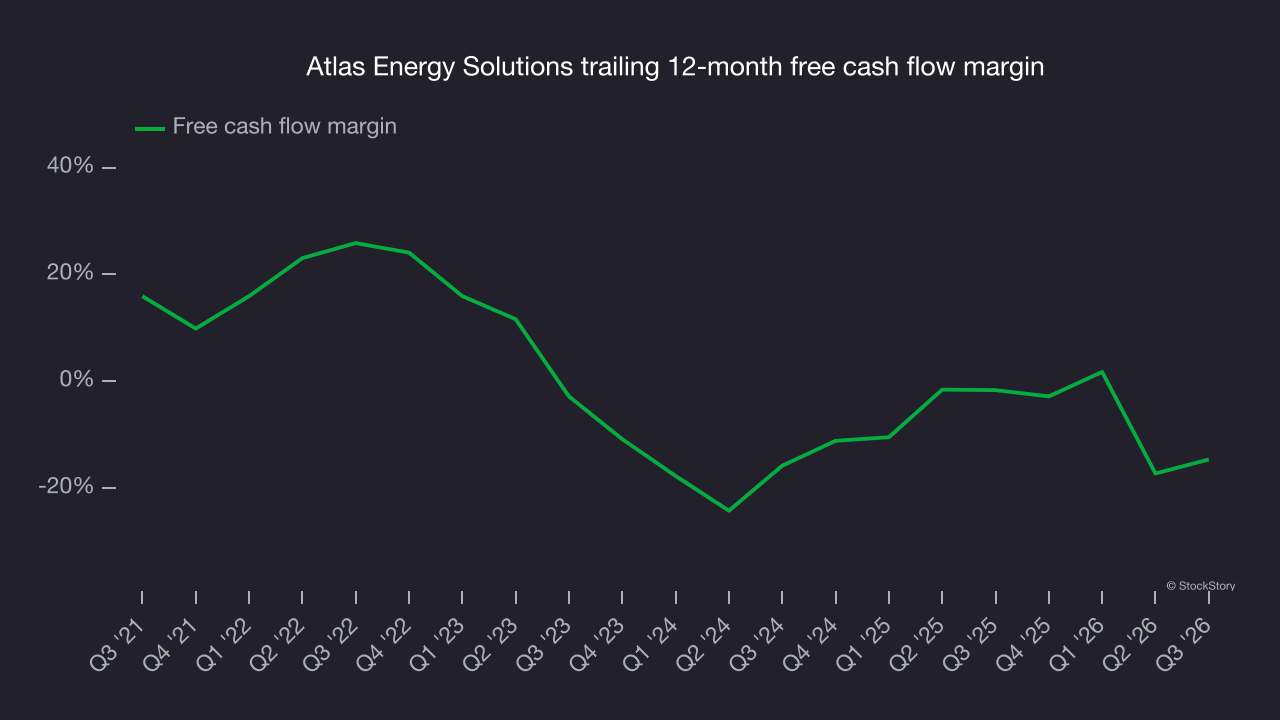
Atlas Energy Solutions’s free cash flow totaled $25.34 million in Q3, equivalent to a 9.5% margin. This was a good result, with its margin 10 percentage points higher than in the same quarter last year, but the short-term improvement should be viewed cautiously because investment needs can be seasonal, causing temporary swings. Long-term trends are more important.
Key takeaways from Atlas Energy Solutions’s Q3 results
Atlas Energy Solutions’s narrow revenue beat was a positive, but EBITDA and EPS both missed Wall Street’s consensus estimates, making this a weaker quarter overall. Shares edged lower 1.2% to $8.13 immediately after the report.
Atlas Energy Solutions had a disappointing quarter, but does that create a buying opportunity? That decision calls for a look at its valuation, business quality and latest quarterly results. For more on those factors, read our full research report here (it’s free).