
ExlService Holdings (EXLS) Faces A 125% Above Fair Value View As OpenAI Win Lifts Momentum
Why the latest EXL news matters for shareholders
ExlService Holdings (EXLS) has just been named an OpenAI Select Partner while also reporting higher earnings per share and raising full year 2026 revenue guidance. This gives investors fresh information to reassess the stock.
Across recent sessions, ExlService Holdings has ridden a strong 30-day share price return of 15.89% and a 90-day move of 20.47%, while the 1-year total shareholder return of 5.80% and 3-year total shareholder return of 55.87% point to momentum that has built over a multi year period around its AI driven execution and fresh OpenAI partnership headlines.
Compare how other AI-focused companies stack up against ExlService Holdings by reviewing our hand picked list of 41 profitable AI stocks that aren't just burning cash with real earnings behind their technology stories.
After a 20% move over three months and fresh OpenAI headlines, ExlService Holdings now forces a timing question. Is this the moment to step in, or does patience for a cheaper entry make more sense as the valuation picture comes into focus?
Most Popular Narrative: 125% Overvalued
Based on the most followed narrative, ExlService Holdings screens as significantly overpriced, with a fair value of $18.40 against a last close of $41.43. That gap frames the OpenAI Select Partner news as a sentiment boost layered on top of a valuation that already assumes a lot.
Offshore analytics and managed-operations provider that runs mission-critical claims, underwriting, payment-integrity and finance workflows for large insurers, healthcare payers and banks, and is repositioning that base into data and AI-led delivery. Roughly 53% of revenue is recurring, embedded operations protected by 12 to 30 months of transition friction, which is enough to make permanent capital loss unlikely at a low entry price. It is not enough to underwrite compounding: five years of mix shift into AI-led work has produced no gross margin expansion, contracts are terminable without cause, and the AI work is re-won through pilots rather than inherited. The thesis is therefore a price thesis, not a quality thesis
See why 4 investors see ExlService Holdings as 125% overvalued.
Result: Fair Value of $18.40 (OVERVALUED)
Still, two pressure points could change the story for ExlService Holdings: contracts that can be ended without cause, and a cost base heavily tied to wages and currency.
Find out about the key risks to this ExlService Holdings narrative.
Another View: ExlService Holdings Through a Cash Flow Lens
The narrative-based fair value of $18.40 paints ExlService Holdings as heavily overpriced. A different tool, the SWS DCF model, points the other way. It puts future cash flow value at $96.85 per share, which is well above the current $41.43 price. Which story feels more realistic to you?
For a closer look at how that cash flow figure is built, walk through the full calculation with the Look into how the SWS DCF model arrives at its fair value.
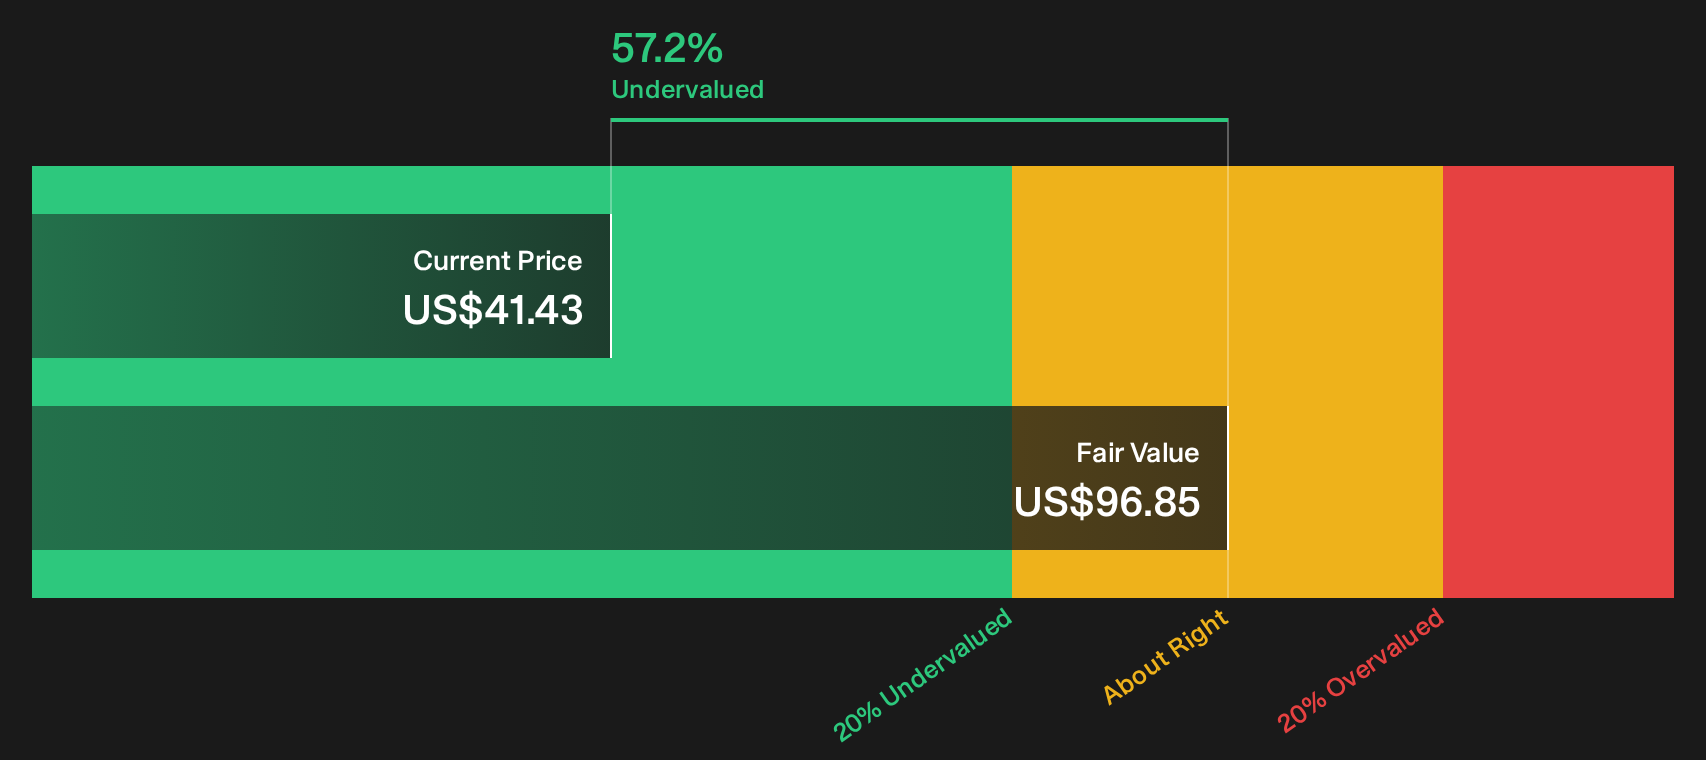
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ExlService Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear message? If ExlService Holdings has you on the fence, stress test the numbers yourself and weigh up the 3 key rewards.
Looking for more investment ideas beyond ExlService Holdings?
If ExlService Holdings leaves you undecided, broaden your watchlist with other opportunities that match your risk tolerance, income needs, and balance sheet preferences.
- Target resilient income by reviewing companies in the 5 dividend fortresses that may help anchor your portfolio with cash payouts.
- Hunt for mispriced opportunities through the 36 high quality undervalued stocks that spotlight businesses trading below their assessed worth.
- Prioritise stability first and stress test your downside with the 29 resilient stocks with low risk scores focused on sturdier balance sheets and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com