
Is EchoStar (ECHO) Fully Priced After JPMorgan's Upgrade?
EchoStar has been on a striking multi year run, and with the share price recently closing at US$96.94, the key question now is how that market value lines up with the sales the business is generating. For anyone looking at the stock today, the issue is less about the headlines and more about whether the current valuation is grounded in its revenue base.
- Over the past 3 years the stock has delivered a very large gain of about 8x, which puts a lot of pressure on the relationship between EchoStar's market value and its underlying sales.
- Recent attention on the company has centered on spectrum related assets, balance sheet changes and its investment in SpaceX, which can shape how investors think about future revenue potential and the timing of cash inflows attached to those assets.
- Your read on EchoStar is one view; the desks covering it have another. See what analysts think EchoStar's shares could be worth.
The issue now is whether EchoStar's current share price is properly supported by its sales when measured against the Fair Ratio benchmark.
If you want more ideas built around this kind of valuation question, a focused stock screen is a useful next step. You can start with 36 high quality undervalued stocks.
Does EchoStar Look Pricey on Sales?
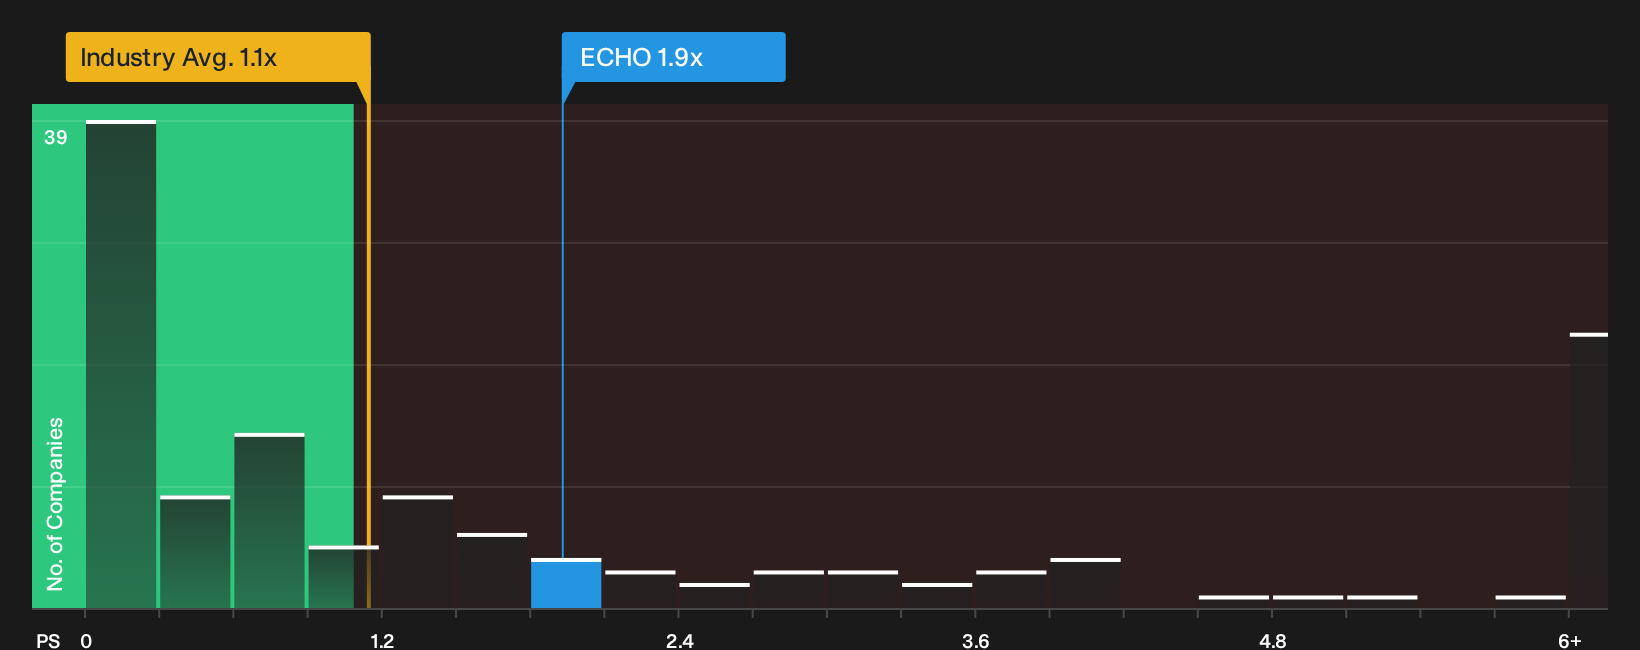
P/S is a useful lens for EchoStar because the focus today is squarely on what investors are willing to pay for each dollar of revenue rather than current earnings. The stock trades on a P/S of about 1.9x, which is higher than both the Media sector average of roughly 1.1x and the peer group at about 0.9x. That premium suggests buyers are assigning extra value to EchoStar’s specific mix of satellite operations, spectrum exposure and related assets compared with a typical media peer.
The Fair Ratio model, which looks at what a tailored P/S might be given EchoStar’s size, margins, sector and risk profile, points to a lower multiple than where the shares trade today. Despite the recent JPMorgan upgrade and pre market strength lifting sentiment, the current P/S still screens as overvalued against that Fair Ratio benchmark. That leaves the onus on you to judge whether the spectrum assets, balance sheet shifts and the SpaceX stake justify paying this richer sales multiple. Explore the numbers behind EchoStar's P/S valuation.
The EchoStar Narrative: What Would Justify Today's Price?
EchoStar Narratives pick up where the P/S puzzle leaves off by explaining which paths for future growth, profitability and earnings would need to occur for the current share price to appear materially higher or lower over time on Simply Wall St's Community page. Rather than relying on a single number from a ratio or model, these short scenarios clarify which version of EchoStar is being implied so you can track in real time whether that story is actually unfolding.
EchoStar attracts investors who either see a discounted asset story tied to cash, spectrum and SpaceX, or worry that market enthusiasm already runs ahead of fundamentals.
Bull case: 26% undervalued
"EchoStar Capital now controls a large cash position alongside an existing SpaceX equity stake, and management has outlined a capital framework that prioritizes reinvestment into existing operations, targeted new investments and potential shareholder returns..."
Discover why this Narrative puts EchoStar at 26% undervalued.
Bear case: 121% overvalued
"Let’s be real: if you just looked at EchoStar’s legacy financials, you’d run the other way..."
Explore why this Narrative puts EchoStar at 121% overvalued.
Before leaving EchoStar, one more check belongs beside the price tags
Headline ratios only tell part of EchoStar’s story, because separate forensic checks have flagged potential concern points that deserve a look from any shareholder before drawing firm conclusions. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com