
Is Crescent Energy (CRGY) Undervalued As Earnings Near And Revenue Growth Looms?
Crescent Energy earnings in focus
Crescent Energy (CRGY) is back on investors’ radar ahead of its earnings report this Monday after the market close, with analysts projecting a 50.8% year on year jump in quarterly revenue.
The recent move in Crescent Energy’s share price to around $14.20, alongside a 90 day share price return of 25.89% and a year to date share price return of 66.86%, points to building momentum. The 1 year total shareholder return of 73.46% contrasts with a more moderate 3 year total shareholder return of 35.03%.
Scan for more potential movers in energy by lining up Crescent Energy against 36 high quality undervalued stocks with similar momentum and fundamentals.
Crescent Energy’s sharp run into earnings could either echo real shifts in drilling economics and cash generation, or mainly reflect mood around analyst expectations. The valuation work now needs to separate story from substance.
Most Popular Narrative: 21% Undervalued
The dominant Crescent Energy valuation story pegs fair value around $18.06, which sits well above the last close at $14.20 and frames the current run as investors testing how much of that gap is justified by execution on acquisitions and cash flow.
Crescent Energy’s programme of acquiring and integrating large positions in proven U.S. basins, illustrated by the approximately US$3.85b Devon Eagle Ford deal that adds about 68,000 Boe/d of production and more than 600 Tier 1 locations at roughly 3x EBITDA, is expanding the production base and reserve life in ways that can support higher revenue and earnings.
See why 18 investors see Crescent Energy as 21% undervalued.
Result: Fair Value of $18.06 (UNDERVALUED)
Still, Crescent Energy’s reliance on large acquisitions and equity raises, combined with a reported P/E far above industry averages, leaves little room for integration missteps.
Find out about the key risks to this Crescent Energy narrative.
Another View on Crescent Energy’s valuation
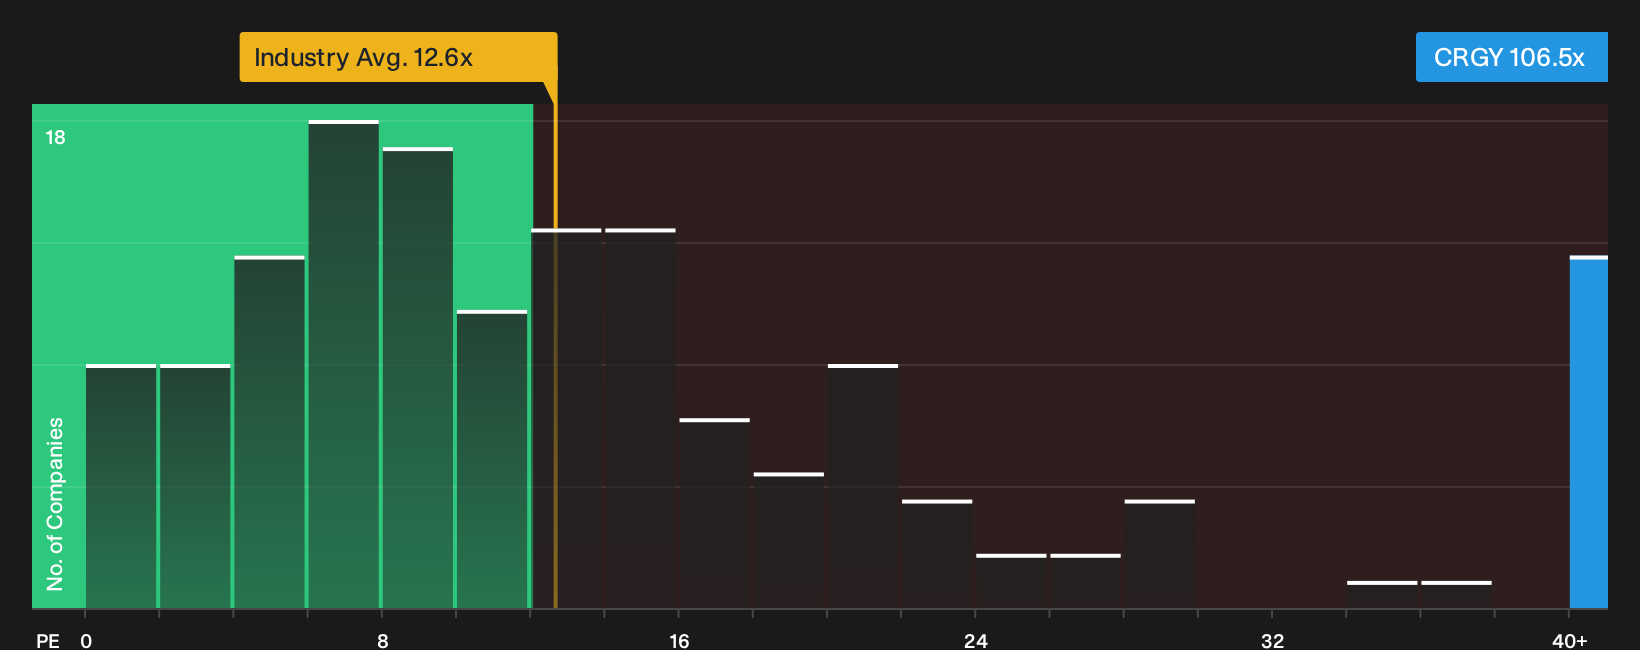
That $18.06 fair value narrative leans heavily on future earnings power, yet today’s multiples send a very different message. Crescent Energy trades on a P/E of about 106.5x compared with 12.6x for the US Oil and Gas industry and 10.4x for peers, while the fair ratio sits closer to 27x. That gap suggests investors are paying a steep premium and taking on valuation risk if execution or sentiment softens. The question is which signal carries more weight right now: the optimistic cash flow story or the rich earnings multiple?
For a closer look at how the earnings multiple stacks up against this fair ratio and the wider sector, and what that could mean if sentiment normalises, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Crescent Energy feels familiar, that is the point; you need to pressure test the numbers yourself. To see how the positives and concerns stack up side by side, start with 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Crescent Energy?
Once you have formed a view on Crescent Energy, do not stop there. Broader idea generation can help you compare risk, income, and value across the market.
- Target dependable cash flows by reviewing companies with strong payouts through the 5 dividend fortresses.
- Balance opportunity and resilience by scanning for companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential future leaders hiding in plain sight by checking the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com