
Crane (CR) Dropped, So What Is Behind The Latest Attention?
Crane (CR) has drawn fresh attention after reporting third quarter 2026 results that topped expectations and raising its full year earnings guidance, alongside affirming its regular quarterly dividend.
Crane shares closed at $198.02, with the price slipping 3.79% over the last day but still showing a 5.59% share price gain year to date. A 3.32% total shareholder return over the past year contrasts with a very large 5-year total shareholder return near 3x, which reflects earlier, stronger momentum before the recent earnings and dividend updates.
Scan beyond Crane's latest beat and raised outlook to see how other industrials with strong earnings stories stack up in our hand picked 36 high quality undervalued stocks.
Crane just paired a guidance lift with a one day pullback, which raises a simple tension. Are investors reacting to noise in sentiment, or to what this industrial is actually worth on the numbers today?
Most Popular Narrative: 16.5% Undervalued
Crane closed at $198.02, while the most followed narrative pegs fair value at $237.20 using an 8.6% discount rate. This frames the latest pullback as a valuation gap rather than a verdict on the business.
Crane’s recent acquisition of PSI, which includes Druck, Panametrics and Reuter-Stokes, continues to expand the company’s presence in higher margin sensing and fluid control applications. 2026 EPS accretion is now guided at about US$0.20 compared with the original US$0.08 expectation, supporting further earnings and margin growth.
See why 5 investors see Crane as 17% undervalued.
Result: Fair Value of $237.20 (UNDERVALUED)
Still, the Crane narrative can crack if premium P/E expectations collide with weaker margins or if Process Flow Technologies faces prolonged chemicals and project softness.
Find out about the key risks to this Crane narrative.
Another View On Crane’s Valuation
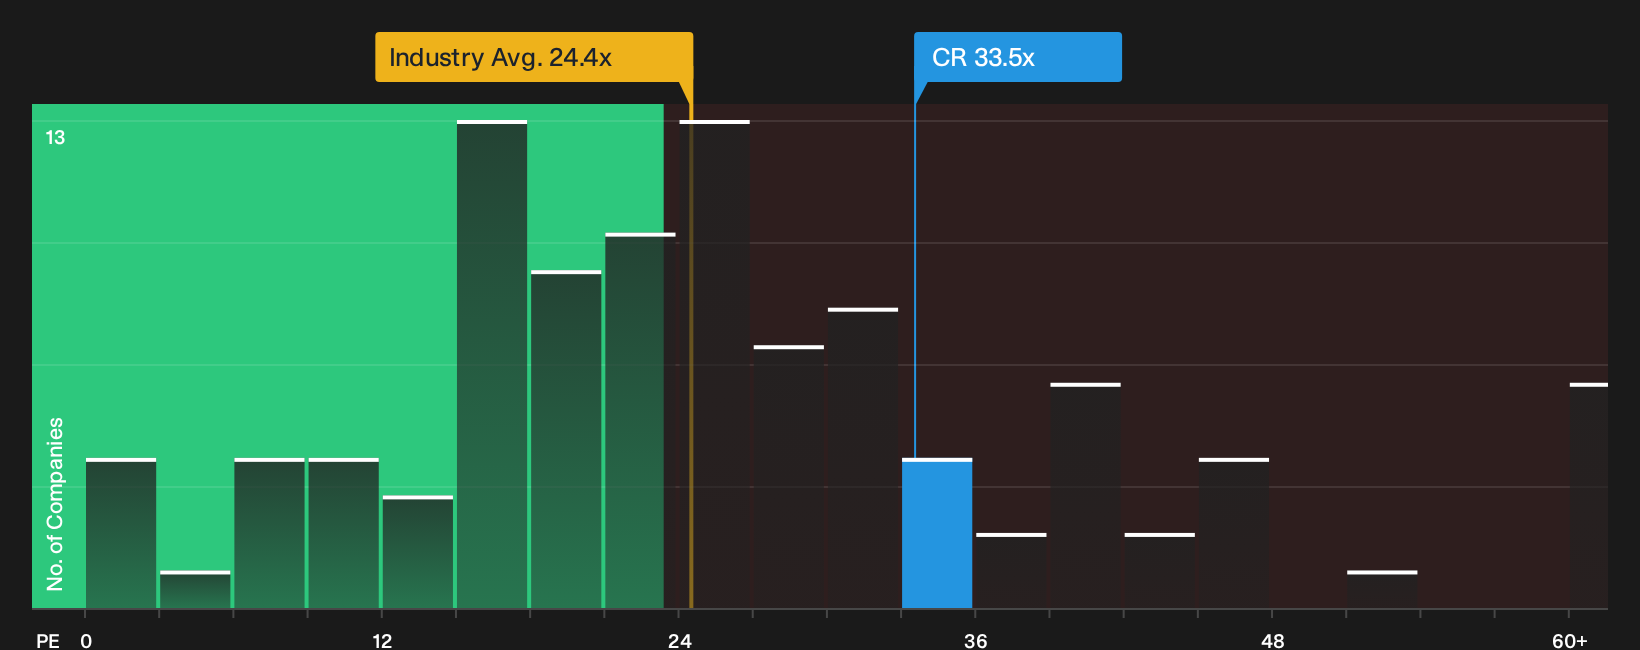
That 16.5% gap to fair value uses a narrative driven model. The P/E tells a tougher story. Crane trades on 33.5x earnings versus 28.7x for peers and 24.4x for the US Machinery group, while the fair ratio is also 24.4x. That points to richer pricing. Is the quality premium worth paying?
To see how those earnings multiples line up against the underlying numbers, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sharp moves in sentiment around Crane only matter if they line up with the underlying data. Review the full picture and decide quickly where you stand. To get a balanced feel for both the concerns and the potential upside, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Crane?
If you stop with Crane, you only see one angle. Broaden your watchlist now and you give yourself more ways for the numbers to work in your favor.
- Target resilience first by scanning a list of solid balance sheet and fundamentals (24 results) that can handle shocks better than highly leveraged peers.
- Hunt for mispriced quality using a focused 36 high quality undervalued stocks that filters for fundamentals, not just headlines.
- Spot under-the-radar potential by running through a 19 high quality undiscovered gems that most investors are not watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com