
Learn Why The Bull Case For Dime Community Bancshares (DCOM) Could Change Following Stronger Quarterly Earnings
- Dime Commercial Bancshares reported third quarter 2026 results with net interest income of US$121.22 million and net income of US$41.56 million, along with a quarterly cash dividend of US$0.34375 per Series A preferred share declared for payment on November 16, 2026.
- The combination of higher earnings per share from continuing operations and lower net loan charge offs points to improved credit performance together with stronger core profitability for Dime Commercial Bancshares.
- We will now look at how Dime Commercial Bancshares' higher third quarter net interest income could influence the broader investment narrative.
Compare Dime Commercial Bancshares' latest credit and income trends with a hand picked 29 resilient stocks with low risk scores that also prioritise balance sheet strength and consistency in their financial profiles.
Dime Commercial Bancshares Investment Narrative Recap
To own Dime Commercial Bancshares, you need to believe the shift toward a broader commercial bank can convert its low cost funding and loan repricing pipeline into steadier earnings, without credit issues or expense creep getting in the way. The latest quarter supports that thesis in the near term, with higher net interest income and stronger earnings from continuing operations.
The near term swing factor still sits in credit costs around commercial real estate and multifamily, where elevated provisions had been a concern. Lower net loan charge offs this quarter point in the right direction, although that trend needs to hold as Dime Commercial Bancshares keeps funding new lending teams and specialized verticals that lift its expense base.
The third quarter earnings release is the announcement that really matters here. Dime Commercial Bancshares reported net interest income of US$121.22 million and net income of US$41.56 million for the period, along with basic and diluted earnings per share from continuing operations of US$0.90. For the first nine months of 2026, both net interest income and profit were higher than the comparable 2025 period.
Those figures sit alongside net loan charge offs of US$9.75 million for the quarter compared with US$12.59 million a year earlier, which ties directly into the key risk around credit quality and reserves. When you line that up with the preferred dividend declaration, the picture is of a bank trying to keep capital returns, loan repricing benefits, and credit costs in balance as it pushes deeper into business lending.
How Dime Commercial Bancshares' Forecasts Tie Into The Story
Dime Commercial Bancshares' analyst narrative links the recent quarter to a longer earnings path that stretches out to 2029. Forecasts assume revenue grows at 14.7% per year over the next few years while profit margins move higher from 27.2% today to 33.3% in three years, and together these shape expectations for future profitability and shareholder returns.
On the earnings line, analysts see profit rising from US$119.3 million today to US$220.6 million by 2029, supported by the commercial banking mix shift, loan repricing and the build out of specialty lending teams. That move implies an earnings increase of about US$101 million over the period, so you are being asked to underwrite not just balance sheet progress but a much larger income statement by the end of the decade.
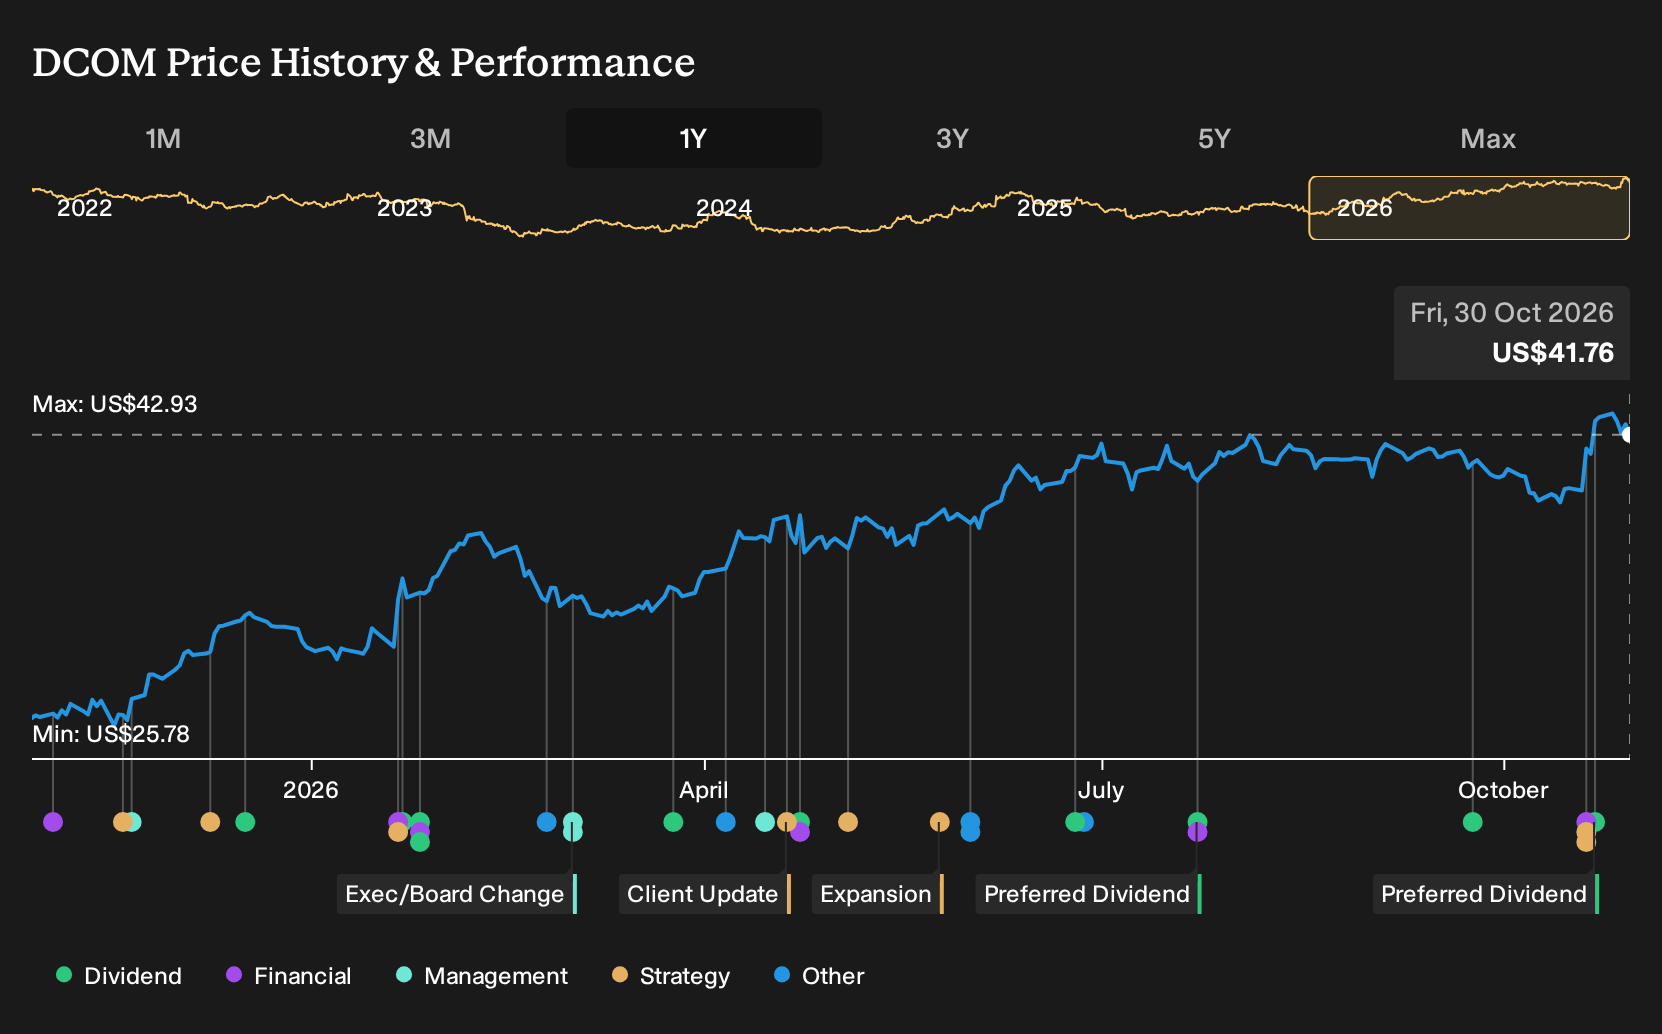
The same 2029 framework underpins the valuation work. Analyst models point to forecast revenue of US$662.6 million and profit of US$220.6 million in that year, with Dime Commercial Bancshares trading at a P/E of 11.6x on those future earnings compared with 14.6x today. Those inputs sit behind a consensus price target of US$46.00, described as 14.1% above the current US$39.51 share price, with a discount rate assumption of about 7.2% to 7.24% used to bring those future estimates back to today.
Assumptions in the background are just as important as the headline numbers. Analyst models build in share count growth of 0.6% a year over the next three years, which slightly dilutes per share outcomes unless earnings grow faster than the share base. The profit margin uplift from 27.2% to 33.3% also does a lot of heavy lifting, so any pressure from higher funding costs, competition for deposits or a slower ramp in fee income could leave actual results below the path implied by these projections.
The trade off that investors need to weigh is clear. Funding new commercial and specialty teams lifts core cash operating expenses toward about US$260 million for 2026, while credit reserves have moved higher with an allowance for credit losses at 98 basis points of loans after a US$14 million provision tied to investor commercial real estate and multifamily exposures. If those cost and credit trends settle at a higher level than analysts expect, it could put earnings and the implied 2029 margin trajectory under pressure.
On the flip side, if Dime Commercial Bancshares keeps adding low cost commercial and municipal deposits, continues repricing around US$2.5b of loans that are coming off average rates of 4.25%, and maintains measured exposure to higher risk commercial real estate, then the gap between current profitability and the analyst forecast could narrow over time. For readers, the key task is to decide whether the revenue growth, margin lift and share issuance assumptions together feel realistic given the bank's business mix and risk appetite.
Dime Commercial Bancshares' narrative projects US$662.6 million revenue and US$220.6 million earnings by 2029. This assumes 14.7% yearly revenue growth and an earnings increase of about US$101 million from US$119.3 million today.
Discover how Dime Commercial Bancshares' fair value indicates a 10% potential upside to its current price before other investors act on this information.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from US$46 to about US$88.66, so retail views on Dime Commercial Bancshares stretch from modest upside to almost a double. Set that against rising expenses, credit reserves tied to commercial real estate, and fresh loan repricing catalysts, and you can see how sharply opinions can differ. It is worth exploring several community viewpoints before forming your own stance.
Explore 2 other Dime Commercial Bancshares fair value estimates, including one that suggests it could be worth just $46.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dime Commercial Bancshares research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dime Commercial Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dime Commercial Bancshares' overall financial health at a glance.
Looking for more Dime Commercial Bancshares investment ideas?
If you want to stress test your view on Dime Commercial Bancshares against other opportunities, the Simply Wall St Screener lets you quickly scan for different types of businesses that fit your risk and return preferences.
- For investors who care most about resilience, start with companies that have historically scored well on stability by reviewing a 29 resilient stocks with low risk scores that keep volatility and financial red flags in check.
- If income is the priority, focus on businesses with meaningful yields and consistent shareholder payouts by checking out a curated set of 5 dividend fortresses that may complement a core holding like Dime Commercial Bancshares.
- When the goal is to find potential mispricing, compare Dime Commercial Bancshares to a 36 high quality undervalued stocks that combine solid fundamentals with what analysts view as attractive entry prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com