
How Investors Are Reacting To Vertex Pharmaceuticals (VRTX) Phase 3 Kidney Trial Results
- Vertex Pharmaceuticals reported Phase 3 RAINIER data for povetacicept in IgA nephropathy, with NEJM publication and ASN Kidney Week presentation detailing proteinuria reductions and trial design.
- The focus on an autoinjector device and every 4 week dosing, supported by patient preference data, highlights administration features that could be important for future uptake in renal disease.
- Attention now shifts to how Vertex Pharmaceuticals' broader investment narrative could be influenced by povetacicept's Phase 3 IgAN results and the NEJM publication.
Vertex Pharmaceuticals Investment Narrative Recap
To be comfortable owning Vertex Pharmaceuticals, you need to believe the cystic fibrosis engine can stay resilient while newer areas like renal disease, endocrinology and pain steadily take on more weight. The big short term swing factor remains execution across this broader portfolio, including launches such as CASGEVY and JOURNAVX, and uptake outside the US.
The biggest near term risk still sits with concentrated exposure to high margin CF therapies and any pricing or volume pressure there, alongside integration and financing risk from the Crinetics deal. The RAINIER IgA nephropathy data and NEJM publication support diversification, but do not remove those core business risks.
The RAINIER Phase 3 readout for povetacicept is the clearest link between this week’s news and the existing Vertex Pharmaceuticals catalyst list. Management had already framed renal disease as a future pillar, with late stage assets in both IgA nephropathy and APOL1 mediated kidney disease and growing regulatory comfort around proteinuria and eGFR endpoints.
RAINIER meeting its proteinuria endpoint, plus the focus on an autoinjector with every 4 week dosing and a dedicated PAVANT experience trial, feeds directly into that renal thesis. For investors watching catalysts, the key questions now are regulatory interactions, real world adoption on top of SGLT2 use and how quickly renal revenue can help offset any CF or Crinetics related pressure.
What The Current Vertex Pharmaceuticals Consensus Is Pricing In
Vertex Pharmaceuticals' current analyst playbook assumes revenue growth of 11.7% a year over the next three years, with profit margins moving from 35.0% today to 36.1% by 2029 as the product mix shifts toward newer renal and endocrinology drugs alongside cystic fibrosis.
On earnings, the consensus points to profit of US$4.4b today rising to US$6.3b by 2029, which is an increase of roughly US$1.9b in annual earnings, even though analyst views are spread between US$5.1b and US$7.6b at the top and bottom of the range.
For that earnings profile to line up with current targets, the stock would need to trade on a 28.3x P/E in 2029 versus about 30.3x today, a premium multiple compared with the 17.1x currently applied to the wider US biotech group. Any change in how investors view sector risk or Vertex Pharmaceuticals' kidney pipeline could matter for that gap.
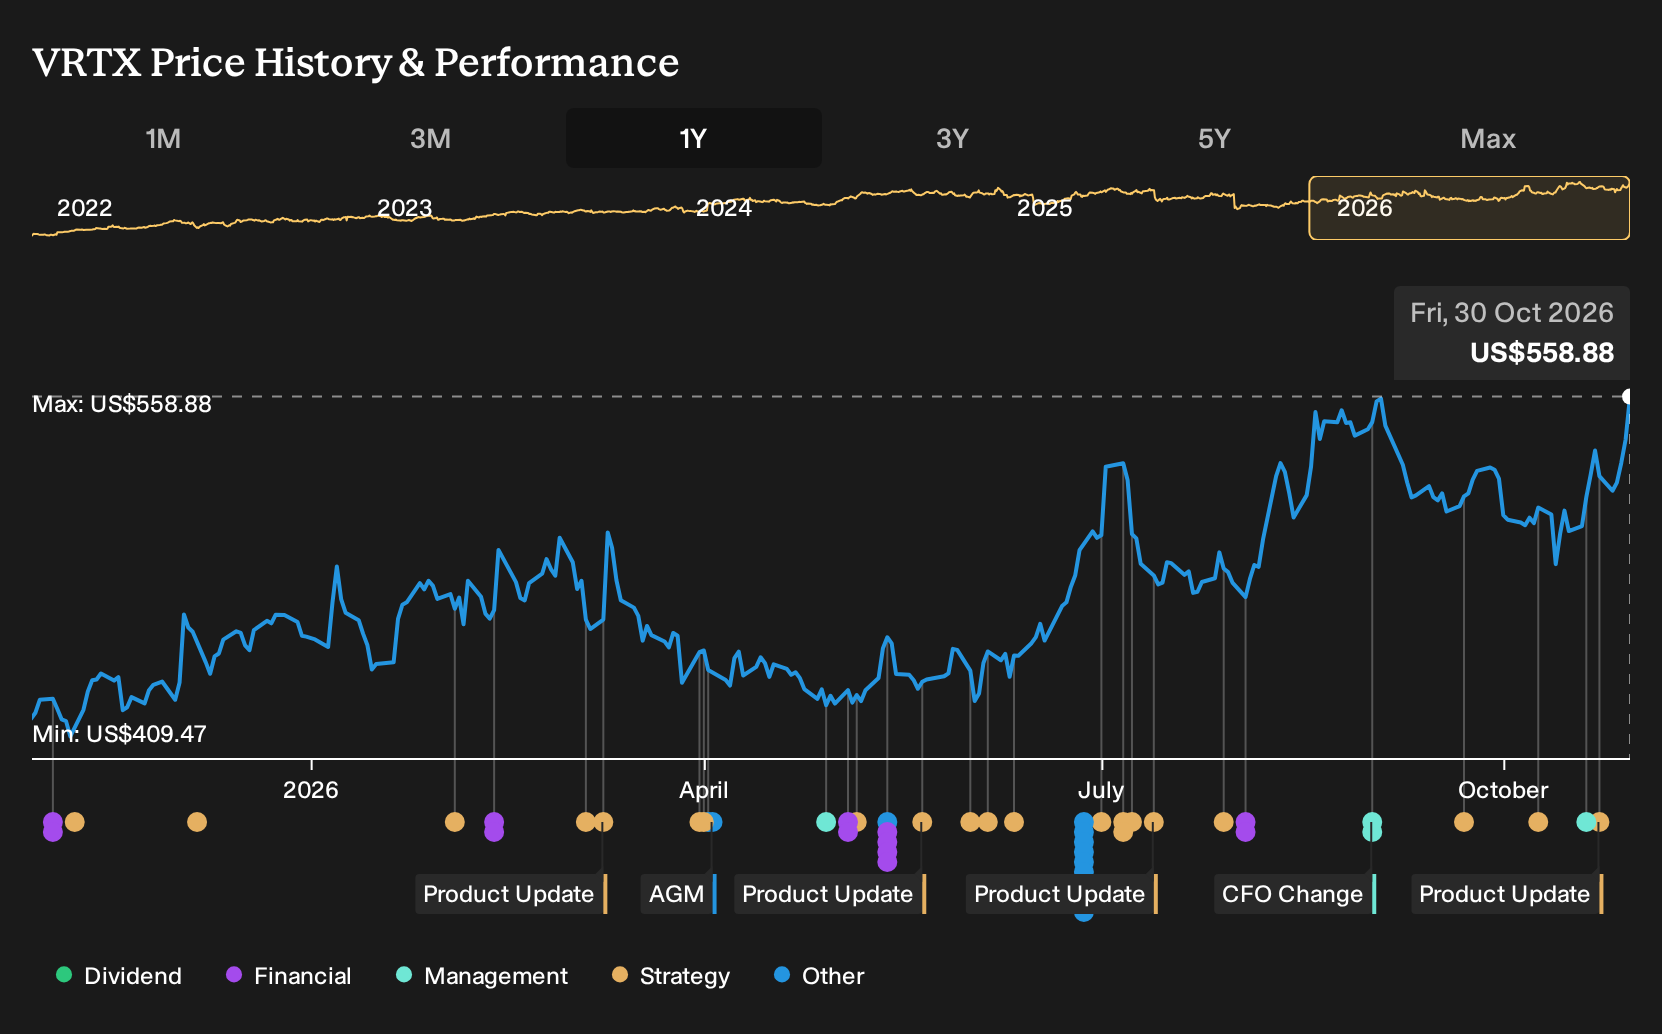
Those same forecasts imply 2029 revenue of US$17.6b and earnings of US$6.3b. Analysts then discount these figures back at roughly 7.5% to support a consensus price target around US$571 on a share price that recently traded near US$526, leaving single digit upside that suggests many on the Street already factor in meaningful contribution from renal disease, CASGEVY, JOURNAVX and the Crinetics portfolio.
Vertex Pharmaceuticals' narrative projects US$17.6b revenue and US$6.3b earnings by 2029. This assumes 11.7% yearly revenue growth and an earnings increase of about US$1.9b from US$4.4b today.
Uncover why Vertex Pharmaceuticals' fair value aligns with its current price.
Exploring Other Perspectives
One alternate angle on Vertex Pharmaceuticals is the risk that renal approvals arrive more slowly than hoped if regulators ask for longer outcome data beyond proteinuria. The most cautious analysts were only penciling in about US$16.3b of revenue and US$5.1b of earnings for 2029 before this RAINIER update, which reflects a much tougher narrative on timing and scale. That gap with consensus shows how wide opinions can be. Use this new IgAN data as a prompt to compare several viewpoints rather than lean on a single story.
Explore 4 other Vertex Pharmaceuticals fair value estimates, including one that suggests as much as 23% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vertex Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vertex Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vertex Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vertex Pharmaceuticals?
If Vertex Pharmaceuticals has sharpened your focus on quality, risk and long term pipelines, it can be useful to line that thinking up against a broader watchlist. The Simply Wall St Screener lets you scan the market through the same lens, so you can sanity check your thesis against other opportunities with clear financial profiles.
- If capital preservation is high on your list, start with resilient companies flagged in the 29 resilient stocks with low risk scores and see which ones fit your comfort level.
- For investors hunting for mispriced quality, compare Vertex Pharmaceuticals with a 36 high quality undervalued stocks that pairs strong fundamentals with what analysts see as attractive entry points.
- If balance sheet strength matters most to you, filter for businesses with low leverage and plenty of flexibility by running the list of solid balance sheet and fundamentals (24 results)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com