
Is Freeport-McMoRan (FCX) Undervalued After Strong Earnings And Higher Fourth Quarter Guidance?
Freeport-McMoRan (FCX) just paired stronger third quarter earnings with new fourth quarter guidance that points to its highest sales of 2026, driven by higher copper volumes and a sharp jump in gold output.
Despite the upbeat third quarter and strong fourth quarter outlook, Freeport-McMoRan’s share price has slipped, with a 1-day move down 5.55%, a 7-day share price return down 4.13% and a 30-day share price return down 13.28%. At the same time, the year-to-date share price return is up 20.30% and the 1-year total shareholder return is 53.11%, suggesting that recent weakness may reflect a reset in expectations rather than a break in the longer-term trend.
Capitalize on the volatility around Freeport-McMoRan by scanning a curated shortlist of copper producers and related miners in the 16 top copper producer stocks.Freeport-McMoRan just paired strong reported earnings with a sharp pullback in the share price. The key question for investors is whether that reset leaves the risk reward still tilted toward buyers, or whether the valuation is already doing its job.
Most Popular Narrative: 21% Undervalued
The most followed narrative on Freeport-McMoRan pegs fair value at $79.07, above the last close of $62.47, with that gap resting heavily on copper volume projects and cost control delivering as planned.
Freeport-McMoRan’s large above-ground copper stockpiles and progress with new leach additives and heated solutions, already producing around 200 million pounds per year with a target of 800 million pounds annually within 3 to 4 years, point to potential low incremental cost volume growth that could support higher future revenue and structurally lower unit net cash costs.
See why 113 investors see Freeport-McMoRan as 21% undervalued.
Result: Fair Value of $79.07 (UNDERVALUED)
Still, the Freeport-McMoRan narrative leans heavily on smooth Grasberg execution, as well as large brownfield projects like Bagdad staying on schedule and within budget.
Find out about the key risks to this Freeport-McMoRan narrative.
Another View: Freeport-McMoRan Through The Earnings Lens
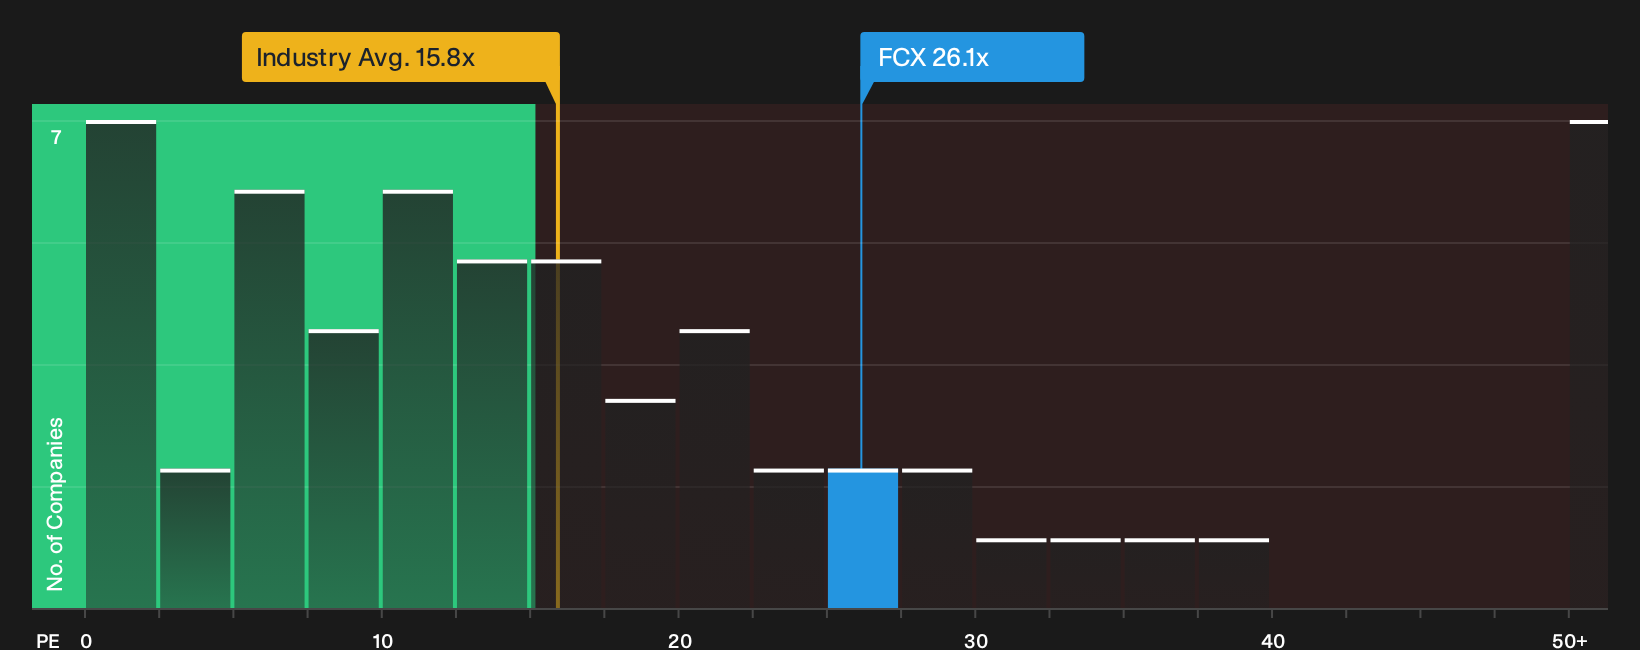
The story looks different when the P/E ratio is used instead of the fair value estimate. Freeport-McMoRan trades on about 26.1x earnings versus a fair ratio of 22.2x, the US Metals and Mining industry at 15.8x and peers at 16.6x, which points to valuation risk if sentiment cools.
That gap raises a simple question for investors: Is the premium a reasonable price for copper exposure and project execution, or is it a margin of safety given away before the next cycle turn?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Freeport-McMoRan’s valuation and project risks can be useful if you treat them as a prompt, not an answer. You may wish to act while sentiment is divided by reviewing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Freeport-McMoRan?
If you only focus on Freeport-McMoRan, you risk missing other opportunities that fit your style, your risk tolerance, and your return goals just as well.
- Target resilient income by reviewing companies built around steady cash flows and reliable payouts in the 5 dividend fortresses.
- Hunt for quality at a discount by scanning financially strong businesses trading below their estimated worth in the 36 high quality undervalued stocks.
- Zero in on sturdier balance sheets by filtering for companies with solid financial foundations using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com