
Nvidia Stock Looks Surprisingly Cheap. Why NVDA Could Rise 61%.
Nvidia (NVDA) continues to deliver solid growth even against increasingly challenging year-over-year (YoY) comparisons. While the company remains a major beneficiary of rising investments in artificial intelligence (AI) infrastructure, its current valuation appears surprisingly cheap relative to its strong earnings growth trajectory and that of its peers.
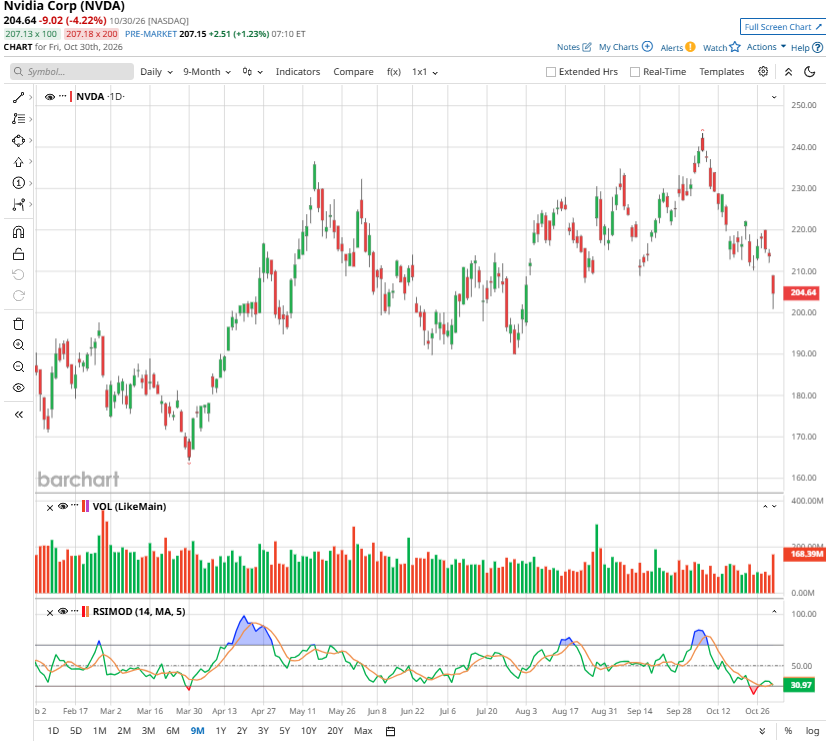
Year-to-date (YTD), NVDA stock has advanced 10%, slightly trailing the S&P 500's ($SPX) 11% return. However, demand for Nvidia's GPUs and CPUs remains supported by expanding AI workloads, hyperscaler investments, and the ongoing buildout of data center infrastructure. These structural demand drivers indicate solid growth ahead.
Moreover, Nvidia's substantial free cash flow generation enables it to reward shareholders through continued share repurchases and dividend distributions.
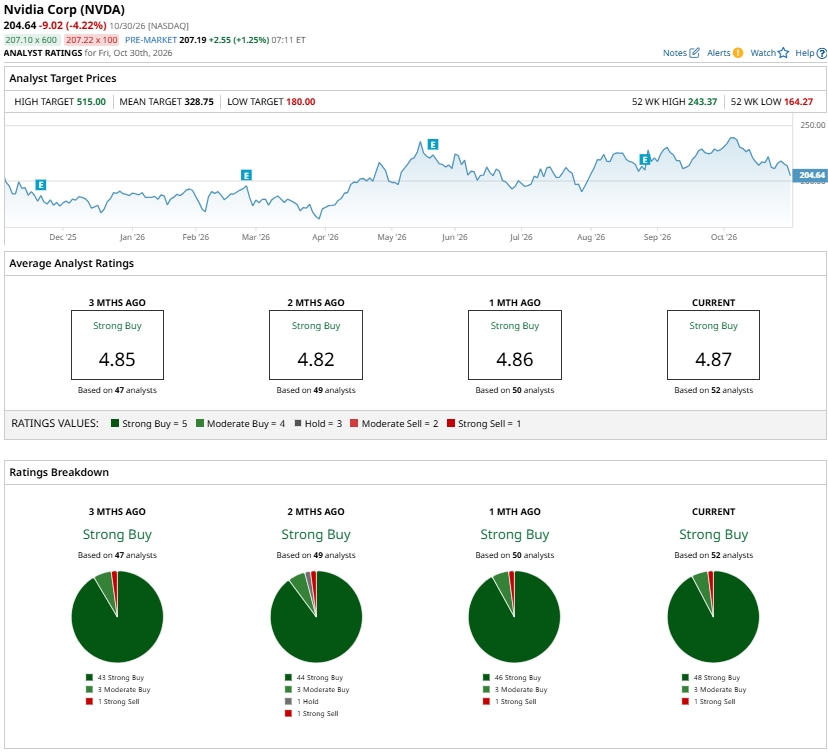
Taken together, Nvidia's durable competitive positioning in AI computing, favorable industry tailwinds, robust earnings outlook, and shareholder-friendly capital allocation strategy strengthen its long-term investment thesis. Meanwhile, analysts’ average price target of $328.75 indicates Nvidia's stock could rise about 61% in the next 12 months.
Nvidia’s Solid Growth Supports Upside in Stock
Nvidia will continue to capitalize on the accelerating buildout of AI infrastructure, as hyperscale cloud providers continue to expand investments in computing capacity. The company’s expanding addressable market, diversified customer base, and new product innovations position it to deliver solid growth and support its stock price.
In Q2, Nvidia's top line increased 106% to $96.2 billion. Revenue growth rate has been accelerating sequentially, which indicates strong demand for its advanced computing solutions. Earnings per share (EPS) also surged 128% YoY, benefitting from solid top-line growth.
Nvidia’s addressable market is also expanding, strengthening Nvidia’s growth prospects. Demand continues to originate from hyperscale cloud providers, AI research institutions, AI-native companies, enterprises, and sovereign customers. This broadening demand base will support future demand by creating additional opportunities to monetize AI adoption across industries and geographies. Moreover, it reduces the firm's reliance on individual customer categories.
Nvidia’s data center business is growing rapidly, and the growth rate is unlikely to slow down anytime soon. Revenue from this business increased 18% sequentially to $89 billion in Q2. Hyperscale revenue climbed 13% sequentially to $49 billion, supported by continued adoption of the Blackwell platform. Meanwhile, the ACIE division, which serves neocloud providers, industrial customers, and enterprises, delivered stronger growth, with revenue rising 25% sequentially and 138% YoY to $40 billion.
Nvidia’s product roadmap strengthens its growth prospects. Nvidia has begun shipping its Vera Rubin platform, which management expects will achieve the fastest product ramp in its history. Vera Rubin is expected to account for approximately 20% of data center revenue in Q3, with its contribution likely to increase as production scales.
Furthermore, Nvidia’s growth opportunity extends beyond GPUs. Networking solutions and CPUs are complementary revenue drivers. Networking revenue increased 18% sequentially, reflecting the growing importance of high-speed connectivity in increasingly complex AI data centers. At the same time, the expansion of agentic AI applications is generating additional demand for data center CPUs.
Nvidia expects total server CPU revenue of $20 billion in the current fiscal year. Given strong customer demand and an improving supply outlook, Nvidia expects CPU revenue to more than double in fiscal 2028.
Management expects third-quarter revenue of $108 billion, implying 12% sequential growth. Hyperscale demand is also expected to strengthen in the fourth quarter and remain robust into fiscal 2028 as Vera Rubin production scales.
Overall, sustained AI infrastructure investment, successive product launches, and expanding networking and CPU opportunities provide multiple growth drivers that support Nvidia stock.
NVDA Stock Is Cheap
NVDA stock is trading cheap, indicating it has room to run. The stock trades at 23 times forward earnings, which is low considering its strong earnings growth. Analysts expect Nvidia’s earnings to more than double this fiscal year. Moreover, the momentum will continue into fiscal 2027. Analysts expect its bottom line to grow 69.3% YoY in fiscal 2027.
Nvidia’s solid growth prospects and low valuation make it a compelling risk-reward play.
Strong Growth and Attractive Valuation Support 61% Upside
Nvidia’s solid revenue and earnings growth, expanding AI opportunity, and continued product innovation provide a strong foundation for further gains. Despite its robust growth outlook, NVDA trades at just 23 times forward earnings, indicating it is undervalued.
With analysts projecting substantial earnings growth ahead and the stock trading cheap, Nvidia has the potential to surge 61% and hit the average price target of $328.75 in the next 12 months.
Analysts keep a “Strong Buy” consensus rating on NVDA stock.
On the date of publication, Sneha Nahata did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.