
Is Kratos Defense & Security Solutions (KTOS) A Bargain On Its NASA Space Reactor Win?
NASA Space Reactor contract puts Kratos Defense & Security Solutions in focus
Kratos Defense & Security Solutions (KTOS) just secured a US$33.6 million subcontract tied to NASA’s Space Reactor-1 Freedom project, which is pushing the stock into the spotlight for investors tracking advanced space and defense programs.
For context, Kratos Defense & Security Solutions shares trade at US$41.09 after declining about 5.7% on the day, and the stock now shows a year to date share price loss of about 48%. However, the 3 year total shareholder return is about 134%, suggesting recent momentum has faded despite a much stronger longer run record.
Scan other defense and space contractors showing similar program exposure with our curated list of 29 resilient stocks with low risk scores for ideas beyond Kratos Defense & Security Solutions.
Kratos Defense & Security Solutions now sits between a bullish story built on NASA, hypersonics and recent contract wins, and a bearish read on a sharp share pullback. Which side does the current valuation lean toward next?
Most Popular Narrative: 56% Undervalued
Against Kratos Defense & Security Solutions' last close at $41.09, the most followed narrative points to a fair value of $94.44, so the current slide sits against a backdrop of analysts still modeling a much higher long run outcome. That gap is being framed around whether today’s contracts and capacity build out can convert into the scale needed to support those forecasts.
Kratos Defense & Security Solutions is building a larger hypersonic franchise, with hypersonic revenue around US$200m in 2025 and forecasts of roughly US$400m in 2026 and at least US$700m in 2027, supported by several hundred million dollars of recent funding, new programs such as Kraken and Nemesis, 120 solid rocket motors on order, and a multi year MACH TB budget profile of about US$7b, which could materially lift future revenue and earnings power.
See why 164 investors see Kratos Defense & Security Solutions as 56% undervalued.
Result: Fair Value of $94.44 (UNDERVALUED)
Still, the Kratos Defense & Security Solutions story can wobble if foreign exchange pressure on profitability persists or if high upfront investment keeps delaying stronger free cash flow.
Find out about the key risks to this Kratos Defense & Security Solutions narrative.
Another View on Kratos Defense & Security Solutions Valuation
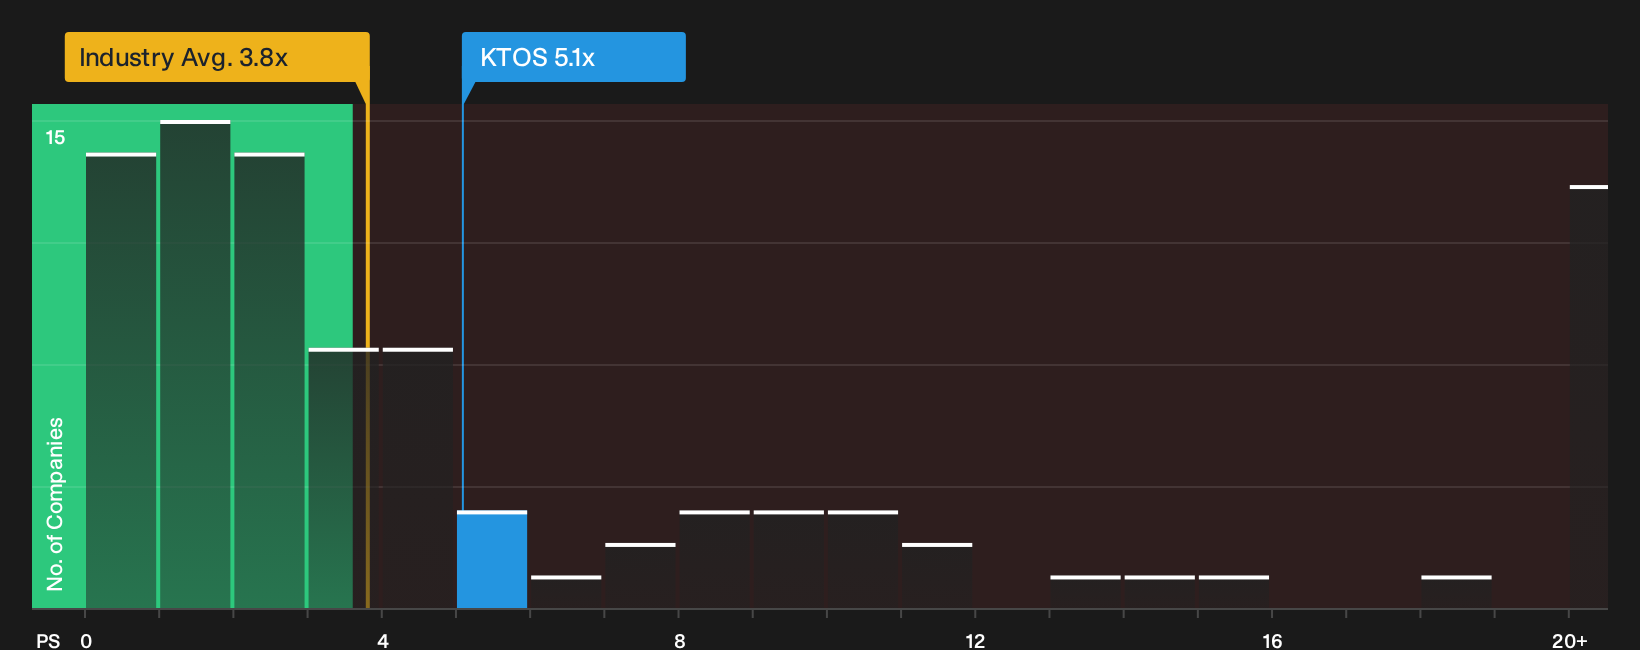
That $94.44 fair value mark leans heavily on long term forecasts. A different lens looks at the P/S ratio today. Kratos Defense & Security Solutions trades on 5.1x sales, compared with 3.8x for the US Aerospace & Defense group and a fair ratio estimate of 2.7x, which points to meaningful valuation risk if expectations cool.
To see how this pricing gap lines up with the broader numbers and assumptions, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Kratos Defense & Security Solutions story today. Act while the data is fresh and weigh both sides of the thesis with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Kratos Defense & Security Solutions?
Keep momentum on your research and put today’s Kratos Defense & Security Solutions update in context by comparing it with other focused opportunities across different styles of stocks.
- Target potential mispricings across the market by scanning a curated pool of quality opportunities through the 36 high quality undervalued stocks.
- Strengthen your income playbook and pressure test dividend reliability using the hand picked 5 dividend fortresses.
- Prioritise financial resilience by filtering for companies with balance sheets that can take a hit using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com