
Is Aon (AON) Cheap Or Expensive As Strong Q3 Earnings Lift The Stock?
Aon (AON) drew fresh attention after reporting third quarter 2026 results, with sales of US$4,101 million and net income of US$476 million, along with higher earnings per share from continuing operations year over year.
Aon’s latest update landed after a sharp rebound in the shares, with a 7 day share price return of 6.5% and a 30 day gain of 19.4% from a recent 90 day decline of 9.8% that left the year to date share price return down 6.6% and the 1 year total shareholder return down 4.7%. This hints that investors are reassessing earnings resilience rather than treating this quarter as a one off.
Scan how Aon compares to other insurance and financial services stocks showing resilient earnings trends using our hand picked 29 resilient stocks with low risk scores in the current market.
Aon’s quick rebound leaves the stock trading between a discounted intrinsic estimate and a higher analyst target range. The real issue now is where fair value falls inside that spread.
Most Popular Narrative: 16% Overvalued
Aon closed at $321.67 while the most followed narrative anchors fair value at $276.22. The current rebound sits above that implied line and focuses attention on how the USI deal and higher leverage could reshape the earnings path that underpins that estimate.
The assumed bearish price target for Aon is $276.22, which represents up to two standard deviations below the consensus price target of $358.95. This valuation is based on what can be assumed as the expectations of Aon's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
See why 0 investors see Aon as 16% overvalued.
Result: Fair Value of $276.22 (OVERVALUED)
Still, if Aon delivers smoother USI integration with tighter costs and proves out higher margin E&S and capital solutions, this bearish fair value could be challenged.
Find out about the key risks to this Aon narrative.
Another View: Cash Flows Point the Other Way
The bearish narrative pegs Aon as 16% overvalued at a fair value of $276.22, yet our DCF model points in the opposite direction. On that cash flow view, the shares at $321.67 trade about 25% below an estimated value of $429.42, which frames today’s rebound in a very different light.
This split between analyst targets and the SWS DCF model raises a simple question for investors. Do you put more weight on market multiples or on the cash that Aon is expected to generate over time, and what would make you change your mind if the story shifts from here?
Look into how the SWS DCF model arrives at its fair value.
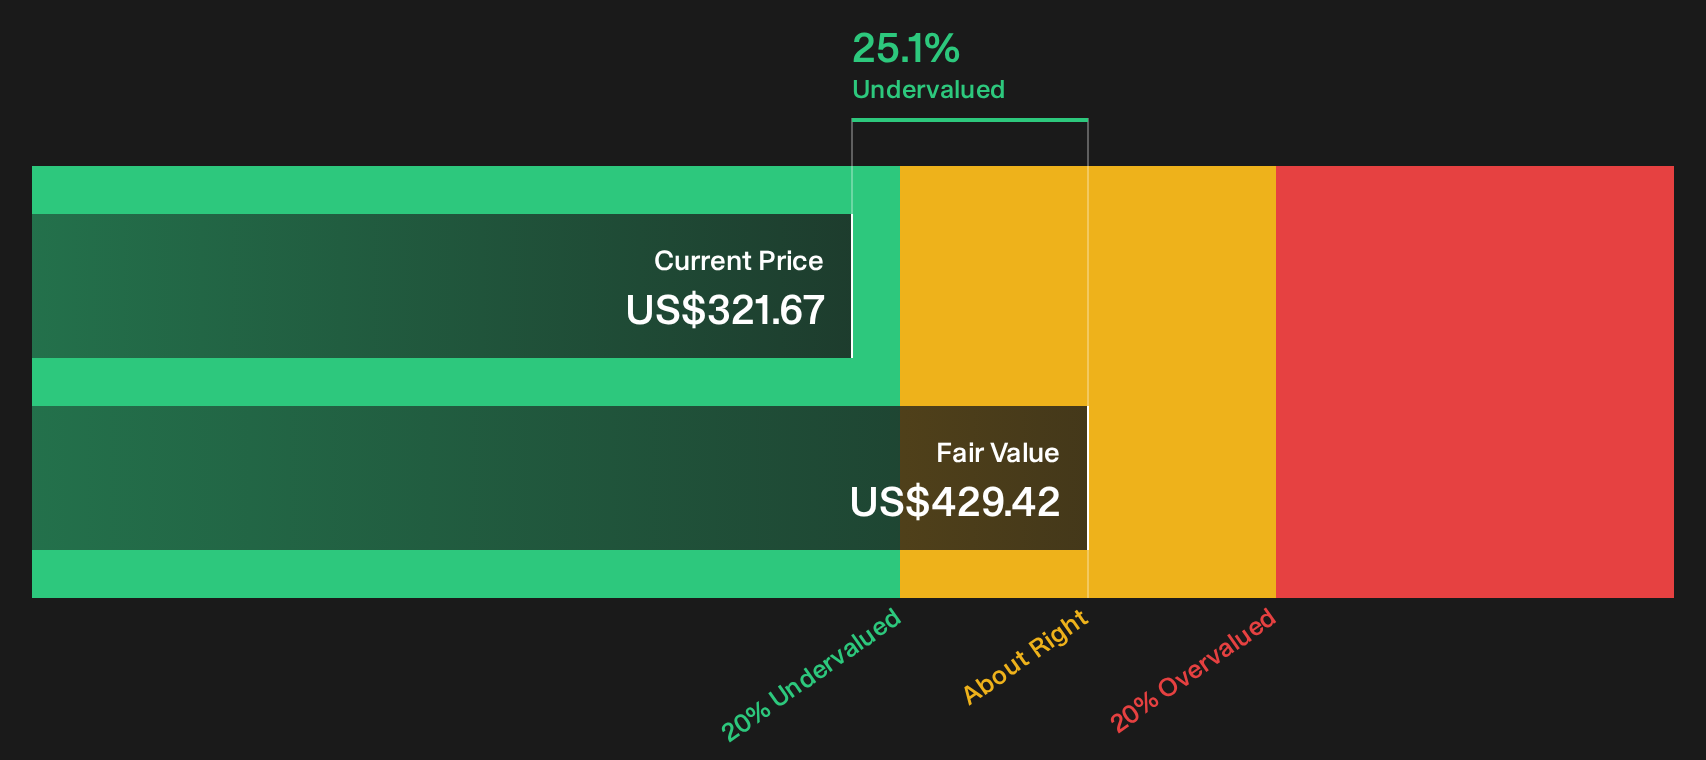
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals run through this Aon story, so move quickly, review the full risk and reward balance, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aon?
Do not stop at Aon. Broaden your watchlist now using focused screens that can surface different types of opportunities before they move out of reach.
- Hunt for quality on sale by scanning a curated pool of stocks that screen as potentially mispriced using the 36 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that aim to combine higher yields with resilience through the 5 dividend fortresses.
- Prioritise balance sheet strength and financial robustness by running the list of solid balance sheet and fundamentals (24 results) so weaker businesses do not quietly drag on your returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com