
UFP Technologies (UFPT) Stock Dropped, So What Is Driving Attention Today?
UFP Technologies (UFPT) heads into this Tuesday’s post-market earnings release with fresh attention after previously topping revenue and EPS expectations, with analysts looking for continued year-on-year growth.
Recent trading has cooled, with the share price down 3.0% over the last session and 15.0% over 90 days. This comes even though the year-to-date share price return is 27.4% and the 5-year total shareholder return of 327.1% points to strong longer term momentum.
Scan beyond UFP Technologies and explore other potential earnings movers with our curated list of 19 high quality undiscovered gems.
UFP Technologies now trades almost 20% below the average analyst target, even after a strong multi year share price run and recent pullback. Is that discount a bargain or a warning about stretched expectations?
Most Popular Narrative: 20% Undervalued
UFP Technologies closed at $284.50, while the most followed narrative pegs fair value at $355, about 20% higher. That gap rests on the expectation that recent investments and medical focus will support a premium profile over time.
The expansion of manufacturing capacity and product development centers in the Dominican Republic, along with new program launches for robotic-assisted surgery customers, sets the stage for sustained revenue growth tied to increased demand for sophisticated medical device components and packaging solutions.
Robust growth in multiple medical end markets including patient services, interventional, surgical, and wound care reflects the tailwind from a growing, aging population and rising prevalence of chronic diseases, which are likely to accelerate top-line growth as channel inventory destocking is now behind the company.
See why 5 investors see UFP Technologies as 20% undervalued.
The fair value estimate of $355 is built using a 7.45% discount rate and narrative assumptions that combine expected revenue growth, margin targets, and what investors are willing to pay for those future earnings. That approach leans on UFP Technologies continuing to focus on higher margin medical segments while managing customer concentration, acquisition integration, and capacity moves such as the Dominican Republic expansion.
Result: Fair Value of $355 (UNDERVALUED)
Still, the narrative around UFP Technologies could shift quickly if customer concentration issues or further manufacturing disruptions weigh on orders or margins.
Find out about the key risks to this UFP Technologies narrative.
Another View: UFP Technologies Through The P/E Lens
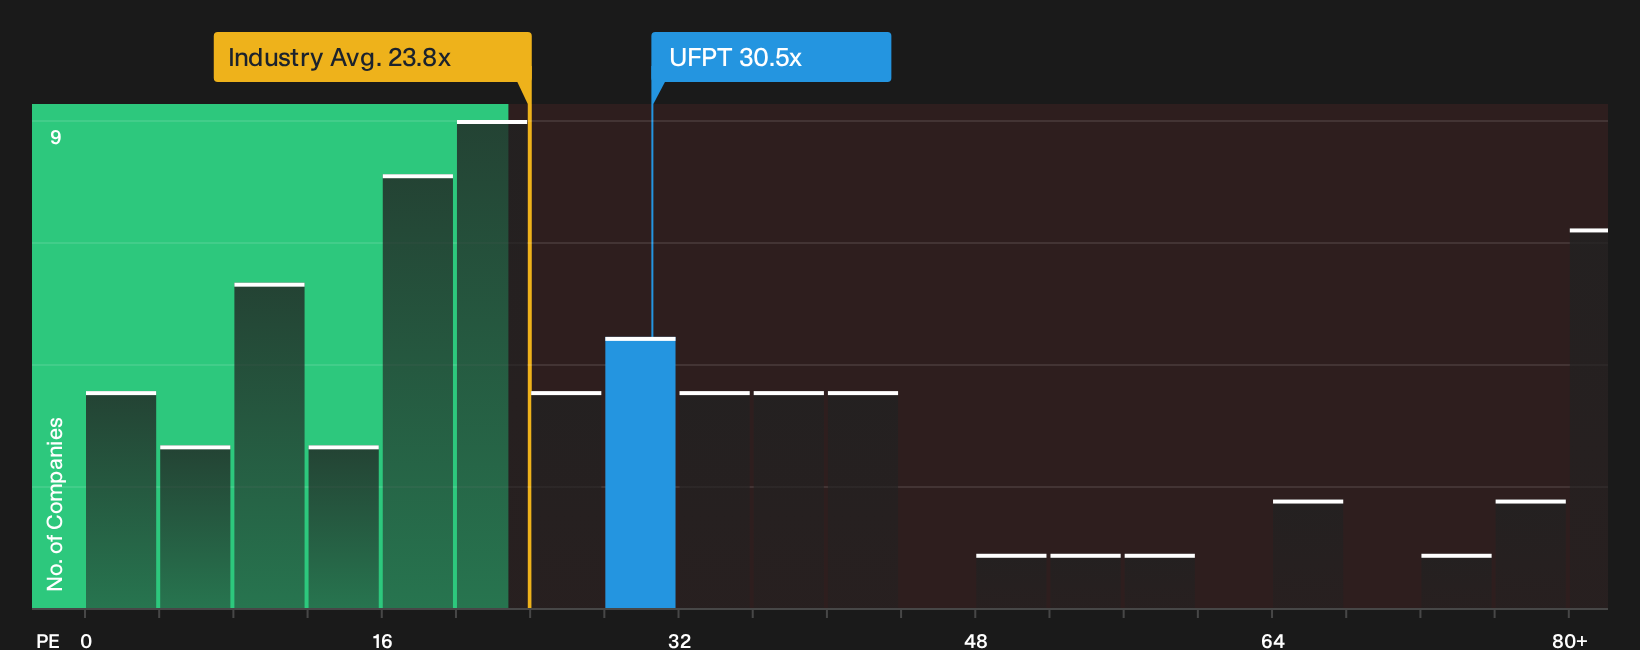
The narrative fair value of $355 per share paints UFP Technologies as undervalued, yet the P/E picture reads differently. The stock trades on about 30.5x earnings, above the US Medical Equipment sector at 23.8x and above a fair ratio of 25.7x implied by regression analysis.
Put simply, investors are already paying a richer multiple than both the industry and that fair ratio, which suggests less cushion if sentiment cools. The peer group average P/E of 60.4x shows some investors pay far more for growth in this space, but also underlines how quickly expectations can reset if the story changes.
For anyone weighing these signals, the question becomes whether the medical focus and past execution justify that premium, or whether the fair ratio is the level the market could eventually drift toward.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on UFP Technologies so far. If you want to move quickly and form your own view, consider both sides and review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond UFP Technologies?
If UFP Technologies has your attention, do not stop here. Broaden your watchlist with fresh ideas sourced from focused screens built around quality, value, and resilience.
- Zero in on potential mispricing opportunities by scanning a curated set of quality stocks trading below what fundamentals may justify through the 36 high quality undervalued stocks.
- Prioritize dependable balance sheets and fundamentals by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you stress test your portfolio against financial fragility.
- Dial back portfolio risk and concentrate on stability by filtering for 29 resilient stocks with low risk scores that some investors may overlook until it is too late.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com