
Tourmaline Oil (TSX:TOU), What Is Behind The Latest Attention?
Tourmaline Oil (TSX:TOU) is increasing its exposure to international LNG benchmarks such as JKM and TTF, with plans to tie 220 million cubic feet per day to these prices starting in 2026.
The latest move into LNG-linked pricing comes as Tourmaline Oil’s share price shows building momentum, with a 10.73% one-month share price return and 12.76% three-month share price return at a last close of CA$68.64.
Scan for other gas producers with similar momentum and diversified pricing by starting with the hand-picked 16 top copper producer stocks that is aligned with Tourmaline Oil’s LNG-linked shift.
Tourmaline Oil now has LNG-linked upside and a share price that has already moved. Does that shifting mix still leave enough potential reward to justify the current risk?
Most Popular Narrative: 3% Undervalued
Tourmaline Oil’s most followed narrative pins fair value at CA$71.07, only slightly above the last close at CA$68.64. This keeps the focus firmly on whether LNG-linked volumes and new infrastructure can shift the risk and reward balance.
The phased Northeast BC Montney infrastructure build out, including the Aitken and Groundbirch Monias plants and associated pipelines, is expected to add 1.1 billion cubic feet per day of gas handling capacity and generate an anticipated structural incremental annual cash flow contribution of over $400 million once both phases are complete. This directly supports net margins and free cash flow.
See why 106 investors see Tourmaline Oil as 3% undervalued.
Result: Fair Value of CA$71.07 (UNDERVALUED)
Still, Tourmaline Oil faces real pressure if Western Canadian gas benchmarks stay weak or if the paused second phase of its Northeast BC build takes longer than planned.
Find out about the key risks to this Tourmaline Oil narrative.
Another View: Tourmaline Oil Looks Expensive On Earnings
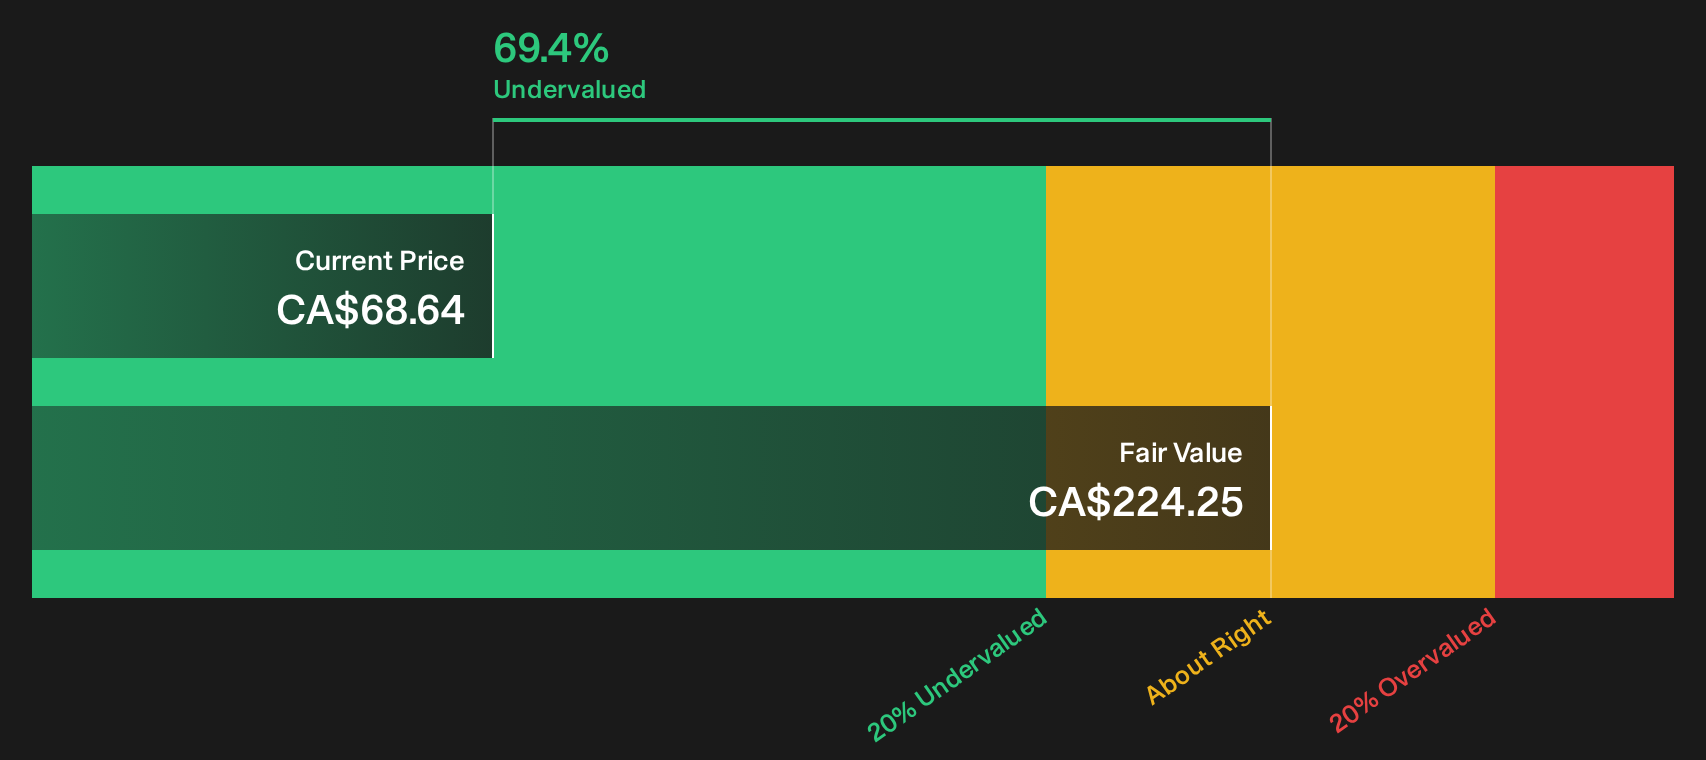
Tourmaline Oil screens as deeply undervalued on the SWS DCF model, with the current CA$68.64 price sitting well below an estimated future cash flow value of CA$224.25. Yet on earnings, the stock trades at a rich 70.7x P/E versus a 21.2x industry average and a 25.8x fair ratio. Is this a mispriced opportunity, or just a lot of optimism baked into one ticker?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split between optimism and caution around Tourmaline Oil feels sharp, that is the point, and it is why acting early on your own research matters. To weigh that tension directly against the data, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Tourmaline Oil?
Tourmaline Oil may sit at the center of your watchlist today, but casting a wider net with structured ideas can help refine your next move.
- Target resilient cash generators by scanning the 3 dividend fortresses that focus on income strength and durability.
- Look for quality at a potential discount and use the 8 high quality undiscovered gems to surface opportunities that the crowd may be overlooking.
- Prioritize capital preservation and filter through the 9 resilient stocks with low risk scores to spot businesses with sturdier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com