
TransDigm Group (TDG) Stock Dropped, So What Is Drawing Attention Now?
TransDigm Group (TDG) has moved back into focus after reporting Q3 results with 23% growth in net sales, 13% growth in adjusted EPS, and 19% growth in EBITDA, along with increased hedge fund ownership.
Despite the strong Q3 numbers and increased hedge fund interest, TransDigm Group’s short-term momentum has cooled. The 90-day share price return is down 10.06% and the year-to-date share price return is down 15.59%, even though the 5-year total shareholder return is up 104.54%.
Spot potential peers to TransDigm Group with hedge fund interest and strong recent earnings trends by scanning our hand-picked 19 high quality undiscovered gems in similar quality-focused corners of the market.TransDigm Group now trades at a clear discount to both analyst targets and an intrinsic value estimate after a double digit pullback. Is that a pricing error, or is the market quietly flagging real risk?
Most Popular Narrative: 19% Undervalued
On the narrative view, TransDigm Group’s fair value sits at $1,414.30, which is well above the last close of $1,146.81 and frames the recent pullback as a valuation gap that hinges on how durable its aftermarket engine really is.
The main thing that has to go right is continued execution on leveraged, acquisition led growth, while managing regulatory scrutiny, right to repair risk, and a structurally high net debt to EBITDA profile.
See why 37 investors see TransDigm Group as 19% undervalued.
Result: Fair Value of $1,414.30 (UNDERVALUED)
Still, the TransDigm Group story leans heavily on acquisitions and tight control of aftermarket parts, so tougher antitrust scrutiny and right to repair rules could quickly challenge that thesis.
Find out about the key risks to this TransDigm Group narrative.
Another View: TransDigm Group Through The P/E Lens
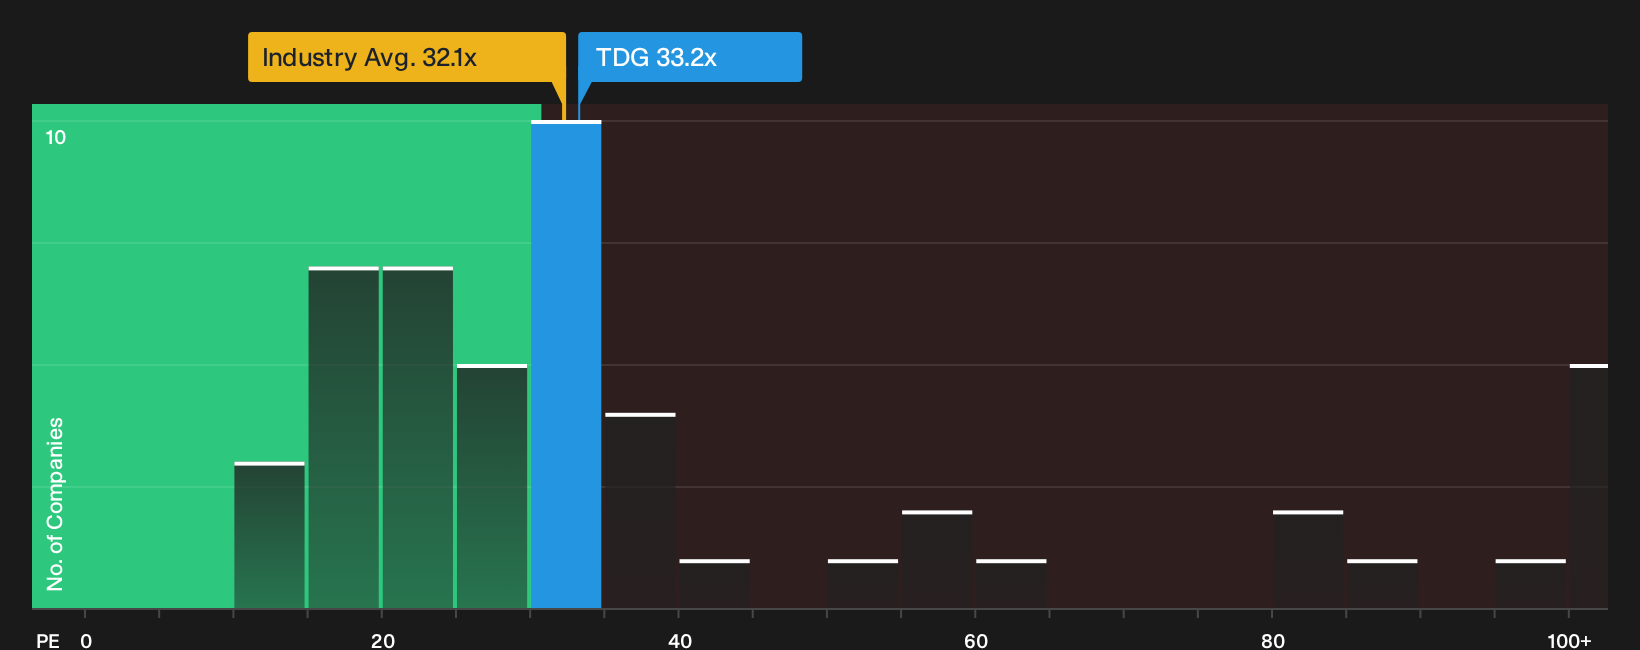
The first story on TransDigm Group leans on cash flow and intrinsic value. A second look uses the P/E ratio, and that picture is less forgiving. TDG trades on 33.2x earnings versus 32.1x for the US Aerospace & Defense group, 26.5x for peers, and a fair ratio of 30.9x. This points to richer pricing and some valuation risk if sentiment cools or growth expectations slip.
Investors who want to stress test that richer P/E against earnings quality, sector benchmarks, and the fair ratio can go deeper with the valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on TransDigm Group’s valuation and risks can cut both ways, so move quickly, review the underlying data, and weigh 4 key rewards and 3 important warning signs carefully.
Looking for more investment ideas beyond TransDigm Group?
You have a clear view on TransDigm Group. Now broaden your opportunity set and test your thinking against other stocks with different risk and reward profiles.
- Target value upside with quality fundamentals by scanning a curated set of 36 high quality undervalued stocks that may offer more compelling entry points than crowded stories.
- Prioritise resilience and aim to sleep better at night by reviewing a 29 resilient stocks with low risk scores that focuses on sturdier balance sheets and steadier business profiles.
- Look beyond the mainstream by tracking a 19 high quality undiscovered gems that highlights underfollowed companies before attention and liquidity potentially build.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com