
Descartes Systems Group (TSX:DSG) Could Be 20% Below Fair Value After Customer Wins
Descartes Systems Group (TSX:DSG) just picked up fresh customer momentum, with Herschel Parts and WEL Companies adopting its logistics tools to streamline shipping workflows and brokered freight operations.
Despite these customer wins, Descartes Systems Group’s share price has been choppy in the short term, falling 1.55% over the past day and 4.65% over the past week. At the same time, the 30-day share price return of 11.19% and 90-day gain of 16.41% point to building momentum, supported by a 1-year total shareholder return of 2.21% and 24.68% over three years.
Scan logistics-focused opportunities that follow themes similar to Descartes Systems Group by exploring our curated list of 95 robotics and automation stocks.
Descartes Systems Group has just bounced over the past quarter after a softer week, which leaves a practical question for you as an investor: Is it worth stepping in at CA$126.77 or waiting for a cheaper entry before the next move?
Price-to-Earnings of 41.3x: Is it justified?
On simple valuation math, Descartes Systems Group trades on a P/E of 41.3x, which sits beside a last close of CA$126.77 and points to a rich earnings multiple rather than a discount story.
The P/E ratio compares what investors pay for each dollar of current profit, and for a software platform with subscription style revenue and logistics tools like Descartes Systems Group, earnings based metrics tend to carry a lot of weight.
Here, the market is putting a higher price on each dollar of profit than both the firm’s own estimated fair P/E of 27.9x and the wider North American software cohort on 31.8x. This suggests buyers today are paying up for its earnings profile and treating the current growth and margin mix as worth a premium that could compress if expectations cool.
Against that, the fair P/E ratio of 27.9x provides a reference level that the valuation could gravitate toward if sentiment or growth assumptions reset. This makes the current 41.3x gap important for you to notice when comparing alternatives.
Explore the SWS fair ratio for Descartes Systems Group.
Result: Price-to-Earnings of 41.3x (OVERVALUED)
Still, a rich 41.3x P/E leaves Descartes Systems Group exposed if sentiment cools or if recent double digit revenue and net income growth rates slow.
Find out about the key risks to this Descartes Systems Group narrative.
Another view on Descartes Systems Group’s value
The P/E screen paints Descartes Systems Group as expensive, yet our DCF model points in the opposite direction. At CA$126.77, the stock trades about 20.4% below an estimated future cash flow value of CA$159.32. That sounds more like a discount than a premium. So which lens do you trust when the signals conflict?
Look into how the SWS DCF model arrives at its fair value.
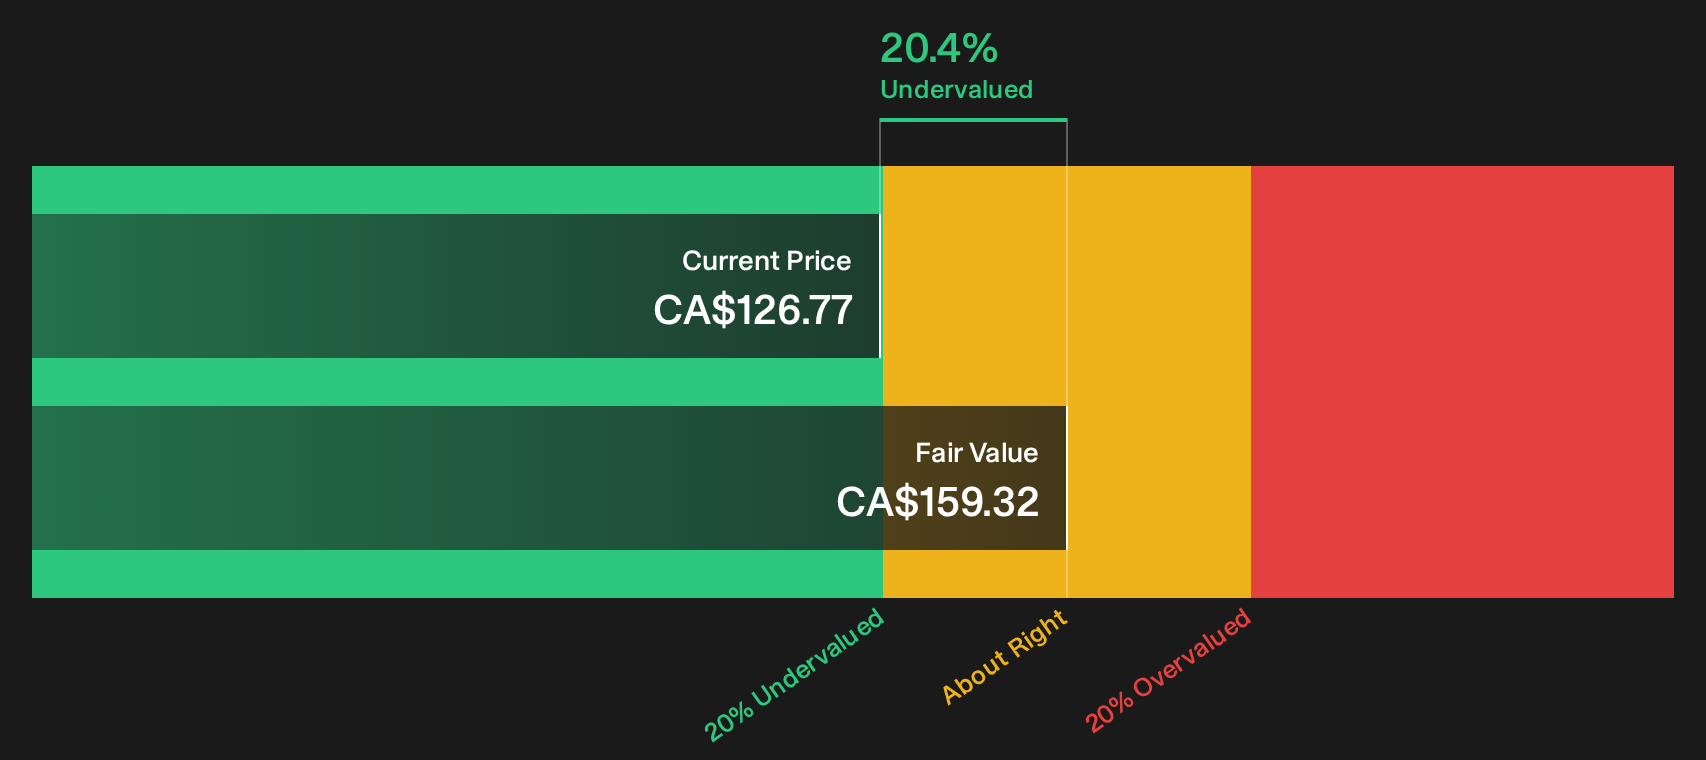
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Descartes Systems Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Descartes Systems Group so far. If you want to move quickly and rely on your own judgement, weigh the data on both sides and review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Descartes Systems Group?
If Descartes Systems Group has your attention, do not stop here. Use fresh ideas from wider markets so you are not relying on a single story.
- Target long term compounding potential by reviewing a curated set of quality companies trading at appealing valuations through the 3 high quality undervalued stocks.
- Strengthen your portfolio’s resilience by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (6 results).
- Get ahead of the crowd by scanning a focused shortlist of underfollowed opportunities via the 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com