
Glaukos (GKOS) Just Moved, What Is Drawing Fresh Attention?
Why Glaukos stock is back in focus
Glaukos (GKOS) moved onto more investors’ watchlists after its late October earnings update, which paired stronger third quarter results with higher 2026 sales guidance and a new 2027 revenue outlook.
The late October guidance lift helped ignite a sharp move higher, with a 7-day share price return of 33.28% and a 30-day gain of 45.10%, building on year-to-date share price momentum of 114.60% and a 1-year total shareholder return of 171.88%.
Scan for other ophthalmology and healthcare stocks showing fresh earnings momentum by starting with our curated list of 33 healthcare AI stocks, which ties real business performance to market-moving price action.
After a move like this, Glaukos now forces a simple question: Do the new sales targets and first profitable quarter in a while still leave enough upside for fresh buyers, or has most of the payoff already been pulled forward?
Most Popular Narrative: 19% Overvalued
Glaukos last closed at $237.60, while the most followed narrative pegs fair value at $199.31 using a 7.54% discount rate. That gap reflects a view that the share price already builds in ambitious assumptions on growth, profitability and long term reinvestment.
Deep multi platform R&D investment, including 13 to 14 publicly disclosed programs across glaucoma, cornea, retinal and ocular surface disease and the addition of up to five retinal biologics through the RevOpsis agreement, is aimed at building new revenue streams that can layer on top of the current glaucoma and corneal health contributions and support longer term earnings power.
See why 2 investors see Glaukos as 19% overvalued.
Result: Fair Value of $199.31 (OVERVALUED)
Still, Glaukos faces real pressure if Medicare coverage for iDose TR tightens or if Epioxa reimbursement hurdles keep slowing procedures and holding revenue below current expectations.
Find out about the key risks to this Glaukos narrative.
Another View on Glaukos: Cash Flows Tell a Different Story
While the crowd sourced fair value of Glaukos lands at $199.31 and flags the stock as overvalued, the SWS DCF model points in the opposite direction. On that framework, GKOS at $237.60 trades about 35% below an estimated future cash flow value of $364.66, which frames the current price as a discount. Which lens feels more reasonable for you: multiples based narratives or cash flow math?
To understand how this cash flow view is built and what would need to change for Glaukos to screen differently, take a closer look at the Look into how the SWS DCF model arrives at its fair value.
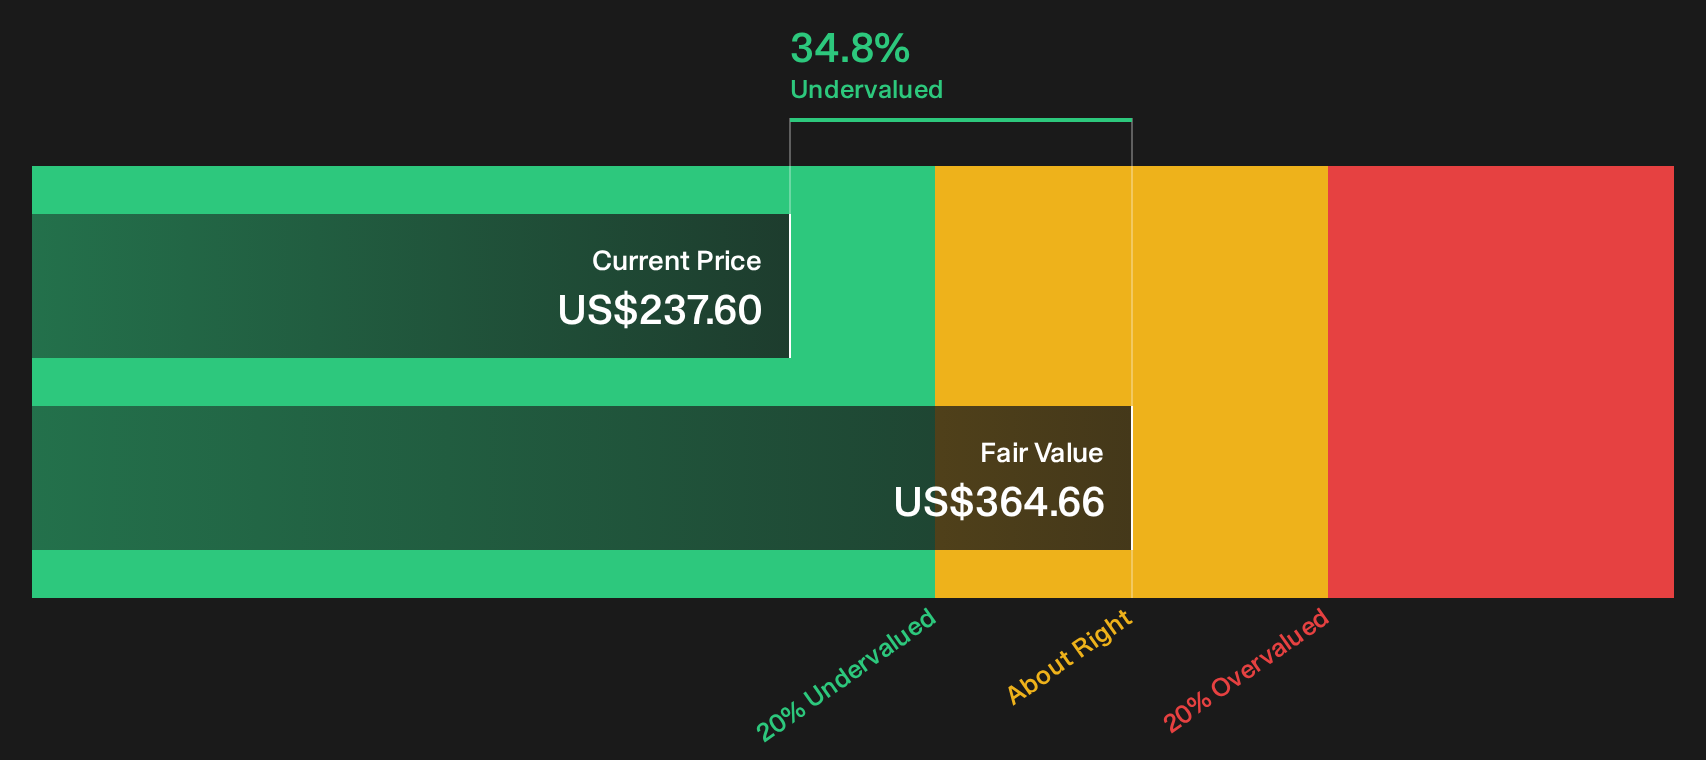
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Glaukos for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big moves in Glaukos often split opinion. If you want to act while sentiment is still settling, weigh the upside against the risks using the 2 key rewards and 2 important warning signs
Looking for more Glaukos sized investment ideas?
If Glaukos has your attention, do not stop at one ticker. Fresh opportunities often sit just outside your current watchlist, waiting for a closer look.
- Upgrade the quality of your watchlist by scanning companies that pair strong balance sheets with resilient fundamentals through the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by reviewing the 36 high quality undervalued stocks that combine robust cash flows with supportive financial footing.
- Build a steadier income stream by screening for high yield payers in the 5 dividend fortresses before the next ex dividend dates approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com