
Missed UCB's Run? Here's What The Latest Numbers Tested
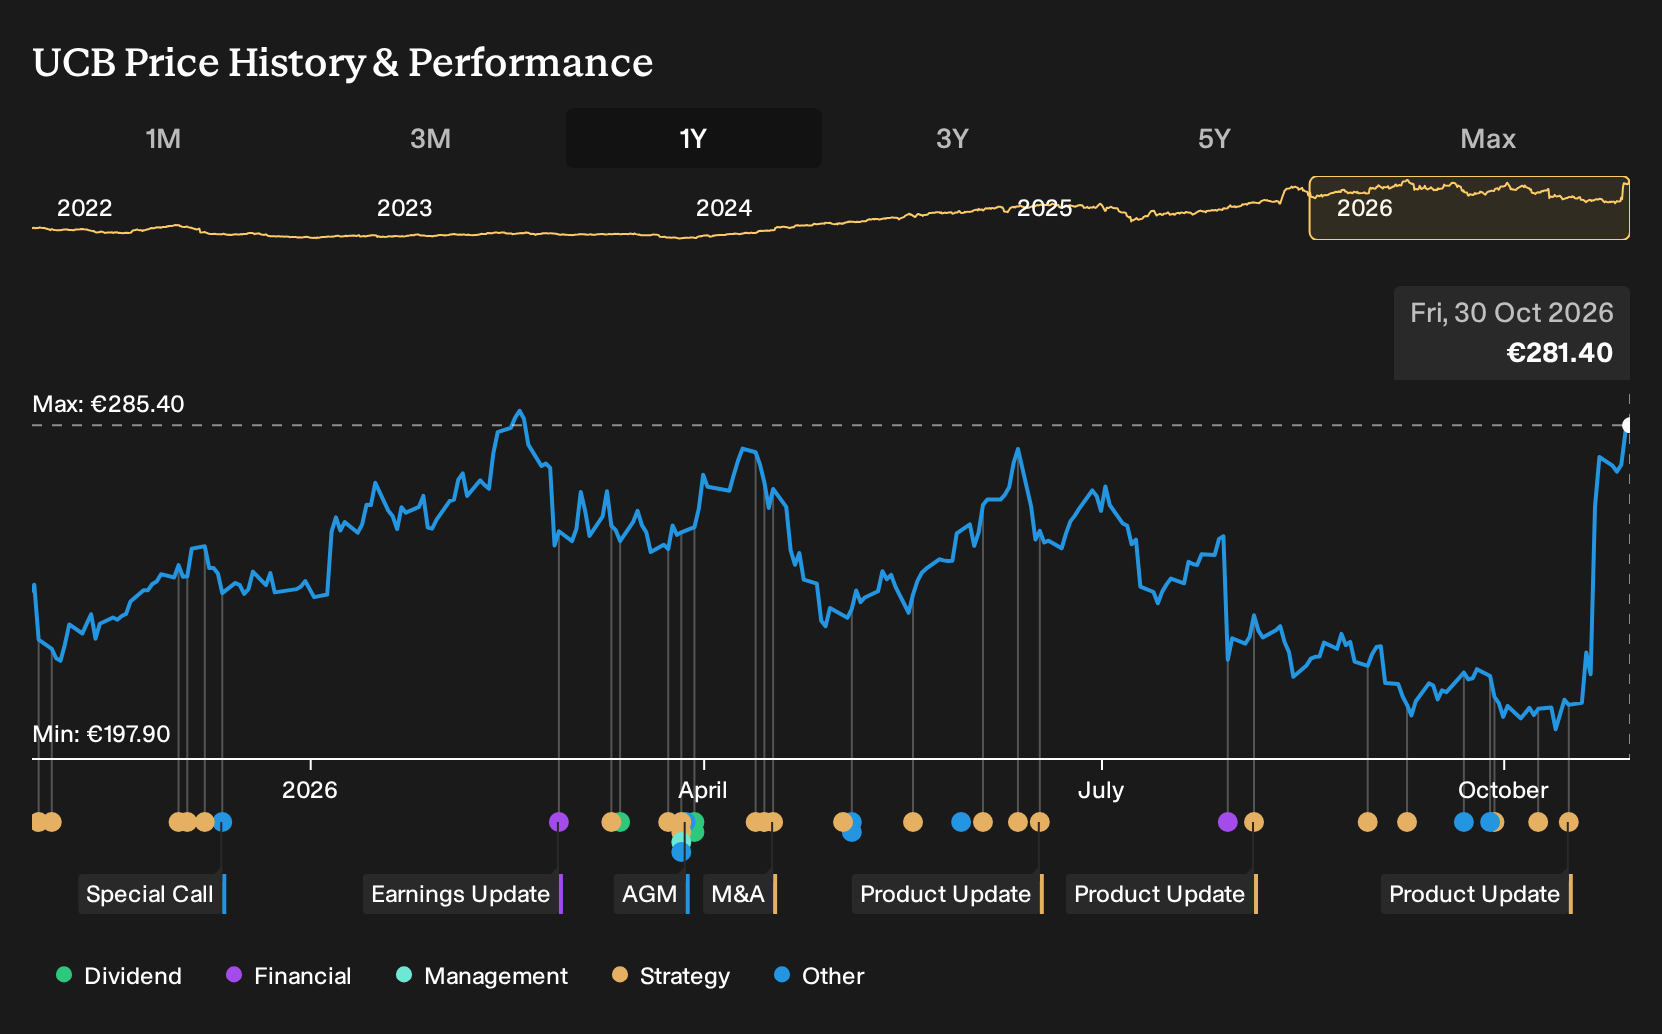
If UCB was sitting on your watchlist instead of in your portfolio, the outcome over the past year may feel expensive. Investors who held UCB over the past year are up 28.5%, including dividends. That gain arrived while analysts were split between a “decade of growth” built on aging populations and digital health, and fears about pricing pressure and patent cliffs. If you rewind to October 2025, how could you have judged whether biologics adoption would outweigh those headwinds?
UCB has already moved. Pinpoint other ways to investigate the theme among 127 healthcare AI stocks.
The Argument You Would Have Been Weighing Up On UCB
The shares cost €238 at the start of the period, so any view on UCB had to begin with whether that price already captured a full decade of biologics enthusiasm.
The bullish story saw aging populations and digital health as powerful demand drivers, with a Fair Value of €255, a price implied by assumptions such as revenue rising 16.3% a year and margins lifting from 19.5% to 25.0% by 2028.
The bearish case argued that rising US price cuts and patent losses would bite, backing a Fair Value of €160 and stressing risks like expected annual double-digit price reductions for BIMZELX and pressure from biosimilars on legacy drugs such as Cimzia and Vimpat.
What The Evidence Around UCB Actually Tested
UCB’s H1 2026 report showed revenue at €4,270m and net income at €1,111m, alongside a net margin of 26.0% compared with 13.6% a year earlier. That mix of higher sales and wider profitability supported the optimistic case that biologics adoption and product launches could offset pricing and patent worries, although future pressures were not settled.
The useful takeaway is simple. When you see a growth story built on new therapies, test it against reported revenue and net margin together, not just headline guidance or pipeline headlines.
What UCB’s Price Now Asks You To Believe
Today UCB trades at €281. The selected Narrative’s Fair Value sits below that level, which is the author’s judgement rather than a hard fact about what the shares should be worth.
The deep-dive hangs on discounted cash flows and on whether recent guidance and margins prove durable. A buyer at €281 is effectively assuming today’s profitability can be sustained, so the question is how that assumption holds up once acquisition risks and margin sensitivity are weighed.
"Two numbers worth stating plainly: 77 % of the DCF''s value sits in the terminal value, and the WACC-minus-growth spread is 5,84 %. A model with three-quarters of its answer beyond year five is a model whose long-run assumptions are doing the work."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where UCB’s Theme Extends Next
UCB leans on chronic disease trends. You could also examine who tackles those same long duration conditions differently.
One large pharmaceutical group is pushing into obesity and diabetes medicines that change how patients manage weight and blood sugar.
It is pairing injectables with an oral option and combination regimens, aiming to widen treatment reach and shape distinct efficacy tiers.
The same business is also working on cancer, immune disorders and brain conditions, adding pillars so no single therapy dominates its portfolio.
If chronic illness demand holds, that broader toolkit could matter as much as any single breakthrough narrative.
One Narrative has already put a figure on it. → Uncover the company trading 14% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com