
Canadian Stock Market Today: TSX Futures Edge Higher On Improved Deficit And Data Watch
The Morning Bull - Canadian Market Morning Update Monday, 2 Nov 2026
Canadian stocks are set for a slightly firmer open, with the S&P/TSX 60 futures edging higher. The big driver this morning is Canada’s improving fiscal picture, which is helping steady sentiment around domestic bonds and the Canadian dollar.
Ottawa’s federal deficit narrowed to C$223 million in August, while revenues rose 7.1% and spending moved up more modestly. That combination points to softer near term fiscal pressure, which matters because it can ease concerns about heavy government borrowing competing with private funding needs.
For you, the link runs through borrowing costs and profit expectations. A cleaner budget profile can support confidence in Canadian government debt, which can feed into steadier funding conditions for banks, capital intensive industries, and income focused sectors tied to domestic rates.
The open question is how long this fiscal breathing room lasts once growth and election debates re enter the picture. The next real test for this calmer tone comes with incoming Canadian manufacturing PMI and trade data; those releases could reshape how investors treat today’s good news.
Stocks to Watch Before the Opening Bell
Fortuna Mining (FVI)
Fresh drill results from Fortuna Mining’s Bambadji Project in Senegal are in focus. The explorer reported 1.9 g/t gold over 64 meters at the Kabewest prospect, from a 45 hole first phase program that forms part of an $8 million campaign running through 2026. Management is targeting an initial Inferred Mineral Resource estimate in early 2027.
Fairfax Financial Holdings (FFH)
Fairfax Financial is at the center of a proposed $5.5b takeover of India’s state owned IDBI Bank. Employee unions and political parties are pushing back, raising transparency and valuation concerns and planning a two day strike. The Indian government has framed the deal as the largest foreign direct investment into the country’s financial sector.
Bank of Montreal (BMO)
Bank of Montreal has closed its purchase of Euroz Hartleys’ Australian capital markets business. The deal folds equities research, institutional sales and trading, capital markets, M&A, and advisory operations into BMO Capital Markets. Investors watching BMO’s global metals and mining franchise now have a larger platform across Australia, North America, and Europe to track.
Top Movers
- Methanex (TSX:MX) surged 13.76% after strong Q3 earnings, a new buyback plan, a guidance update, and a higher analyst target.
- Black Diamond Group (TSX:BDI) climbed 7.38% on record Q3 revenue, a higher dividend, and a new board appointment.
- Imperial Oil (TSX:IMO) advanced 5.37% following record Q3 net income, downstream strength, buybacks, and a reaffirmed dividend.

Top Losers
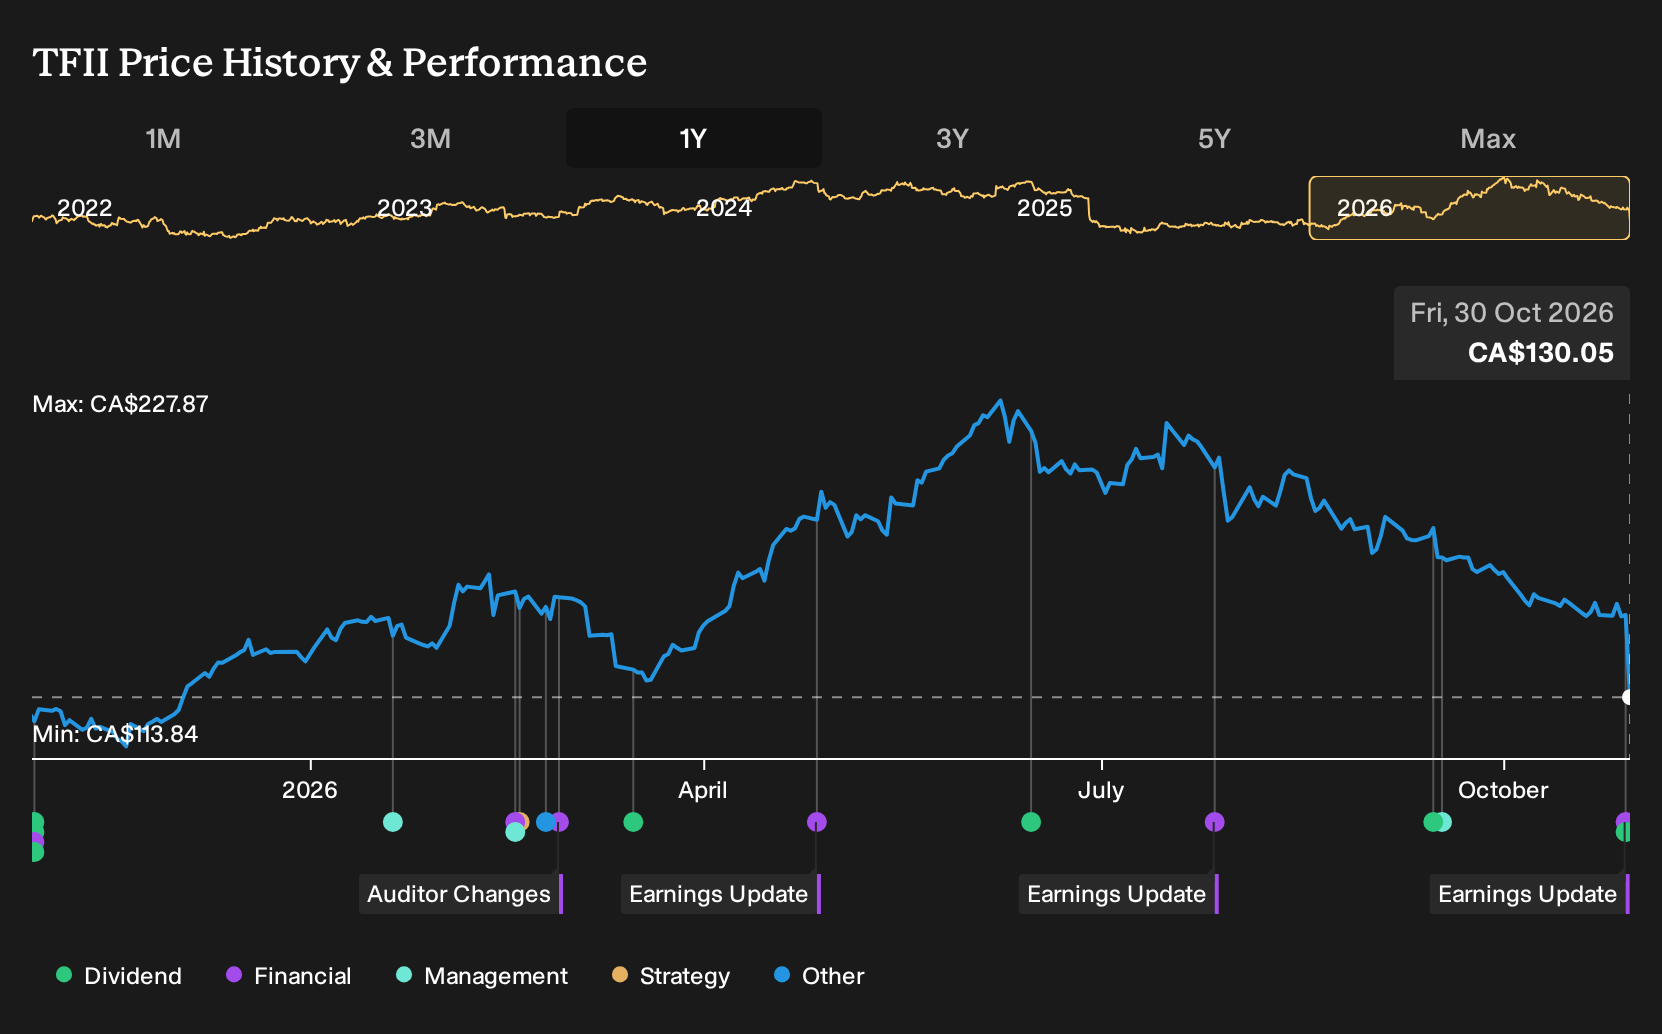
- TFI International (TSX:TFII) declined 17.24% after Q3 results and a sharply lower Q4 outlook, which triggered multiple price target cuts.
- Bird Construction (TSX:BDT) declined 10.69%.
- Lundin Mining (TSX:LUN) declined 8.46% after updating buyback activity and approving an extra US$100 million in repurchase capacity.
On The Radar
Canadian markets face a packed stretch of domestic earnings and macro data, capped by twin labour reports from Ottawa and Washington that speak directly to rate expectations and sector funding costs.
- S&P Global Canada Manufacturing PMI Mon 2 Nov. The October PMI follows a previous 51.5 reading, and a result meaningfully above the 51 forecast would signal firmer factory activity that can stiffen rate expectations and keep borrowing conditions tight for rate sensitive stocks.
- Lightspeed Commerce Thu 5 Nov. Q2 2027 results land pre market, where software subscription revenue trends and transaction volumes will show how merchants are handling costs and what that implies for broader Canadian tech appetite.
- TC Energy Thu 5 Nov. Q3 2026 numbers before the open put a spotlight on pipeline cash flow and capital spending, which are key inputs for how investors assess funding needs across Canadian midstream and the wider energy complex.
- Enbridge Fri 6 Nov. Pre market Q3 2026 results focus attention on distributable cash flow and any commentary on large growth projects, which feeds into how investors think about income reliability and future financing for major Canadian pipelines.
- Canada labour market data Fri 6 Nov. October unemployment is forecast at 6.5% with employment seen rising 15,000, and a materially stronger print could reinforce higher for longer rate expectations that weigh on rate sensitive real estate and utilities.
Sector & Industry Watch
Energy: Oil strength keeps sector in focus
Energy has inched higher over the last week and past month, helped by crude trading near US$100 and strong 1 year gains. That supports cash flow for producers and pipeline operators, which can affect how much they return through dividends or put into new projects that feed jobs and service work across Canada.
The key trigger to watch is this week’s US crude and gasoline inventory data, since a sharp move in stockpiles often shifts oil prices and sentiment toward Canadian Energy stocks.
Materials: Soft month as miners keep spending
Materials is down over the last week and has dropped more sharply over the past month, even as companies such as Cascades keep working on longer term priorities. Lower prices for the group can influence how easily miners and chemical producers raise money for drilling, plant upgrades, or acquisitions that flow through to suppliers and local communities.
For this sector, today’s Canadian Manufacturing PMI is the data point that matters because a weaker factory reading would reinforce cautious demand expectations for industrial metals and packaging materials.
Metals and Mining: Battery metals and gold stay busy
Metals and Mining has retreated over the past week and month, while project news continues from E3 Lithium, Fortuna Mining, Soma Gold and Nevada Organic Phosphate. That mix of weaker prices and ongoing drilling or study work affects how investors weigh near term share swings against long lead projects tied to electrification and resource exports.
The single catalyst to track is Wednesday’s Canada trade balance release, since any shift in export momentum for metals and energy products can sway interest in this industry.
Real Estate: Rate sensitive sector still under strain
Real Estate is down over the last week and remains weaker over the past year and year to date, even with a small 30 day gain. Higher borrowing costs matter for REITs and property managers that depend on refinancing, because pricier loans can reduce cash available for distributions or new developments.
If you hold Real Estate exposure, Friday’s Canadian labour market report is important because a softer jobs backdrop can weigh on occupancy, rent growth and retail foot traffic.
Tech and Semiconductors: Weak chips, selective software wins
Tech has eased over the past week and month, while Semiconductors have fallen far more across all reported periods, reflecting pressure on hardware exposed stocks. At the same time, software players such as Predictiv AI landing an agreement with Metrolinx show that recurring contract opportunities still exist within Canadian technology.
The US ISM Manufacturing PMI later today is the main cue for these groups, since a weaker factory reading south of the border can influence demand expectations for electronics and industrial chips tied to Canadian suppliers.
Where Are The Opportunities Now?
If higher borrowing costs are still weighing on your Real Estate holdings, it can help to focus on steadier balance sheets using this list of list of solid balance sheet and fundamentals (6 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com