
Intercontinental Exchange (ICE) Climbed, What Is Driving Attention Now?
Intercontinental Exchange (ICE) just paired a higher quarterly dividend with fresh third quarter numbers and a new Trade.xyz partnership, putting both cash returns and future market expansion in focus for investors.
The latest move comes after a strong run in Intercontinental Exchange’s share price, with a 1-day share price return of 3.56% and a 30-day share price return of 12.45% pushing the stock to $168.85. A 1-year total shareholder return of 17.52% and 3-year total shareholder return of 62.61% suggest momentum has been building around ICE’s earnings delivery, dividend increases, and recent product and partnership announcements.
Scan how Intercontinental Exchange compares with other exchange and market infrastructure operators by reviewing our curated list of 54 AI infrastructure stocks that are in a similar position on cash generation and scale.
The business looks strong on earnings, buybacks, and a higher dividend. After the latest jump to $168.85, is Intercontinental Exchange still reasonably priced, or are investors paying a rich premium for that strength?
Most Popular Narrative: 12% Undervalued
On the most followed view, Intercontinental Exchange screens as modestly undervalued, with a narrative fair value of about $191.07 against the latest $168.85 close. This puts the current debate firmly on whether its investment spend earns out over time.
The main thing that has to go right is that Intercontinental Exchange successfully executes its higher spending on data centers, AI hardware, and product development so that rising operating expenses and CapEx translate into sustained growth in fixed income, data services, and mortgage technology.
The current valuation implies that the market is cautious about how much value Intercontinental Exchange will ultimately create from its investments in MarketAxess, private credit infrastructure, AI-ready data platforms, and digital asset adjacencies, which this narrative views as leaving the stock undervalued.
See why 41 investors see Intercontinental Exchange as 12% undervalued.
Result: Fair Value of $191.07 (UNDERVALUED)
Still, if Intercontinental Exchange ends up with heavier data center and AI spending that fails to lift recurring revenue, or if the MarketAxess integration drags on earnings, this view of undervaluation weakens quickly.
Find out about the key risks to this Intercontinental Exchange narrative.
Another Angle on Intercontinental Exchange’s Valuation
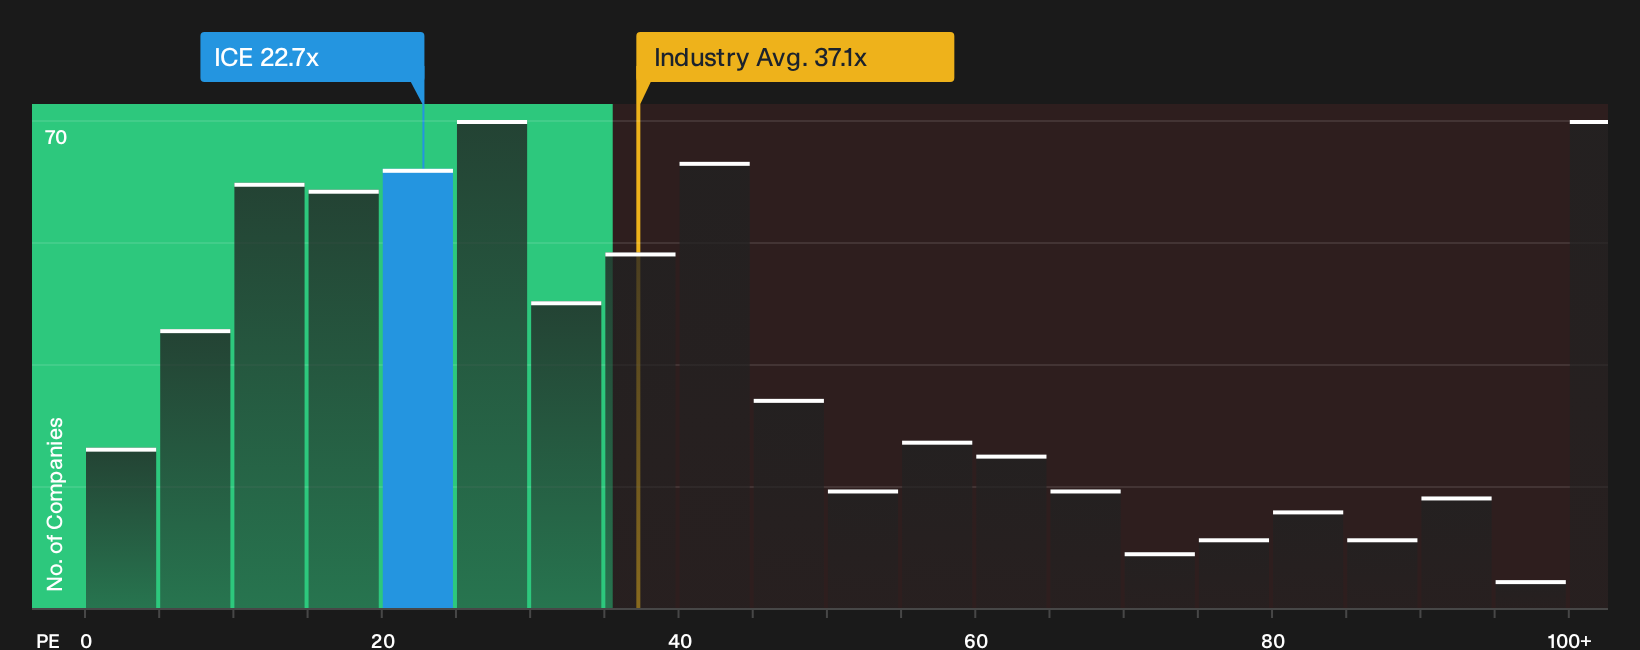
That 12% undervaluation narrative runs into a very different signal from the market’s own pricing. Intercontinental Exchange trades on a P/E of 22.7x, while the fair ratio suggests 16.2x. The wider Capital Markets industry sits at 37.1x and close peers around 27.1x, so ICE looks cheaper than its group but richer than its own fair ratio. Should investors treat that gap as cushion or as extra valuation risk?
See what the numbers say about this price in our valuation breakdown, then compare your own expectations against the See what the numbers say about this price — find out in our valuation breakdown..
Here is how Intercontinental Exchange’s current P/E stacks up against its sector and this fair ratio anchor
Next Steps
Feeling pulled between optimism on Intercontinental Exchange’s potential and concern about the risks in the background is natural. Move fast and weigh the evidence on both sides for yourself with the full breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Intercontinental Exchange?
If you like the setup around Intercontinental Exchange but want options, use the Simply Wall Street Screener to scan other opportunities before the crowd moves on.
- Target resilient balance sheets and steady fundamentals by running a focused search across our list of solid balance sheet and fundamentals (24 results) so you are not relying on one ticker.
- Hunt for potential bargains by comparing quality, valuation, and cash generation across the 36 high quality undervalued stocks that rise to the top of your criteria.
- Stack your watchlist with differentiated opportunities by reviewing the 19 high quality undiscovered gems that combine strong financials with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com