
Murphy Oil (MUR) Climbed, But What Is Behind The Fresh Attention?
What Triggered Fresh Interest In Murphy Oil
Murphy Oil (MUR) is back in focus after a recent shift in analyst rankings and a higher earnings outlook, which is tied closely to progress in its offshore and Eagle Ford development work.
Recent momentum has been strong for Murphy Oil, with a 30 day share price return of 16.7% and a year to date share price gain of 35.27%. The 1 year total shareholder return of 65.32% points to interest that has been building rather than fading.
Scan 36 high quality undervalued stocks, hand picked for investors watching how Murphy Oil’s earnings upgrades and production plans intersect with value and balance sheet strength.
Murphy Oil has run hard on fresh earnings upgrades and project optimism, yet still screens as deeply undervalued on intrinsic metrics. Does that mix leave more upside for new buyers, or mostly execution risk from here?
Most Popular Narrative: 5% Overvalued
Murphy Oil last closed at $43.95, compared with a widely followed fair value narrative of $41.93 that uses a 7.24% discount rate. This points to a modest premium and puts execution of big offshore projects under the spotlight.
The main thing that has to go right is that higher capital spending, especially on Bubale appraisal and the Eagle Ford ramp, converts into commercially attractive offshore volumes without eroding the balance sheet or dividend capacity.
The current valuation implies that Murphy Oil is fairly valued, with the market already pricing in meaningful success from its long duration offshore growth projects and sustained free cash flow from onshore assets.
See why 15 investors see Murphy Oil as 5% overvalued.
Result: Fair Value of $41.93 (OVERVALUED)
Still, if higher US$1.55b capital spending fails to translate into attractive production or if Bubale well costs keep rising, Murphy Oil’s fair value story could quickly look stretched.
Find out about the key risks to this Murphy Oil narrative.
Another View: Murphy Oil On Earnings Multiples
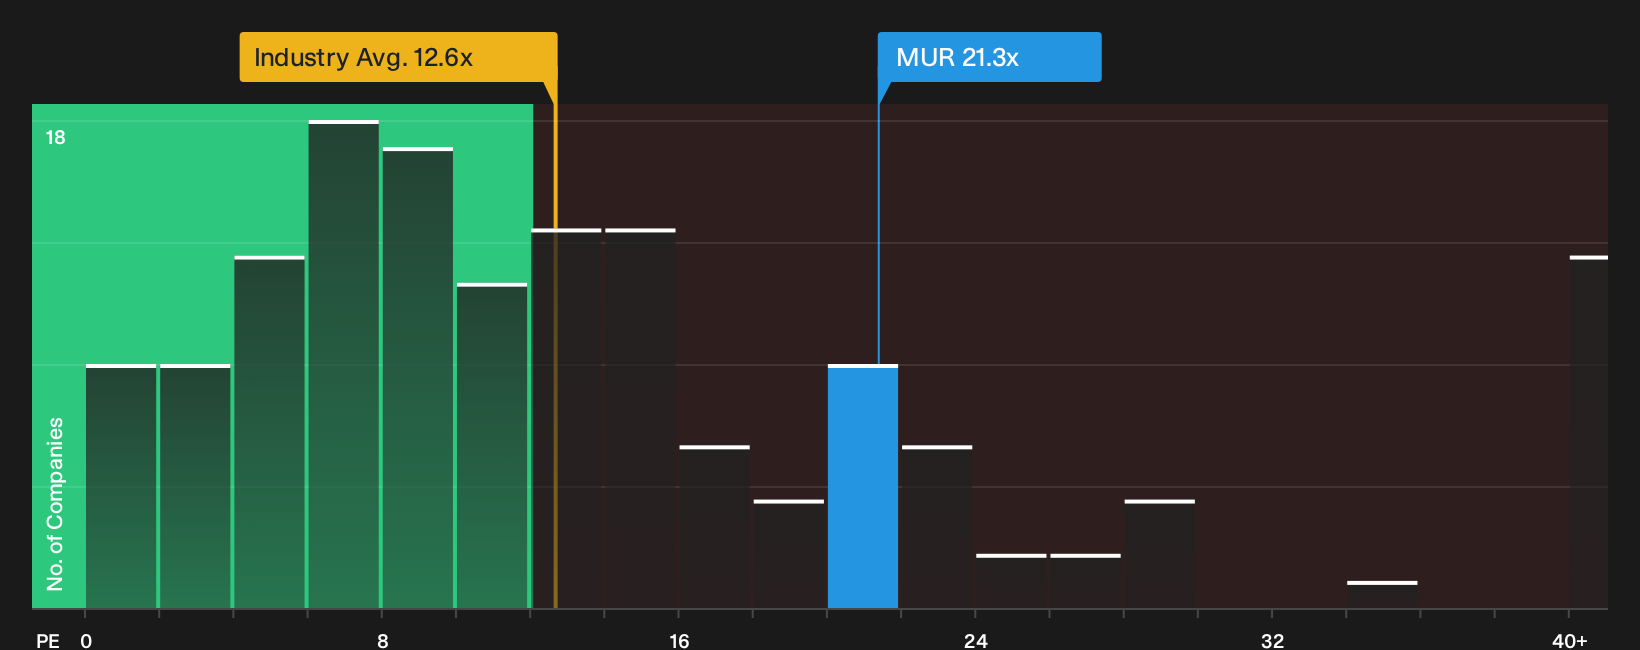
The picture shifts when you step away from fair value models and just look at what investors are paying for Murphy Oil’s earnings today. The shares trade on a P/E of 21.3x, compared with 12.6x for the wider US Oil and Gas group and 10.5x for close peers.
Simply Wall St’s fair ratio for Murphy Oil’s earnings multiple is 16.1x. The current P/E therefore sits well above the industry, the peer set and the level the ratio could move toward if expectations cool. Is that premium a justified price for future projects, or a margin of safety that has already been used up?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murphy Oil for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Murphy Oil so far and still feeling unsure. Act promptly to review the underlying data so you can weigh 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Murphy Oil?
Murphy Oil gives useful reference points, but your portfolio may also benefit from a broader range of candidates that can complement or challenge what this stock offers.
- Target potential mispricings by scanning a curated pool of quality companies that appear overlooked on fundamentals through the 19 high quality undiscovered gems.
- Focus on financial resilience by checking a list of solid balance sheet and fundamentals (24 results) that can handle shocks while still offering room for long term compounding.
- Manage portfolio risk by reviewing a 29 resilient stocks with low risk scores that filters for resilient businesses with lower risk scores baked into the process.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com