
Missed Sulzer's Run? Here's The Bet Holders Made
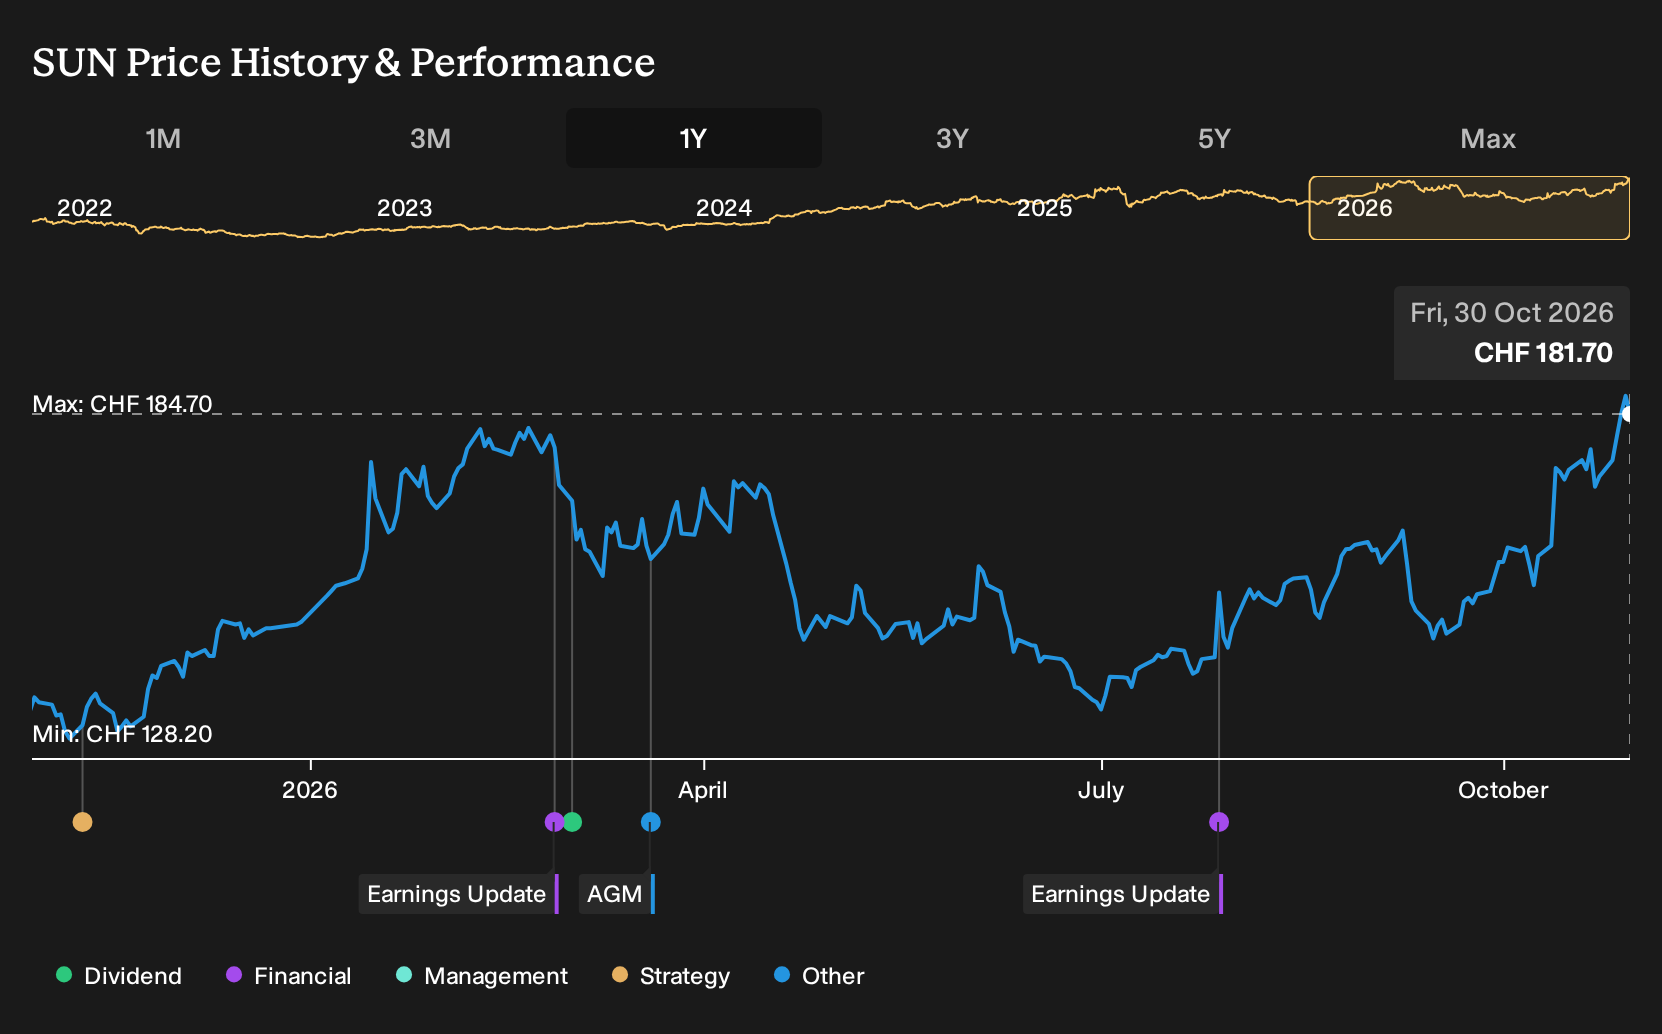
If you had only glanced at Sulzer’s mixed backdrop of tariff worries, Asian overcapacity and delayed projects, a smooth ride would have looked unlikely. Holding Sulzer over the past year would have returned 39.7%, including dividends. That outcome sits between bullish calls for recovery and bearish warnings about compressing refining margins. If both stories were on record at the start, what exactly did investors see in this industrial puzzle?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Sulzer has already moved. Pinpoint other ways to investigate the theme among 33 best rare earth metal stocks.
The Two Sulzer Stories Investors Were Weighing
The shares cost CHF135 at the start, and Sulzer sat between two sharply different stories that both sounded reasonable if you looked at the same set of facts.
The bullish narrative put fair value at CHF176, assuming revenue growth of 3.7%, a 9.8% profit margin and a future P/E of 17.4x, supported by demand for decarbonization and water treatment solutions.
The bearish view saw fair value at CHF89, focusing on Asian overcapacity in refining and petrochemicals and the risk that tariffs and regulatory costs would further squeeze refining margins.
What The Results Changed For Sulzer
Sulzer’s long term Corporate Procurement Agreement with Aramco supported the bullish case, since it underpinned demand for pumps and services in energy. The recycling facility deal for Vitol’s Western Polymer Unit reflected the decarbonization and environmental technology angle. Measured results pointed in a different direction. Revenue moved from CHF1,743.9m in H1 2025 to CHF1,672.6m in H1 2026, while net income and margin both rose, which left the overall picture mixed.
The useful lesson is clear. When a story hinges on higher quality earnings, focus on the trend in net income and margin, not just headline sales. For another industrial, test any “pivot to services and cleaner projects” claim against whether profit and net margin improve even if revenue softens.
What Sulzer’s Current Price Already Implies
Sulzer shares now trade at CHF182 after a 39.7% total return over the past year. The selected Narrative’s Fair Value sits below the current price, which reflects that Narrative’s judgement about what today’s valuation already builds in.
This Narrative highlights strong aftermarket exposure and margin work, while questioning how Chemtech volatility, working capital swings and cash generation interact with that story. For today’s price to hold, a buyer is effectively assuming Sulzer sustains high aftermarket driven profitability while Chemtech’s transition and large project timing do not undermine cash returns.
"Although Sulzer is benefiting from higher-margin aftermarket work that now represents 62% of sales and supports group EBITDA margins above 15%, the 3.9% decline in H1 2026 order intake and weak large-project demand suggest mix alone may not offset softer volume."
One Narrative disagrees with today's price. → See where this Narrative says Sulzer should trade
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 46% below our estimate - connects large online platforms to local pay-in networks and cash-out agents.
- Company 2 - 33% below our estimate - installs tracker devices and software linking equipment purchases to recurring monitoring revenue.
- Company 3 - 24% below our estimate - supplies automated testers as chip and AI server projects move to system-level qualification.
Three companies from the same screener. Open the full list of 200 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com