
How Mixed Q3 Results Will Impact Pediatrix Medical Group Stock
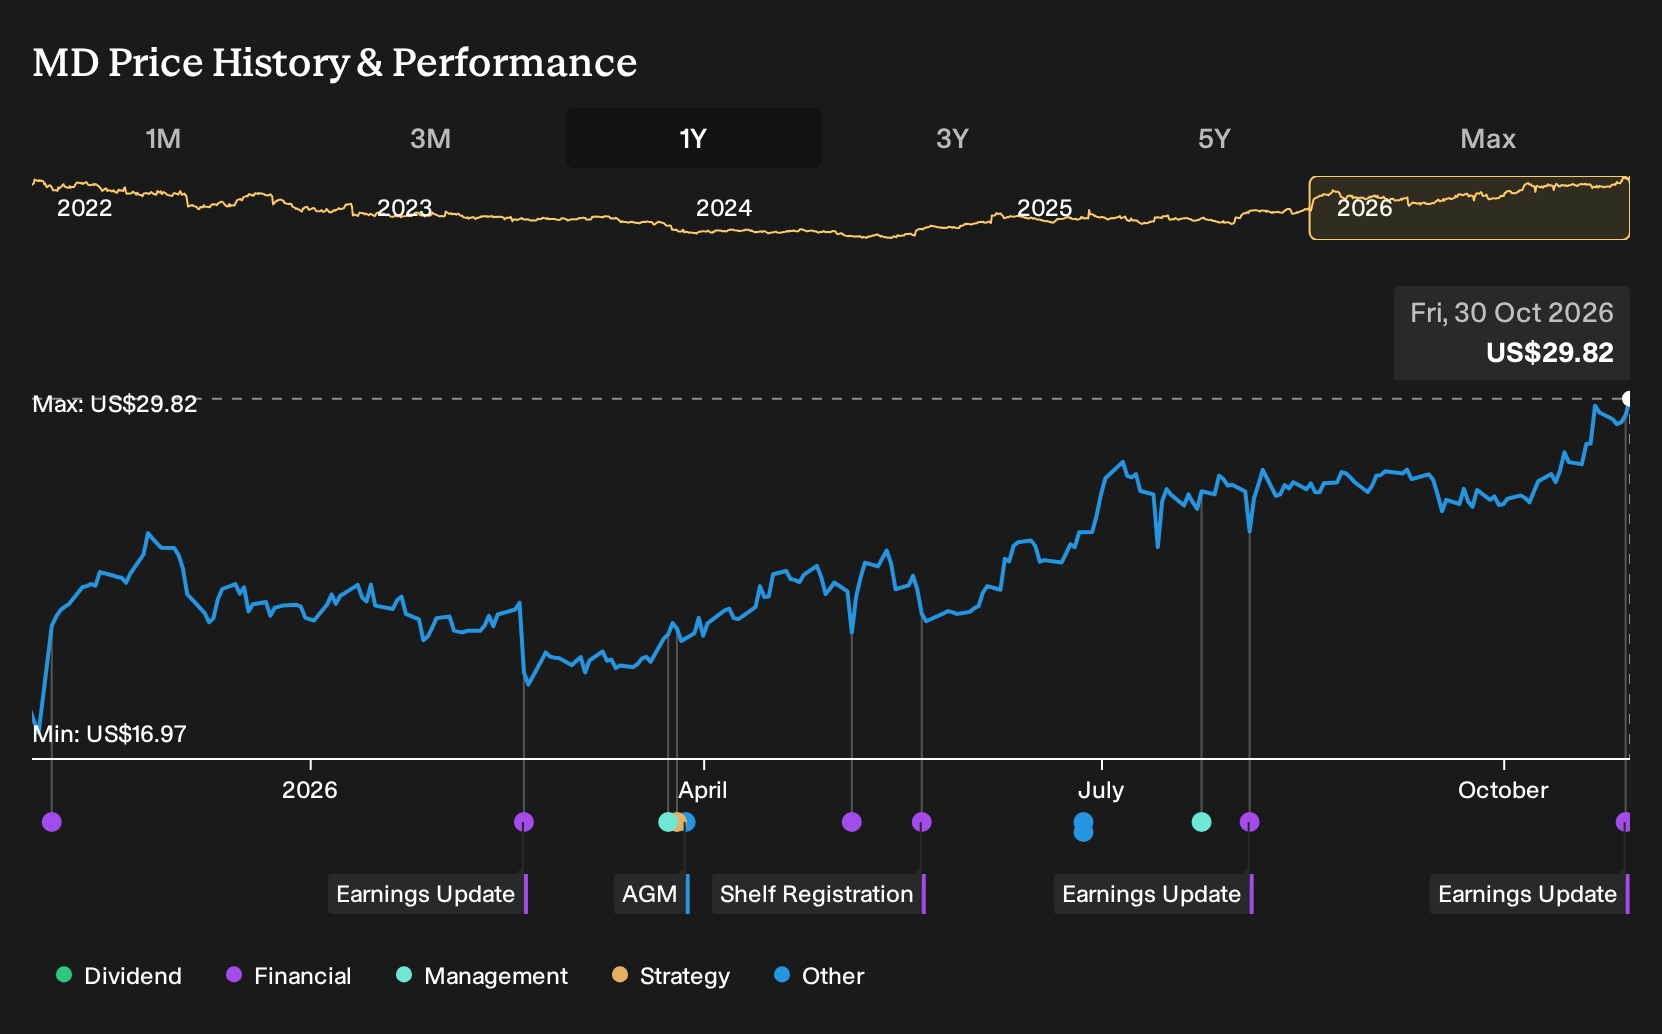
- Pediatrix Medical Group reported Q3 2026 results in late October, with sales of US$501.37 million and net income of US$46.99 million, and reaffirmed full year EBITDA guidance of US$290 million to US$300 million.
- Modest top line progress, alongside lower earnings and a focus on cost discipline, highlights how Pediatrix Medical Group is trading off revenue stability against squeezed profitability and cautious commentary on patient volumes and revenue cycle trends.
- We will now look at how Pediatrix Medical Group's investment narrative might shift, given lower Q3 earnings alongside maintained EBITDA guidance.
Scan how Pediatrix Medical Group’s margin pressure compares with peers by checking which healthcare providers on our hand picked list of solid balance sheet and fundamentals (24 results) are holding up better under similar revenue constraints.
Pediatrix Medical Group Investment Narrative Recap
To stay invested in Pediatrix Medical Group, you need to be comfortable with a story built on steady demand for neonatal and maternal care while margins stay under pressure. The recent Q3 report shows sales of US$501.37 million with net income of US$46.99 million, so the key short term catalyst remains execution on cost control and revenue cycle improvements rather than volume growth.
The biggest operational risk right now sits in reimbursement pressure, hospital fee negotiations and salary costs for clinicians. Lower earnings against a relatively firm top line keep that risk front and center. The latest quarter does not radically change that picture. However, it makes the margin question more urgent for anyone already holding the stock.
The most relevant update is the Q3 2026 earnings release, which kept full year EBITDA guidance at US$290 million to US$300 million while reporting weaker net income and EPS. For you, the signal is that Pediatrix Medical Group is trying to defend profitability through cost discipline and revenue cycle work rather than relying on stronger volumes.
That same announcement matters for catalysts because it ties operational execution directly to earnings quality. With portfolio restructuring, payer mix, reimbursement rules and clinician wage inflation all in play, the near term outcome hinges on how effectively the group manages collections, staffing costs and hospital contracts. Progress here would support the existing narrative, while any slip could quickly pressure both margins and investor confidence.
What The Current Forecasts Assume For Pediatrix Medical Group
Pediatrix Medical Group's narrative projects US$2.2b revenue and US$162.5 million earnings by 2029. This rests on 4.0% yearly revenue growth and an earnings increase of about US$12.4 million from US$150.1 million today.
Uncover why Pediatrix Medical Group's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Pediatrix Medical Group's telehybrid platform as the swing factor. Before this Q3 report, they were pencilling in revenue of about US$2.2b and earnings near US$188.7 million by 2029, compared with US$174.8 million in earlier estimates. You can treat this earnings miss as a reason to compare those upbeat assumptions with more cautious views, then decide which story feels more realistic to you.
Explore 4 other Pediatrix Medical Group fair value estimates, including one that suggests as much as 134% potential upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pediatrix Medical Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Pediatrix Medical Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pediatrix Medical Group's overall financial health at a glance.
Looking for more investment ideas beyond Pediatrix Medical Group?
Once you have formed a view on Pediatrix Medical Group, it can help to compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential upside with strict attention to balance sheet strength, start with our curated 19 high quality undiscovered gems that already show solid fundamentals.
- If resilience matters most to you during choppy periods, filter for companies on the 29 resilient stocks with low risk scores to focus on businesses with more stable financial profiles.
- Income focused investors can tilt their watchlist toward payouts by scanning through the 5 dividend fortresses that combine higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com