
A. O. Smith (AOS) Faces A 15% Fair Value Gap On China Exit And 2026 Reset
A. O. Smith (AOS) has put its China business on the chopping block while releasing third quarter results and fresh 2026 guidance that strips out that segment for the entire year.
The latest announcement follows a strong 30-day share price return of 11.14%, even though the year-to-date share price return is still down 7.68% and the 1-year total shareholder return is down 1.74%. This suggests momentum is building recently, despite weaker multi-year outcomes.
Compare A. O. Smith's refocused story with other industrials by scanning our hand picked list of solid balance sheet and fundamentals (24 results), which may handle portfolio risk differently from a business exiting a major market.
The recent jump in A. O. Smith shares could signal fresh conviction in a leaner, China-free footprint, or it could simply reflect a sentiment swing. How does that line up with where the valuation sits now?
Most Popular Narrative: 14.7% Overvalued
A. O. Smith last closed at $63.07, while the most followed narrative pegs fair value at $55. That gap frames how investors might judge the recent rally against a view that the shares already bake in plenty of optimism.
AOS manufactures water heaters and boilers in North America, with a secondary business in China that is in structural decline. The North American franchise is genuinely strong: three players control more than 90% of the market, the product is a non-discretionary emergency replacement in more than 80% of cases, and prices have risen above inflation for twelve consecutive years.
See why 3 investors see A. O. Smith as 15% overvalued.
Result: Fair Value of $55 (OVERVALUED)
Still, two pressure points could flip the A. O. Smith story quickly: how the 2029 heat pump mandate reshapes its moat, and whether the China exit drags on or cleans up earnings.
Find out about the key risks to this A. O. Smith narrative.
Another View: A. O. Smith Through Earnings Multiples
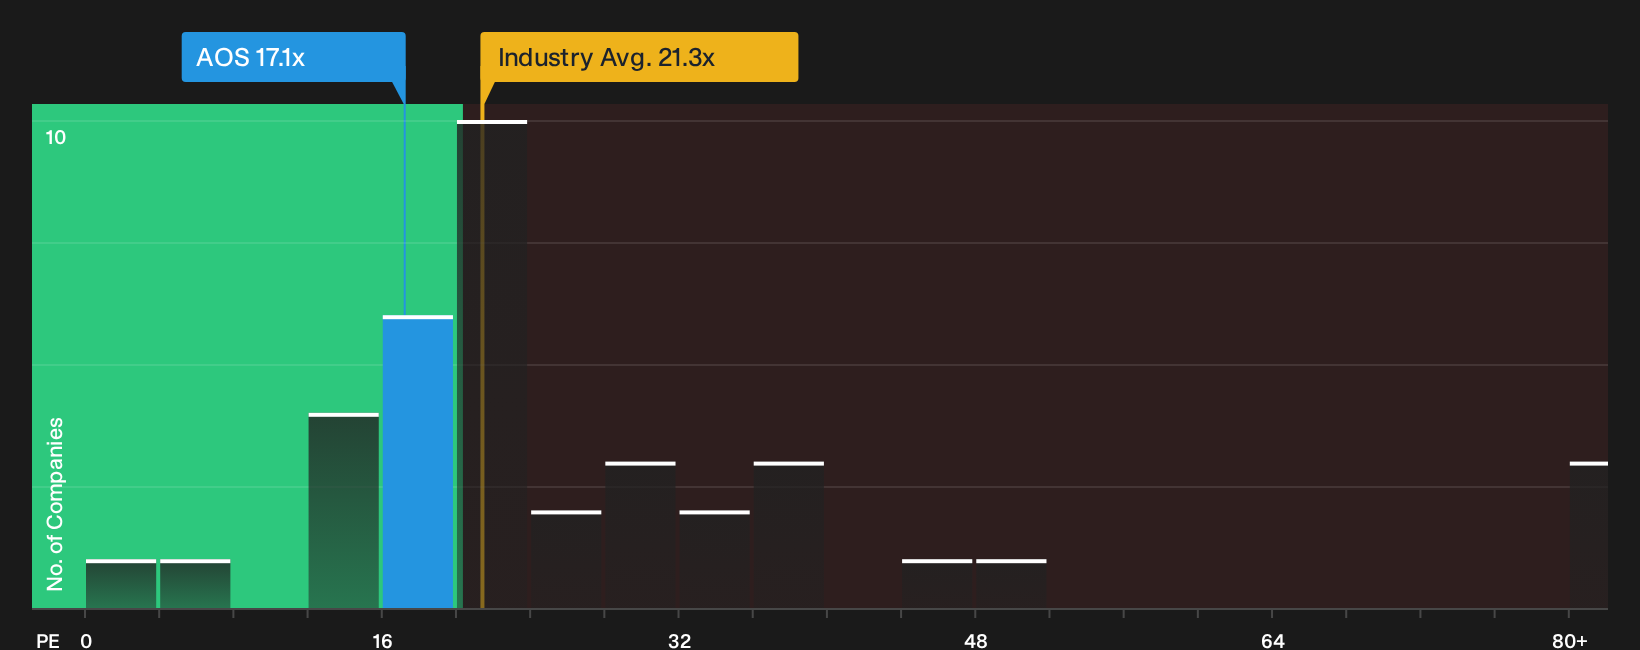
The user narrative sees A. O. Smith as roughly 14.7% overvalued versus a $55 fair value. Our valuation checks tell a different story. At a P/E of 17.1x against a US Building industry average of 21.3x and a peer average of 37.6x, the stock screens as relatively attractive on this metric.
The fair ratio points to 19.2x as a level the market might move toward, which would suggest less valuation risk than the narrative indicates. Which signal do you rely on more: the crowd narrative or the comparative multiples.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment on A. O. Smith leaves you unsure, consider promptly stress testing the assumptions that matter most for your portfolio and reviewing the 4 key rewards
Looking for more A. O. Smith sized investment ideas?
Do not stop with A. O. Smith. Put fresh ideas on your radar now using targeted stock lists that match different risk and return preferences.
- Target value opportunities by scanning companies that screen as attractively priced on fundamentals using our 36 high quality undervalued stocks.
- Prioritise resilience by reviewing a 29 resilient stocks with low risk scores that may help steady your portfolio when individual positions move around.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems with solid financial profiles that fewer investors are watching closely.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com