
Datadog (DDOG) Stock Looks Reasonable Based On Its Cash Flow Outlook
Datadog has seen sharp swings in recent weeks after a multi year climb. That puts fresh attention on a simple question for investors looking at the stock today: Are the cash flows the business can generate over time enough to support the current share price near US$235?
- Over the past 3 years the stock has gained 195.8%, so a lot of future cash generation is already embedded in expectations and becomes critical to assess.
- Recognition as a leader in AIOps platforms and continued investment in AI driven products can influence assumptions about how quickly Datadog converts that growth opportunity into durable cash flows.
- If you'd rather focus on sales, this one's for you. See why Datadog's 21.3x P/S tells a different valuation story.
The issue now is whether Datadog's current market value is aligned with what its cash flows suggest when run through a Discounted Cash Flow (DCF) lens.
If Datadog's recent swings have you rethinking exposure to AI infrastructure, consider using a focused stock screen built around 54 AI infrastructure stocks.
Is Datadog a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model used here projects what Datadog might return to shareholders based on its future free cash generation. Latest twelve month free cash flow is about $1.08b, and the forecast path assumes that this figure increases over time rather than shrinking, with projected annual free cash flows reaching multiple billions of dollars within the next decade.
Because the DCF projections put Datadog's estimated intrinsic value meaningfully above the current share price of $235.27, the model suggests that the market is not fully pricing in those projected cash flows. The recent recognition as a Leader in AIOps platforms, with high scores for areas such as innovation and AI governance, helps explain why long term forecasts incorporate higher free cash flow projections even if the stock price has already risen. You can see how that gap between cash flows and market price looks in detail via the full model output. Find out what Datadog could be worth using our Discounted Cash Flow (DCF) estimate.
The Datadog Narrative: What Would Justify Today's Price?
Narratives pick up where the DCF puzzle leaves off for Datadog by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than it is today. These narratives sit on Simply Wall St's Community page. Each scenario links its number to a clear view on how Datadog's growth, margins and risk profile might evolve, which you can revisit as fresh information comes through.
Community views on Datadog are split between AI deepening the moat and AI optimization capping how far the story can run.
Bull case: 20% undervalued
"Expanding AI workloads, with over 750 AI customers including all 10 of the top AI leaders and growing use cases such as GPU monitoring, Agent Observability, AI Guard and Bits AI, can support higher observability and security spend per customer and feed Datadog revenue growth over time…"
Discover why this Narrative puts Datadog at 20% undervalued.
Bear case: 6% overvalued
"Although Datadog is seeing strong interest from AI focused customers, the disclosed usage reduction from its largest AI client following renewal of a nine figure contract shows how quickly AI workloads can be optimized, which could limit future AI related telemetry growth and constrain revenue and gross margin expansion from this cohort…"
Explore why this Narrative puts Datadog at 6% overvalued.
The Datadog story has one more unanswered question
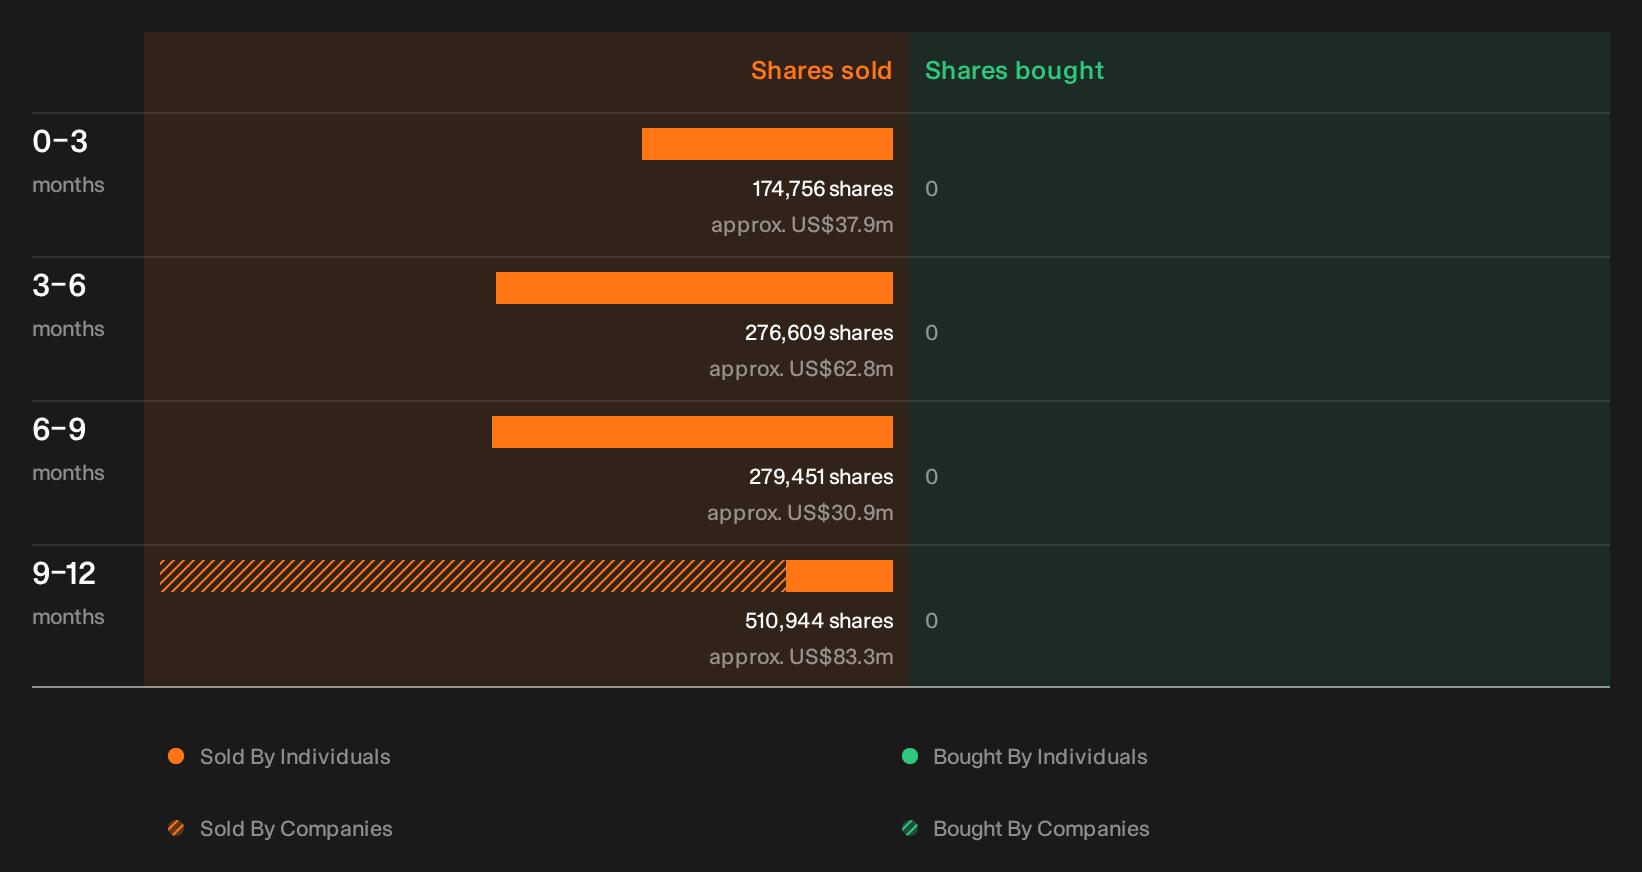
Valuation work sketches one picture of Datadog, but our checks have also picked up recent trades by people inside the business, and the who, how much and what it might signal are all still for you to review. See the recent insider selling flagged for Datadog.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com