
Boeing (BA) Could Be 54% Below Fair Value After Weak Results And Guidance Cut
Boeing (BA) is back in focus after third quarter results fell short of expectations, with a reported loss, reduced free cash flow guidance, and fresh delays to planned 737 MAX production increases weighing on sentiment.
That earnings miss landed on a stock that was already under pressure, with the share price down 27.66% over the past 90 days and 24.68% year to date, while the 1 year total shareholder return has declined 16.13%. This points to fading momentum as investors reassess Boeing’s production risks, revised free cash flow outlook, and the balance between setbacks and positives such as 737-10 certification and new digital products.
Scan beyond Boeing's setback and review other industrials that currently screen as 36 high quality undervalued stocks based on quality and balance sheet strength.
Boeing still has a deep backlog, new 737-10 approval, and fresh digital products, yet the share price has reset hard. Is this a strong franchise temporarily marked down or fairly reflecting the risk now in the story?
Most Popular Narrative: 7.2% Overvalued
Boeing closed at $171.55 against a narrative fair value of $160.01. This frames the stock as slightly ahead of that long term thesis and puts more weight on execution risk than on the recent price slide alone.
The operating recovery is real but incomplete. Commercial Airplanes narrowed its operating margin from negative 5.1% to negative 2.7% on 171 deliveries against 150. The 737 is transitioning to 47 per month from 38 a year ago, with a fourth Everett line activated in July, and management targets 52 next year. The FAA certified the MAX 7 today after nearly a decade, with roughly 30 airframes in storage ready for retrofit.
See why 9 investors see Boeing as 7% overvalued.
Result: Fair Value of $160.01 (OVERVALUED)
Still, this hinges on Boeing avoiding another large programme charge and keeping 737 production and certification milestones on track; any stumble could quickly rewrite the story.
Find out about the key risks to this Boeing narrative.
Another View On Boeing's Value
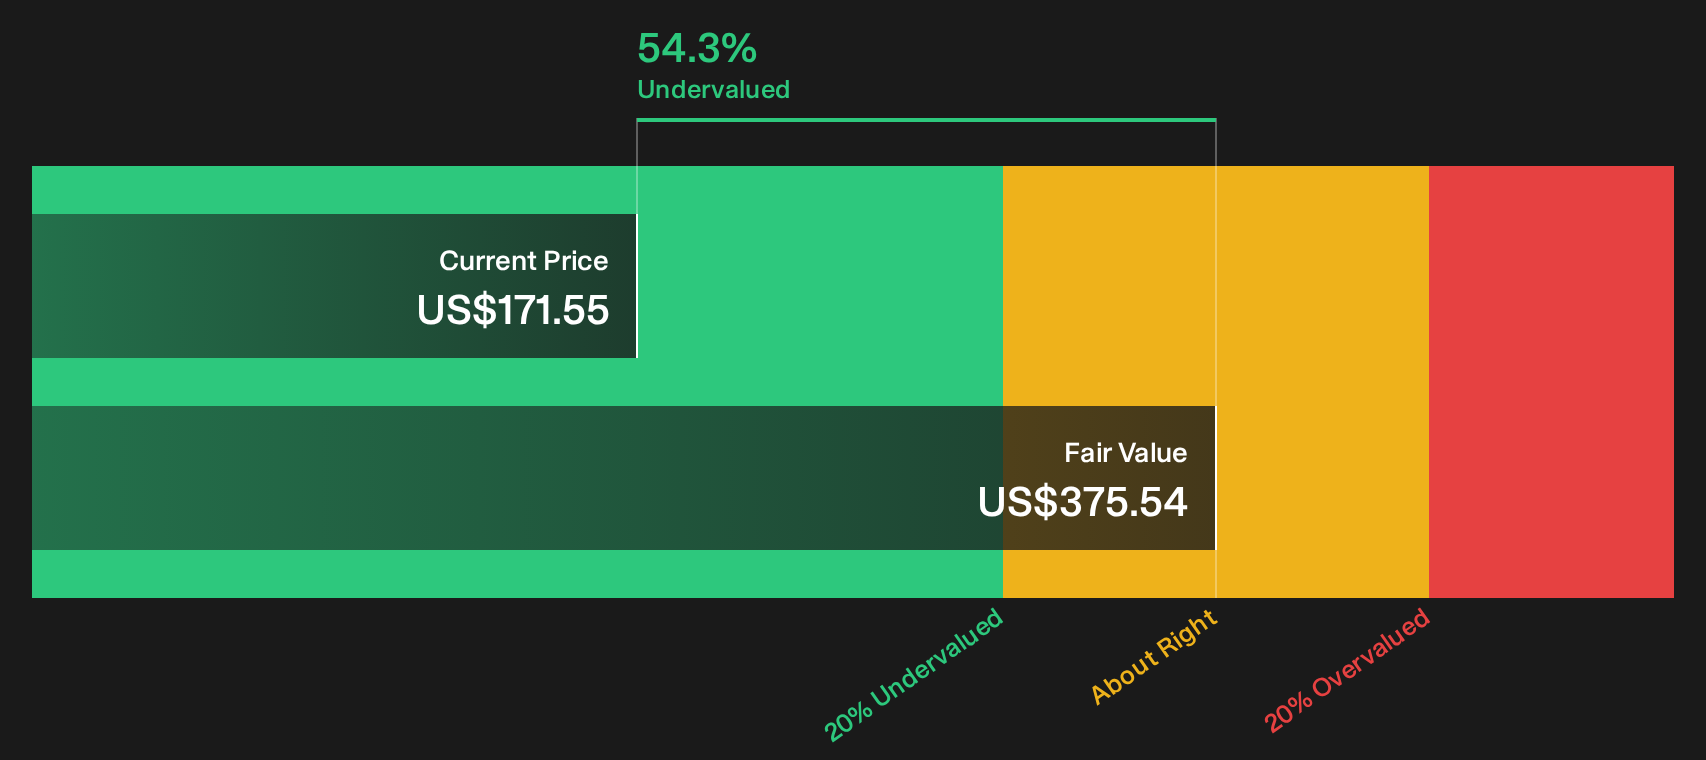
That narrative fair value of $160.01 frames Boeing as 7.2% overvalued, yet the SWS DCF model paints a very different picture. On that cash flow view, Boeing at $171.55 is described as trading 54.3% below its estimated future cash flow value of $375.54, which suggests the story looks very different if you focus on long term cash generation.
For readers who want to see how those cash flows are built up line by line, the next step is to look under the hood of the SWS DCF model: Look into how the SWS DCF model arrives at its fair value.
Next Steps
Conflicted about whether Boeing's setback-filled story points to risk or opportunity right now? Act quickly, check the details for yourself, and weigh both sides by reviewing the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Boeing?
If Boeing's recent reset has you reassessing your watchlist, this is the moment to widen your lens and line up your next set of possibilities.
- Target potential mispricing by scanning for quality companies trading at marked down valuations through the 36 high quality undervalued stocks.
- Prioritise resilience first and returns second by filtering for businesses that pass a tough financial strength check with the list of solid balance sheet and fundamentals (24 results).
- Hunt for lesser known opportunities before the crowd pays attention by reviewing the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com