
Is EVERTEC (EVTC) Fully Valued On Its Reaffirmed Dividend And Recent Rally?
EVERTEC (EVTC) reaffirmed its regular cash dividend, with the Board declaring a quarterly payout of $0.05 per share, scheduled for December 4, 2026, for investors of record as of November 9.
The reaffirmed dividend comes as EVERTEC’s share price shows building momentum, with a 1-month share price return of 15.83% and a year-to-date gain of 9.97%, although the 5-year total shareholder return remains down 26.28%.
Compare EVERTEC’s renewed dividend signal with a curated group of resilient income payers and balance sheet standouts by scanning the list of solid balance sheet and fundamentals (24 results) alongside this update.
EVERTEC has a long-established payments franchise and fresh share price momentum. The real tension for investors now is simple. Does that solid operational story still come at a reasonable valuation after the recent jump?
Most Popular Narrative: 11% Undervalued
EVERTEC’s most followed thesis points to a fair value of $35.60 compared with the recent $31.54 close. This helps put the current rally in context and links the dividend decision to a broader earnings and cash flow story.
Ongoing Latin America expansion through acquisitions such as Sinqia, Dimensa, Tecnobank and BBChain, combined with large processing contracts including Transbank in Chile and Clip in Mexico, is expected to shift more of EVERTEC’s revenue mix toward higher growth markets and support earnings over the next several years.
Growth in Puerto Rico Merchant Acquiring and Payment Services, with recent single digit to low double digit increases in revenue supported by higher sales volumes, transaction growth and pricing initiatives, provides a recurring cash flow base that can help fund investment while supporting overall EBITDA and free cash flow.
See why 2 investors see EVERTEC as 11% undervalued.
Result: Fair Value of $35.60 (UNDERVALUED)
Still, EVERTEC’s case can weaken quickly if Popular contract revenue keeps slipping or if another cybersecurity issue dents client confidence and raises costs.
Find out about the key risks to this EVERTEC narrative.
Another View on EVERTEC’s Valuation
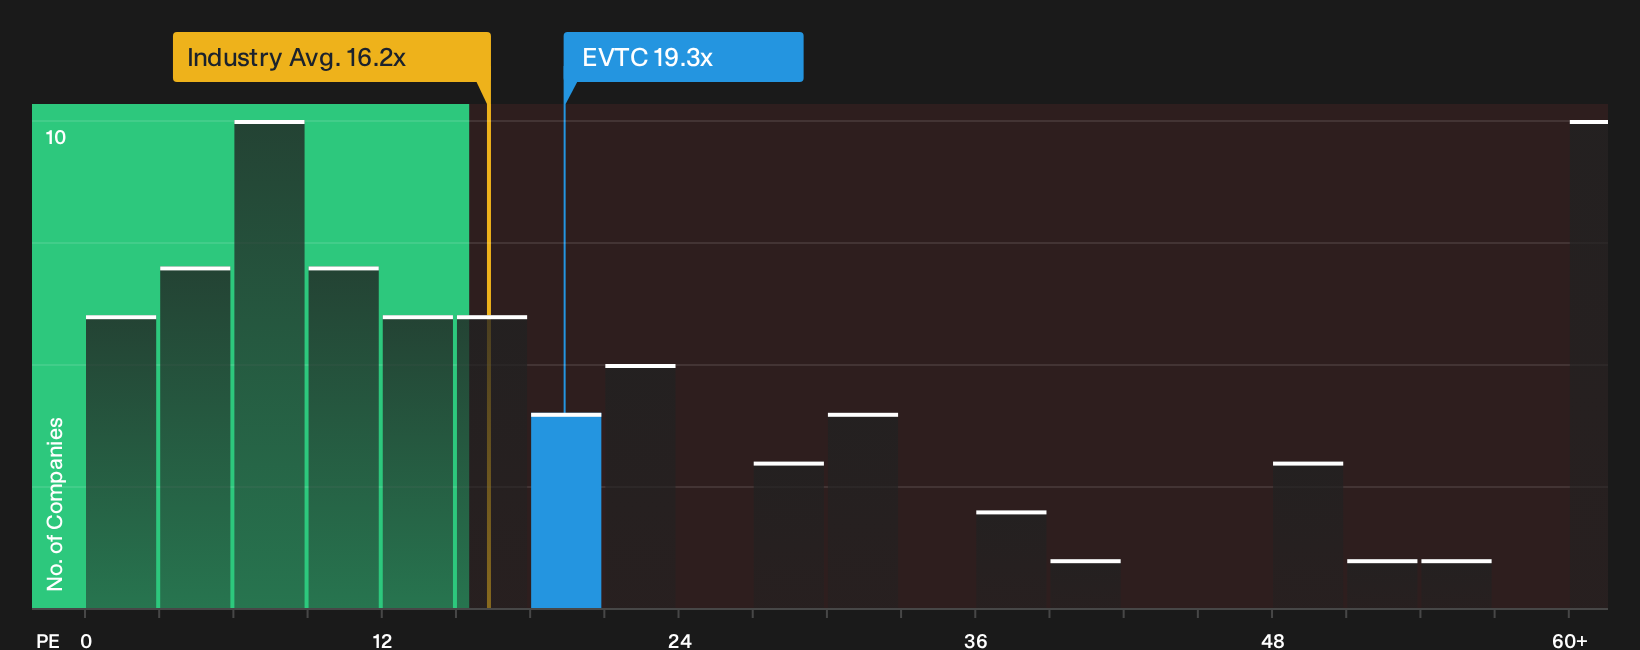
The first narrative framed EVERTEC as undervalued based on a fair value of $35.60. A simple P/E check tells a different story. EVTC trades at 19.3x earnings compared with 16.2x for both peers and the wider US diversified financial industry, and a fair ratio of 15.7x. That premium points to less of a clear bargain and more of a pricing debate. Which signal do you trust more when you look at your own assumptions?
For a closer look at how that earnings multiple stacks up and what it could mean if the market leans back toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on EVERTEC’s value and risk profile are clear, so move quickly to review the underlying data and pressure test your own thesis with 2 key rewards and 3 important warning signs
Looking for more EVERTEC-sized investment ideas?
If you stop with EVERTEC, you risk missing other opportunities that fit your style, so put the Simply Wall Street Screener to work across the market.
- Target steadier potential returns by checking out companies that appear built to weather shocks through the 29 resilient stocks with low risk scores.
- Hunt for possible mispriced opportunities by reviewing the 19 high quality undiscovered gems before other investors catch on.
- Strengthen your income and capital preservation mix by scanning the 5 dividend fortresses that may complement or contrast with EVERTEC in your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com