
When Will Skeena Resources Limited (TSE:SKE) Turn A Profit?
Skeena Resources Limited (TSE:SKE) is possibly approaching a major achievement in its business, so we would like to shine some light on the company. Skeena Resources Limited engages in the exploration and development of mineral properties in Canada. With the latest financial year loss of CA$183m and a trailing-twelve-month loss of CA$248m, the CA$4.7b market-cap company amplified its loss by moving further away from its breakeven target. Many investors are wondering about the rate at which Skeena Resources will turn a profit, with the big question being “when will the company breakeven?” In this article, we will touch on the expectations for the company's growth and when analysts expect it to become profitable.
Skeena Resources is bordering on breakeven, according to the 3 Canadian Metals and Mining analysts. They expect the company to post a final loss in 2026, before turning a profit of CA$347m in 2027. So, the company is predicted to breakeven just over a year from today. How fast will the company have to grow each year in order to reach the breakeven point by 2027? Working backwards from analyst estimates, it turns out that they expect the company to grow 86% year-on-year, on average, which signals high confidence from analysts. If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
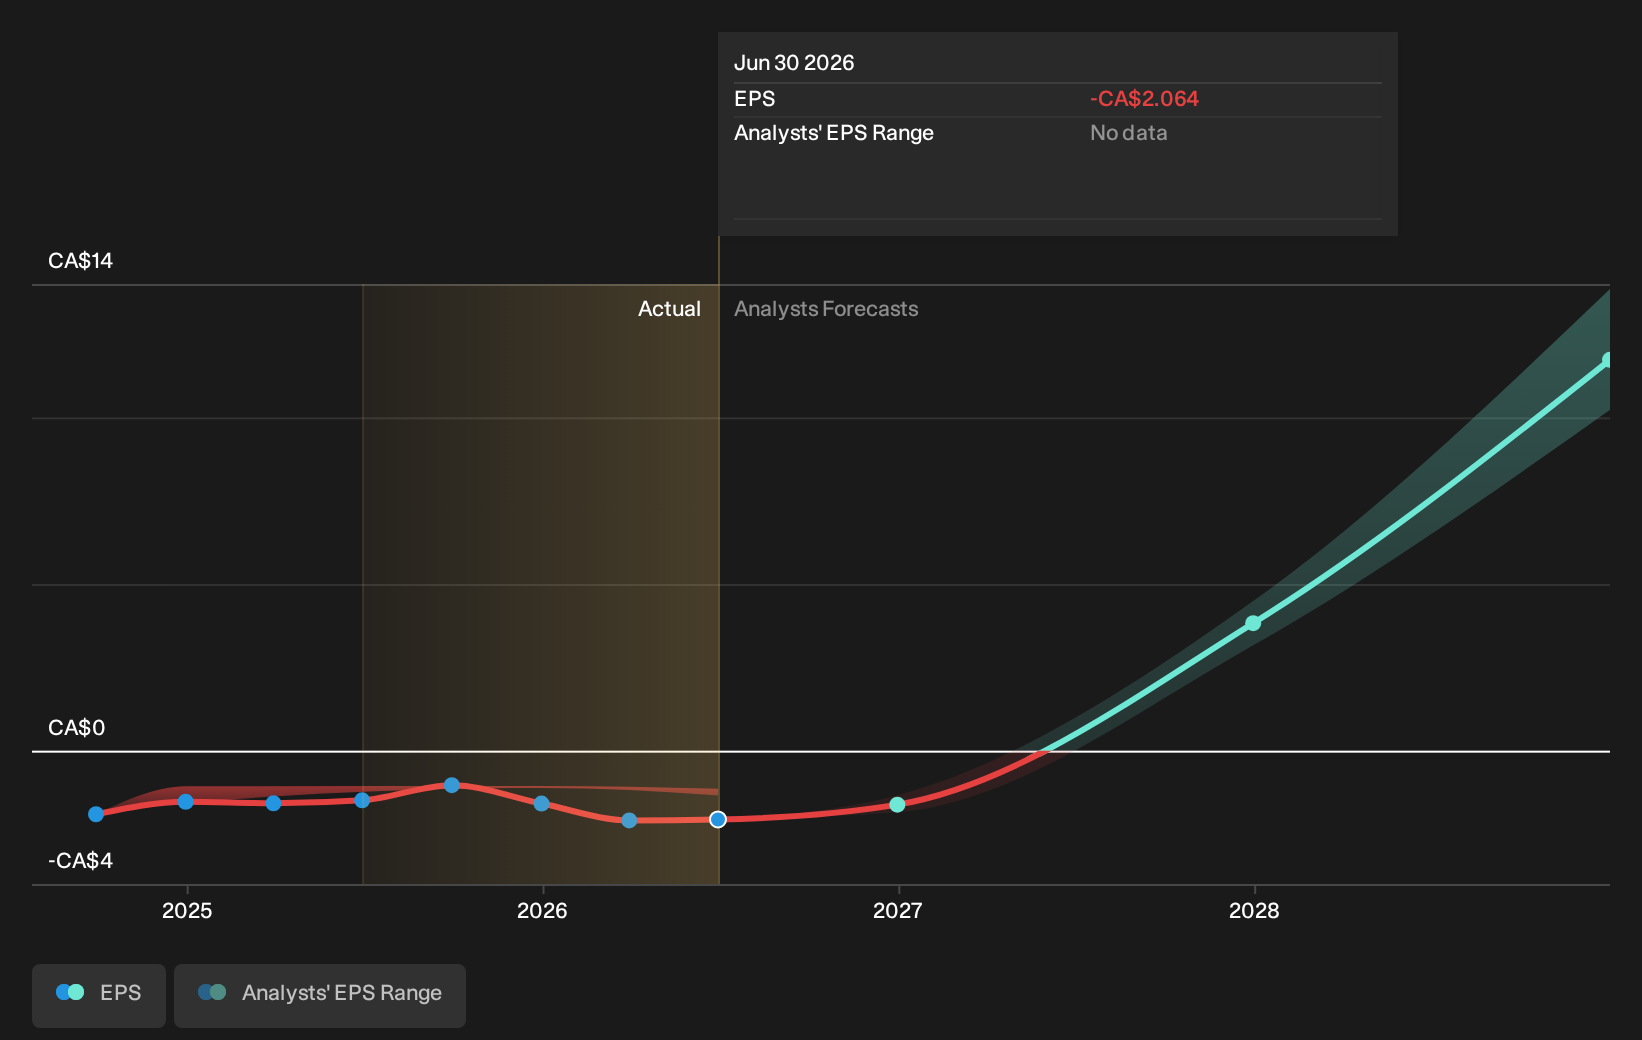
We're not going to go through company-specific developments for Skeena Resources given that this is a high-level summary, however, keep in mind that by and large metals and mining companies, depending on the stage of operation and metals mined, have irregular periods of cash flow. So, a high growth rate is not out of the ordinary, particularly when a company is in a period of investment.
See our latest analysis for Skeena Resources
One thing we would like to bring into light with Skeena Resources is its debt-to-equity ratio of over 2x. Generally, the rule of thumb is debt shouldn’t exceed 40% of your equity, and the company has considerably exceeded this. Note that a higher debt obligation increases the risk around investing in the loss-making company.
Next Steps:
There are key fundamentals of Skeena Resources which are not covered in this article, but we must stress again that this is merely a basic overview. For a more comprehensive look at Skeena Resources, take a look at Skeena Resources' company page on Simply Wall St. We've also compiled a list of important factors you should further research:
- Valuation: What is Skeena Resources worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether Skeena Resources is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Skeena Resources’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.