
Permian Basin Royalty Trust (PBT) Shares Dropped, So What Is Behind The Latest Attention?
Permian Basin Royalty Trust (PBT) is back in focus after the trustee declared a higher monthly cash distribution of $0.045191 per unit, tied to a final settlement payment and stronger Texas natural gas metrics.
The higher payout comes just as Permian Basin Royalty Trust trades at $31.62, after the share price slipped 2.6% over the last session and declined 5.9% across the past week. It still carries a strong year-to-date share price return of 79.8% and a five-year total shareholder return above 3x that level, which indicates notable long-term momentum even as short-term sentiment cools around the latest distribution news.
Look beyond Permian Basin Royalty Trust's latest cash distribution and compare it with other income ideas that feature strong balance sheets and fundamentals in our curated list of solid balance sheet and fundamentals (24 results)
After a long run and a recent pullback around the latest distribution, Permian Basin Royalty Trust raises a simple question: Does the current price still compensate you for the risks on future cash flows?
Price-to-Earnings of 91x: Is it justified?
On simple valuation math, Permian Basin Royalty Trust looks expensive. The units changed hands at $31.62 at the last close while the preferred metric, the P/E ratio, sits at 91x, far above both the US Oil and Gas industry and its peer group.
The P/E multiple compares what investors pay for each dollar of earnings. For a royalty trust like Permian Basin Royalty Trust, where reported profits tie closely to commodity royalties rather than large reinvestment plans, a very high P/E can suggest the market is paying a steep price for access to current and potential future distributions.
Compared with the wider US Oil and Gas industry average of 12.6x and a similar 12.6x figure across its peers, a 91x P/E is far higher. That kind of gap signals the market is pricing Permian Basin Royalty Trust at a substantial premium to sector earnings, which leaves less room for error if royalty income or payouts soften from here.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 91x (OVERVALUED)
The SWS DCF model points in the same direction. Permian Basin Royalty Trust is trading at $31.62, while the model’s estimate of future cash flow value stands at $7.98 per unit, which implies a much lower value than the current market price.
That DCF framework projects future cash flows attributable to unitholders and discounts them back to today using a required return, so the further those distributions are in the future or the more volatile they are, the heavier the discount. For a royalty trust tied to oil and gas properties, the pattern and durability of production plus commodity price swings can have a major influence on that stream.
Given Permian Basin Royalty Trust’s structure and exposure to Texas oil and gas royalties, this gap between $31.62 and the $7.98 DCF estimate highlights how much of today’s price leans on investor confidence in sustained payouts that extend beyond what this model assumes.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of $7.98 (OVERVALUED)
Still, the story behind Permian Basin Royalty Trust can change quickly if Texas production volumes weaken or commodity prices move against current cash flow assumptions.
Find out about the key risks to this Permian Basin Royalty Trust narrative.
Another View on Permian Basin Royalty Trust's Rich Valuation
One more signal points the same way. The SWS DCF model puts Permian Basin Royalty Trust’s fair value at $7.98 per unit, well below the current $31.62 price. This suggests the units are priced richly and leaves you asking how much payout strength you need to feel comfortable holding that gap.
Look into how the SWS DCF model arrives at its fair value.
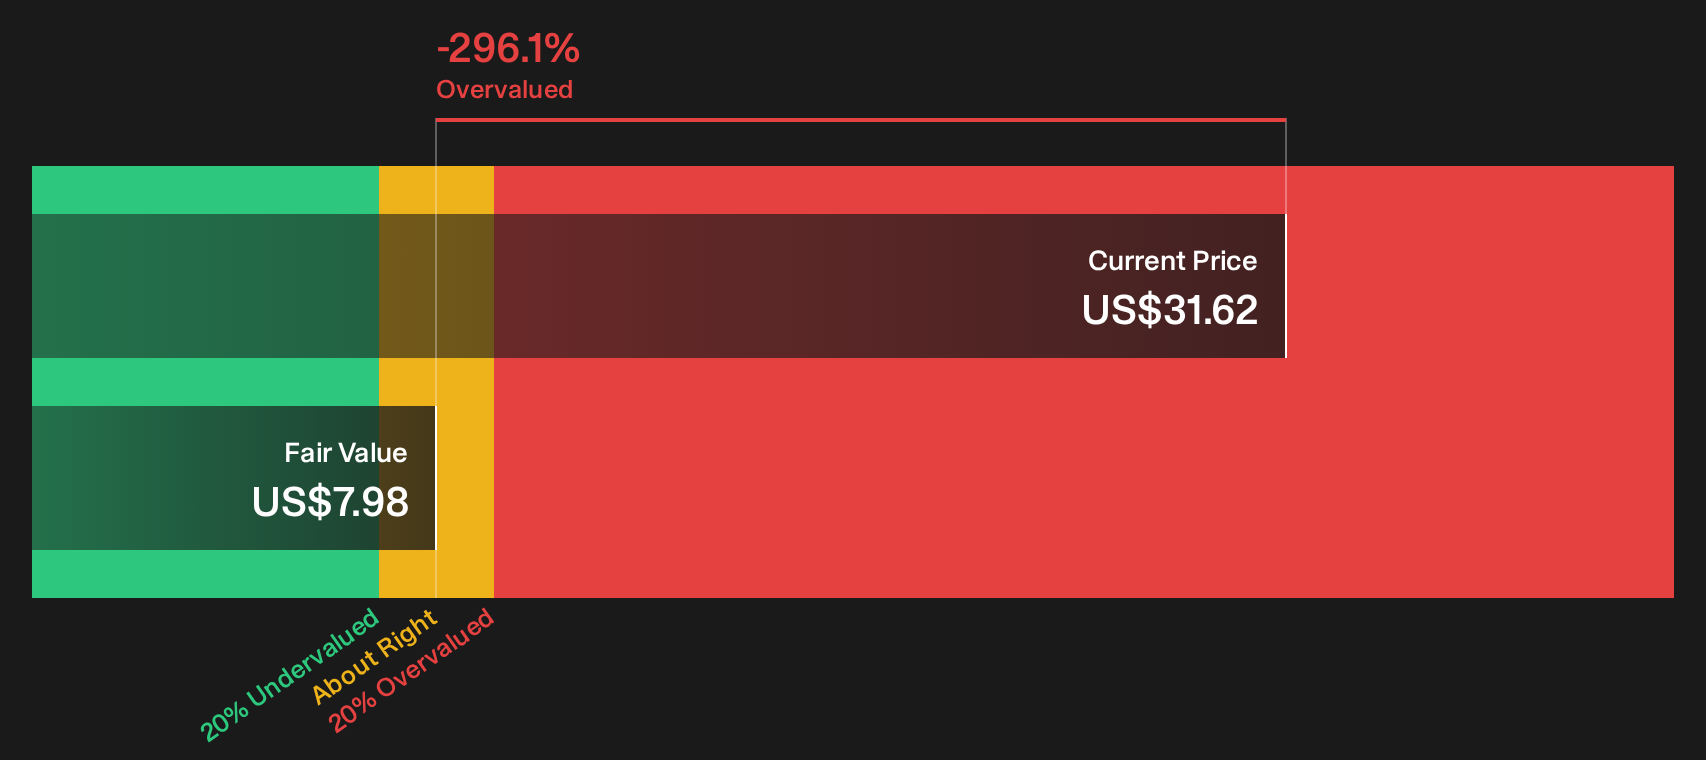
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Permian Basin Royalty Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this all feels heavily skewed to caution, that is the point. Your call on Permian Basin Royalty Trust should rest on your own read of the numbers, disclosures, and risk flags such as the 1 important warning sign
Looking for more investment ideas beyond Permian Basin Royalty Trust?
Do not stop at a single royalty trust when you can scan a broader field of opportunities quickly using the Simply Wall St Screener.
- Target potential mispricing by reviewing companies that screen as 36 high quality undervalued stocks and see which fundamentals line up with your own return expectations.
- Focus on resilience and capital preservation by checking out a 29 resilient stocks with low risk scores that highlights businesses with lower overall risk scores.
- Hunt for tomorrow's potential standouts early by filtering through a curated 19 high quality undiscovered gems before more investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com