
Is Cavco Industries (CVCO) Getting Expensive After Strong Earnings?
Cavco Industries has delivered a striking share price run in recent years, and the latest earnings update adds even more focus to what investors are paying for its profit stream. With the stock recently closing at US$619.00, the central question is how well that market value lines up with what the business earns today.
- Over the past 3 years Cavco Industries has returned 138.9%, which puts a lot of past enthusiasm on the line when you test the price against its earnings power.
- Fresh earnings results with higher revenue and a growing order backlog may support expectations for future profit, while the one time insurance refund raises the issue of how much of the recent strength reflects repeatable earnings.
- Your read on Cavco Industries is one view; the desks covering it have another. See what analysts think Cavco Industries's shares could be worth.
The stock's next move may depend on whether Cavco Industries' current share price can be explained by its earnings when set against a Fair Ratio benchmark.
If you want more context around Cavco Industries' run and its latest earnings story, compare it with 36 high quality undervalued stocks that also meet a similar quality standard.
Is Cavco Industries Getting Expensive on Earnings?
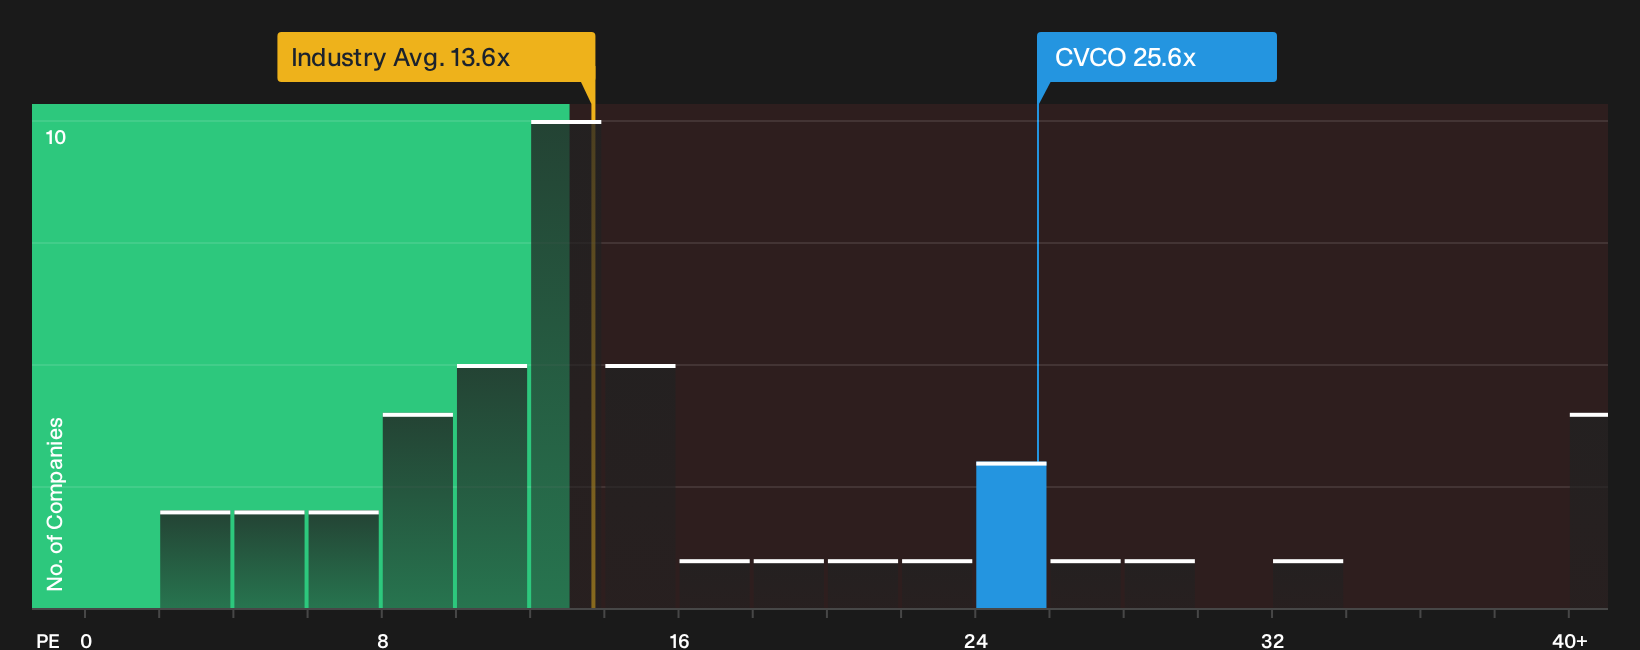
Cavco Industries is usually judged on a P/E basis because profit is a key focus for a housing manufacturer with meaningful earnings on the board. The current P/E sits around 25.6x, which is higher than both the Consumer Durables sector average of about 13.6x and a peer group around 18.0x. As a result, the shares change hands at a richer earnings tag than many close comparables.
The Fair Ratio model, which adjusts for factors like the firm’s margins, scale, industry and risk profile, points to a lower P/E than where Cavco Industries trades today. This indicates that the stock prices in a premium to what that framework implies. Despite the latest quarter showing record revenue and a larger backlog after the fiscal Q2 2027 update, the current earnings multiple already reflects a lot of that optimism relative to the benchmark Fair Ratio. Explore the numbers behind Cavco Industries's P/E valuation.
The Cavco Industries Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Cavco Industries pick up where this valuation puzzle leaves off, by spelling out which paths for growth, profitability and earnings would need to play out for the shares to look meaningfully higher or lower than today’s price. Each scenario links its number to a clear view on how Cavco Industries' growth, margins and risk profile might evolve, giving you something concrete to revisit as new results and data points come through on the Community page.
One of the top community narratives on Cavco Industries: 7% undervalued
"The main thing that has to go right is Cavco Industries converting strong order momentum, capacity additions, and cost synergies into healthier margins..."
Discover why this Narrative puts Cavco Industries at 7% undervalued.
Cavco Industries' price is only half the story
For Cavco Industries, the next question is who is steering the business and how their incentives line up with your interests, because that can shape what the current valuation really means. See who runs Cavco Industries and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com