
Paylocity Holding (PCTY) Launches Recruiting Optimizer, Is A 4% Undervalued View Enough?
Paylocity Holding (PCTY) rolled out Recruiting Optimizer, an AI-powered extension of its recruiting suite that embeds configurable agents into talent workflows, automating sourcing, engagement, screening, and scheduling while keeping hiring decisions with human recruiters.
Despite a softer 7 day share price return of down 3.15%, Paylocity Holding has recorded a 30 day share price gain of 18.30% and a 90 day share price return of 19.25%, pointing to building momentum around AI driven products like Recruiting Optimizer. Meanwhile, the 1 year total shareholder return of 21.38% contrasts with a weaker 5 year total shareholder return, which is down 37.74%.
Scan AI-focused HR and automation peers that are moving on similar catalysts with a curated list of 41 profitable AI stocks that aren't just burning cash that already combine real revenue with disciplined spending.
After a sharp short term rebound and a longer term drawdown, Paylocity Holding now sits at a valuation that implies a fresh call for investors. The key question is whether the current price still leaves enough potential upside to justify the risk.
Most Popular Narrative: 4% Undervalued
Paylocity Holding last closed at $170.91, while the most followed narrative pegs fair value at $178.85, leaving a modest valuation gap that hinges heavily on how AI usage and newer modules convert into durable earnings power.
Expansion of Paylocity Holding’s unified HR, finance and IT platform with embedded AI agents such as Ignite AI and the AI assistant, along with planned premium SKUs tied to tools like Grayscale and Aidora, is expected to convert rising AI usage into higher recurring revenue and average revenue per client over time, which may support earnings.
See why 11 investors see Paylocity Holding as 4% undervalued.
Result: Fair Value of $178.85 (UNDERVALUED)
Still, if Paylocity Holding delivers only mid single digit sales growth or AI modules see slower adoption, the current underappreciated narrative could quickly lose traction.
Find out about the key risks to this Paylocity Holding narrative.
Another View: Paylocity Holding Looks Expensive On Earnings
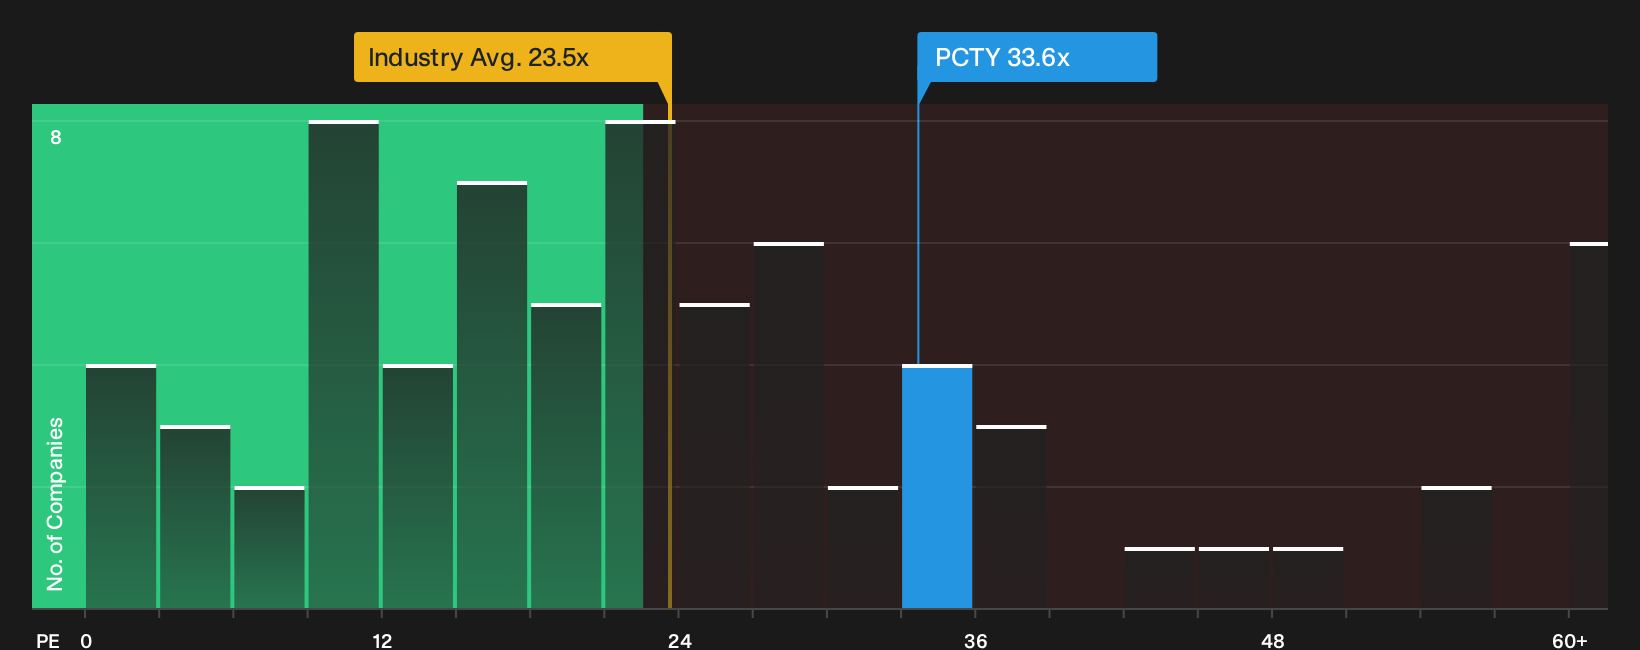
The story shifts once you look at Paylocity Holding through its P/E ratio. The shares trade at 33.6x earnings, compared with 21.5x for peers and a fair ratio estimate of 21.8x, which points to valuation risk if growth or AI uptake underwhelm. Is the premium really justified?
For investors weighing that question against the earnings-based view, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of AI optimism and valuation anxiety feels familiar, do not wait for consensus to form. Instead, dig into the data yourself and pressure test your own thesis using our breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Paylocity Holding?
Do not stop your research with Paylocity Holding. Broader opportunity often sits in places the crowd has not checked yet, and the screener can surface those ideas fast.
- Target resilient balance sheets and steady fundamentals by running the list of solid balance sheet and fundamentals (24 results) that filters for financial strength upfront.
- Hunt for mispriced quality by scanning the 33 high quality undervalued stocks that highlights companies where fundamentals and current prices look out of sync.
- Prioritize calm over drama with the 29 resilient stocks with low risk scores that focuses on resilience scores so you are not chasing every sharp move.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com