
Is MercadoLibre (MELI) Too Expensive After Its 30% Slide?
MercadoLibre has seen its share price slide over the past year, which puts a fresh spotlight on whether the current valuation still lines up with what the business earns. With new growth plans emerging and the stock coming off a weaker patch, the question is how much of its earnings story is already reflected in today's price.
- The share price has fallen 29.9% over the past year, which raises the issue of whether that decline now better reflects the earnings power of the business or still leaves a mismatch.
- The planned Netflix advertising collaboration and push into connected TV and AI driven ad formats may support expectations for future profitability, since they focus on tying brand campaigns more closely to marketplace and payments outcomes.
- The analysts covering MercadoLibre have run their own numbers. See what analysts think MercadoLibre's shares could be worth.
The stock's next move may depend on whether MercadoLibre's current earnings, and what investors expect those to look like over time, are enough to justify today's share price.
If you want to pressure test MercadoLibre against other opportunities built around clear criteria, a focused screener of 33 high quality undervalued stocks.
Is MercadoLibre Getting Expensive on Earnings?
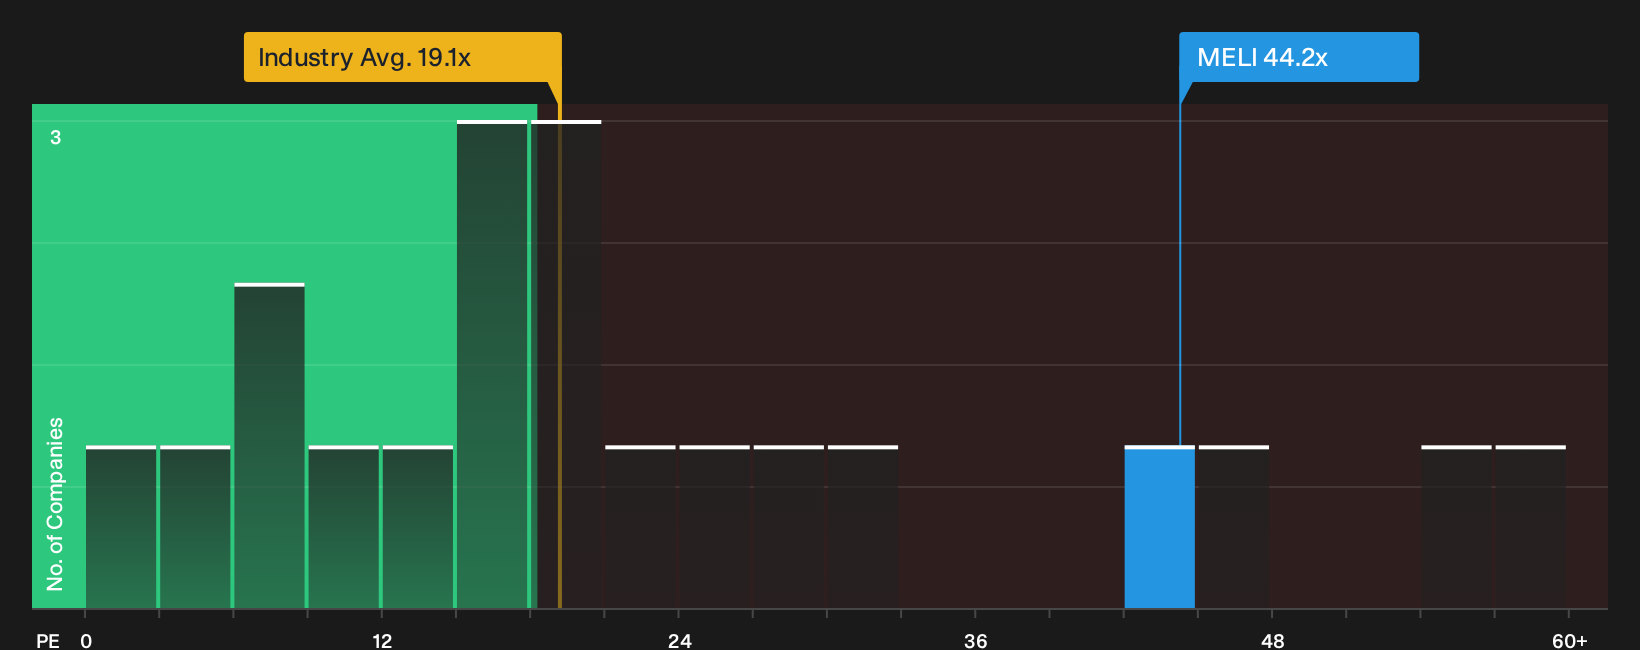
The P/E ratio suits MercadoLibre because investors often focus on earnings when weighing large platform businesses with multiple revenue streams. MercadoLibre trades on a P/E of 44.2x, which is more than double the Multiline Retail industry average of 19.1x and ahead of the peer group on roughly 19.2x. That kind of gap means buyers today are paying a much higher price for each dollar of current earnings than they would for a typical retailer or regional peer.
The Fair Ratio, which adjusts for MercadoLibre’s growth profile, profitability mix, size and risk, sits below the current P/E, so the shares screen as overvalued on this framework. Because the planned Netflix advertising partnership and AI driven ad push are already well flagged, the rich earnings multiple suggests a lot of optimism is already embedded in the quote. For anyone weighing an entry point, the question is whether MercadoLibre’s earnings trajectory can carry that premium over time or whether a lower multiple would be needed to line up more closely with the Fair Ratio. Explore the numbers behind MercadoLibre's P/E valuation.
The MercadoLibre Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the MercadoLibre valuation puzzle leaves off by spelling out which expectations for growth, margins and earnings would need to hold for the shares to be worth materially more or less than today. Each one treats MercadoLibre's implied fair value as a thesis about the business that you can watch over time, rather than a single static estimate, and they live on the stock's Community page.
One of the top community narratives on MercadoLibre: 50% undervalued
"Here’s the part that should make you smarter about valuation generally, not just about this one stock…"
Discover why this Narrative puts MercadoLibre at 50% undervalued.
MercadoLibre’s valuation is only half the story
Price and earnings paint one picture, but Simply Wall St checks have also raised specific concerns about MercadoLibre that investors often overlook when focusing only on multiples and growth narratives. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com