
Fiserv (FISV) Stock May Be Undervalued As Commerce Hub Expands
Fiserv shares closed at US$50.02 after a steep multiyear slide, and the question for anyone looking at the stock today is whether that price still lines up with what the business earns. Recent product launches and partnerships have kept the company in the headlines, but the key issue is how much of that is already captured in the valuation built on its earnings power.
- Fiserv has fallen 58.2% over the past 3 years, which puts the focus squarely on whether its current earnings justify that reset in market expectations.
- New efforts such as the Commerce Hub platform, expanded work with partners like Klarna, and a push into AI supported payments and digital assets can influence how durable and scalable the firm's earnings stream looks over time.
- There is a second opinion on Fiserv worth weighing. See what analysts think Fiserv's shares could be worth.
The issue now is whether today's Fiserv share price is appropriately reflecting what its earnings suggest the business is worth.
If you are weighing Fiserv against other earnings focused payment and fintech opportunities, it helps to compare it with a wider set of 41 profitable AI stocks that aren't just burning cash.
Is Fiserv Still Cheap on Earnings?
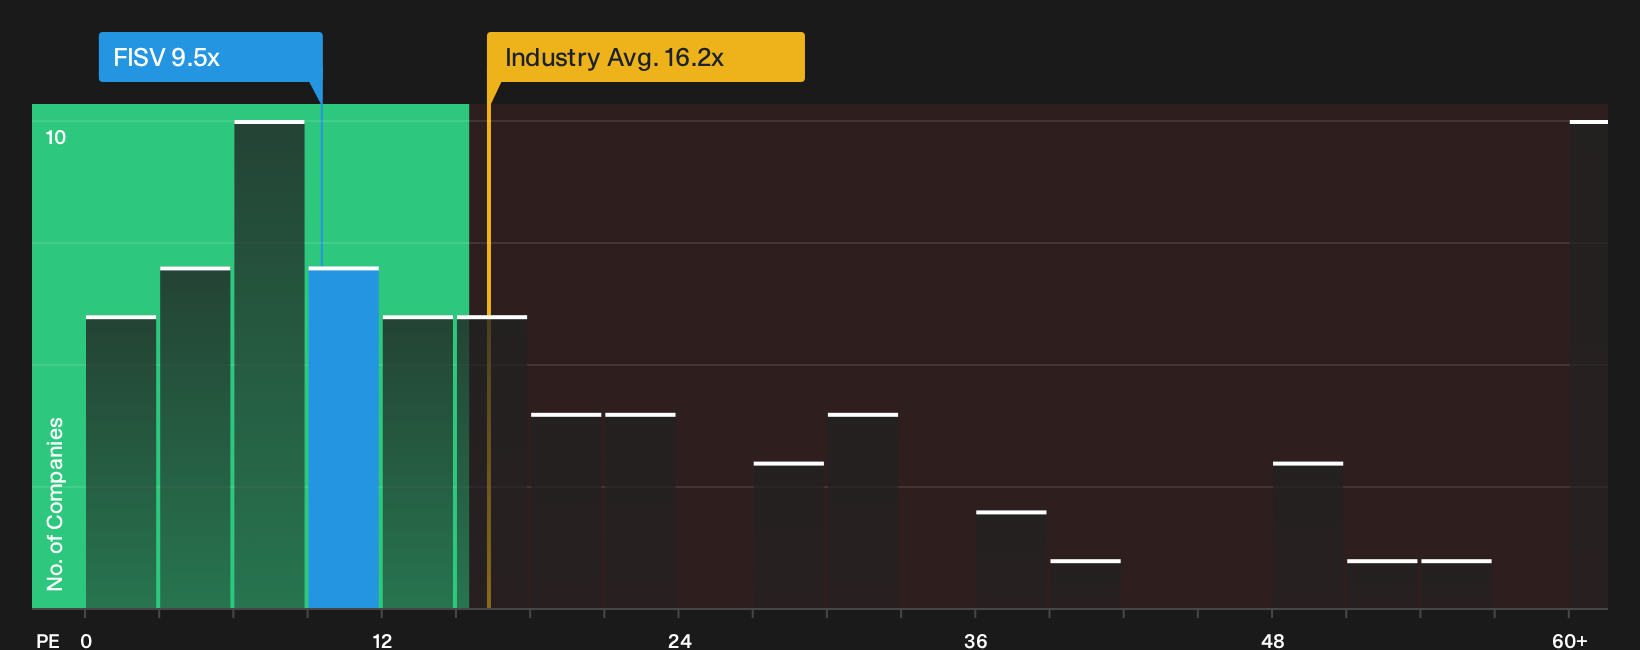
The P/E ratio is a useful lens for Fiserv because the business generates positive earnings and is widely covered by analysts. On this measure, Fiserv trades on a P/E of 9.5x, which is far below the Diversified Financial industry average of 16.2x and well under the 52.5x peer group level reported here. Based on the fair multiple the model would expect for a company with Fiserv's profitability profile and risk mix, the current P/E sits below that reference point. This indicates that the shares appear undervalued on an earnings basis.
Because Fiserv has been rolling out products like Commerce Hub and expanding partnerships around AI and digital assets, such as its work with Fireblocks on stablecoin based transfers, this discount suggests the market is not assigning the same valuation to those earnings streams as it is to many peers. If you are comparing payment and fintech stocks on earnings power, the gap between Fiserv's current P/E and the fair ratio implied by this model is worth a closer look. Explore the numbers behind Fiserv's P/E valuation.
The Fiserv Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Fiserv pick up where the P/E puzzle leaves off and outline which expectations on growth, profitability and earnings would need to occur for the share price to look meaningfully higher or lower than it does today. Each scenario links its figures to a clear view of how Fiserv's revenue trajectory, margin profile and risk picture might change, which you can revisit as new information emerges.
Community views on Fiserv are split between those who see a reset opportunity and those who think the market already reflects the risks.
Bull case: 58% undervalued
"But underneath the surface, we believe the new management team is taking the right steps to transform itself into one of the highest-quality financial technology franchises in the world..."
Discover why this Narrative puts Fiserv at 58% undervalued.
Bear case: roughly fairly valued
"The One Fiserv transformation is consuming cash at an accelerating rate ($95M in Q1 transformation payments alone) with no demonstrated financial results yet..."
Explore why this Narrative puts Fiserv at roughly fairly valued.
Fiserv’s valuation is only half the story
Price and earnings checks paint one picture for Fiserv, but the research also flags specific risk signals that could matter just as much to your decision. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com