
Caught Out By Whirlpool Of India’s Slide? What The Bears Saw
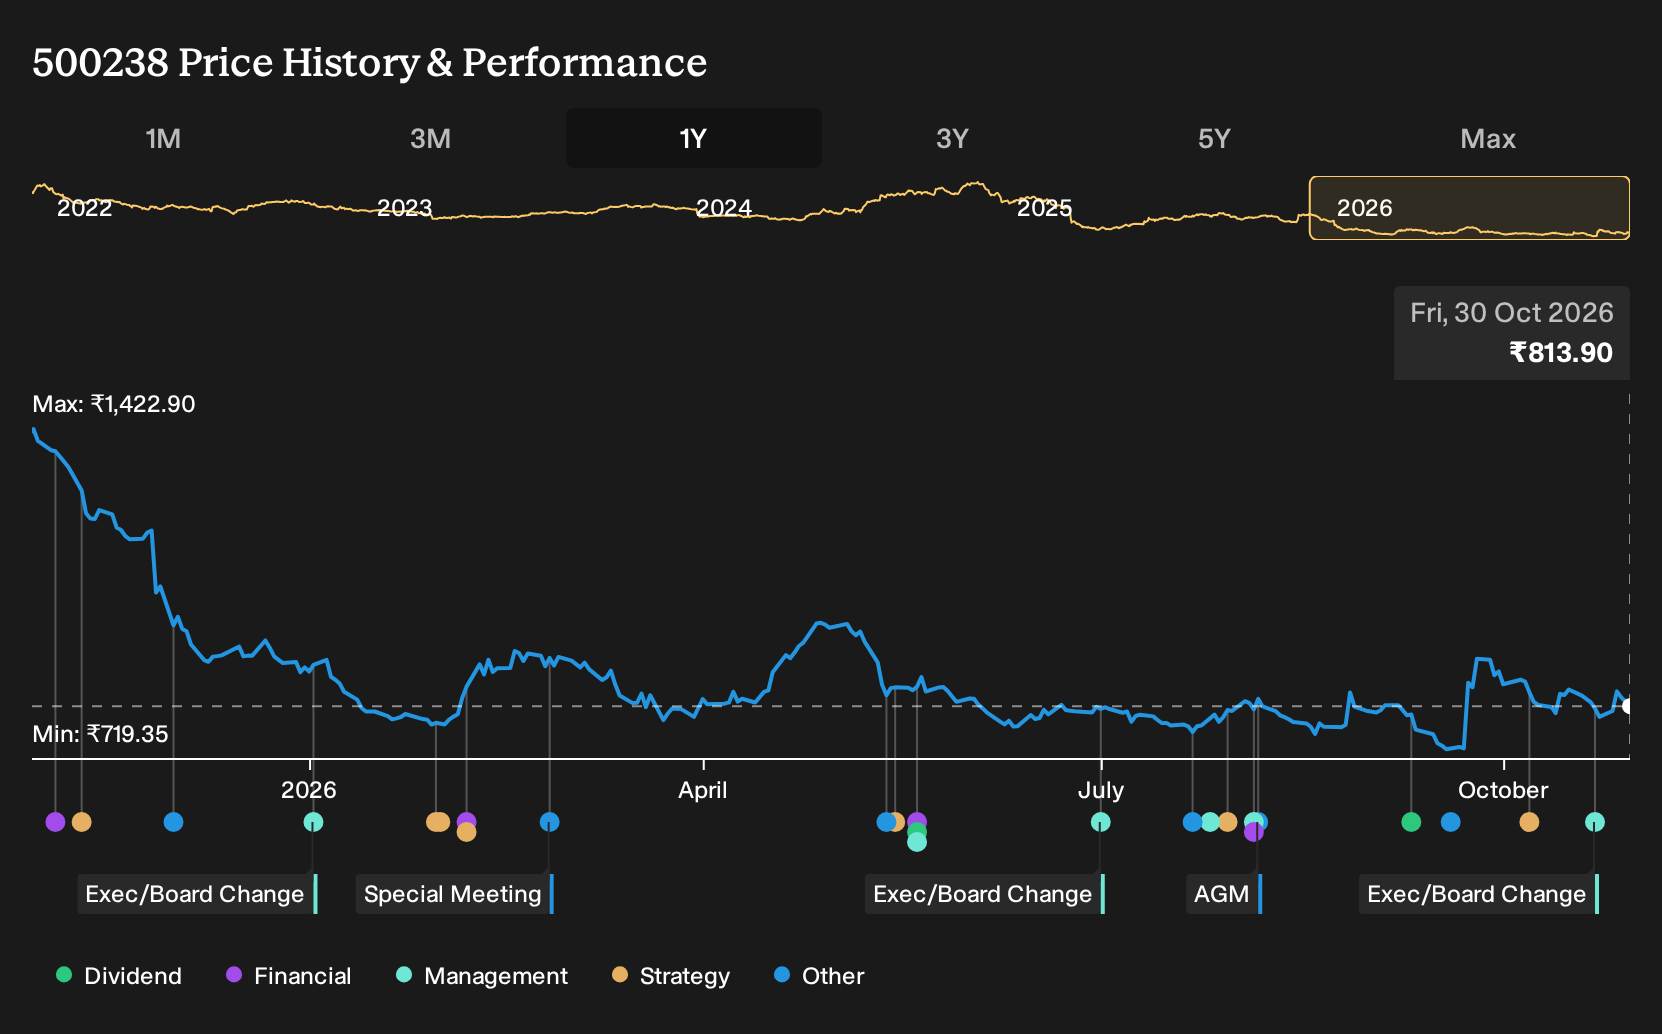
If Whirlpool of India looked like a clear way to ride urban migration and smart-home adoption in late 2025, the past year told a different story. Holding Whirlpool of India over the past year would have meant a 41.4% loss, including dividends. If you had bought on the strength of expected margin expansion, premium products and market share gains, what did that original thesis miss about execution, costs and competition that were already on record?
The easy part of this move is behind Whirlpool of India. Zero in on 200 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Whirlpool of India
The shares cost ₹1,423 at the start of the period, and the debate around Whirlpool of India hinged on whether urban migration and smarter homes could outweigh rising digital competition and regulation.
The bullish narrative pointed to a Fair Value of ₹2,100, a rough guide to what the stock might be worth if its optimistic case played out, built on an assumption that revenue could rise 15.2% a year and profit margins might reach 9.1% by 2028.
The bearish camp argued for a Fair Value of ₹1,100, implying downside if things broke the other way, and focused on the risk that global e-commerce pressure and tighter environmental rules could constrain margins even if revenue grew 10.1% annually and margins only reached 5.7%.
What The Results Changed For Whirlpool of India
Q1 2027 results gave Whirlpool of India bulls and bears something concrete to test. Revenue was ₹27,267.5m versus ₹24,323.2m a year earlier, which supported the demand story. Net income moved from ₹1,457.3m to ₹1,028.8m and net margin slipped from 6.0% to 3.8%, so the profitability leg of the optimistic case stayed unproven. Overall, the evidence cut both ways.
The key assumption here was margin expansion. When you assess another stock built on an efficiency story, track whether net margin is actually widening in reported numbers rather than relying on top-line growth alone.
What Whirlpool of India’s Drop Leaves You Paying For Today
Whirlpool of India now trades at ₹814, with this Narrative’s Fair Value sitting above that level. The current argument leans on premium refrigerators, washers and air conditioners, plus the Elica kitchen range, doing more of the heavy lifting in the revenue mix.
Record sales, cash discipline and a productivity program frame the question. For the fall to look like an opportunity rather than a warning, a buyer today has to believe premium led growth in underpenetrated categories can outpace ongoing regulatory, crude linked and currency cost pressure.
"The narrative that Whirlpool of India is undervalued implies the current share price does not fully reflect the company’s record revenue, premium product investments, negative net working capital profile and higher-margin contribution from Elica."
One Narrative disagrees with today's price. → See where this Narrative says Whirlpool of India should trade
Go Straight To The Source
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 30% below our estimate - ties AI workloads, subscriptions and usage-based services into one expanding cloud platform.
- Company 2 - 35% below our estimate - pushes digital retail upgrades and new store formats to convert traffic into higher-margin sales.
- Company 3 - 39% below our estimate - shifts from underwear focus toward faster growing sports apparel aimed at everyday training.
That is three of the list. See all 199 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com