
MasTec (MTZ) Stock May Trade At A Discount On Raised Guidance
MasTec has delivered a huge 260.7% share price gain over the past three years, yet recent weakness and fresh earnings headlines put the focus squarely on one issue: whether that kind of run still lines up with what the business is actually earning.
- A move of 260.7% over three years has turned MasTec into a very different proposition for anyone asking if the current tag can still be explained by its profit power.
- Record revenue, a historic order backlog and higher earnings expectations can support the case that future income may better match the price investors are being asked to pay today.
- There is a second opinion on MasTec worth weighing. See what analysts think MasTec's shares could be worth.
The issue now is whether MasTec's current share price is adequately supported by its earnings when judged against that Fair Ratio benchmark.
If you are weighing MasTec's 260.7% three year gain against what its earnings currently support, a targeted stock screen built around clear fundamentals can give you a useful comparison set through the 33 high quality undervalued stocks
Is MasTec Still Cheap on Earnings?
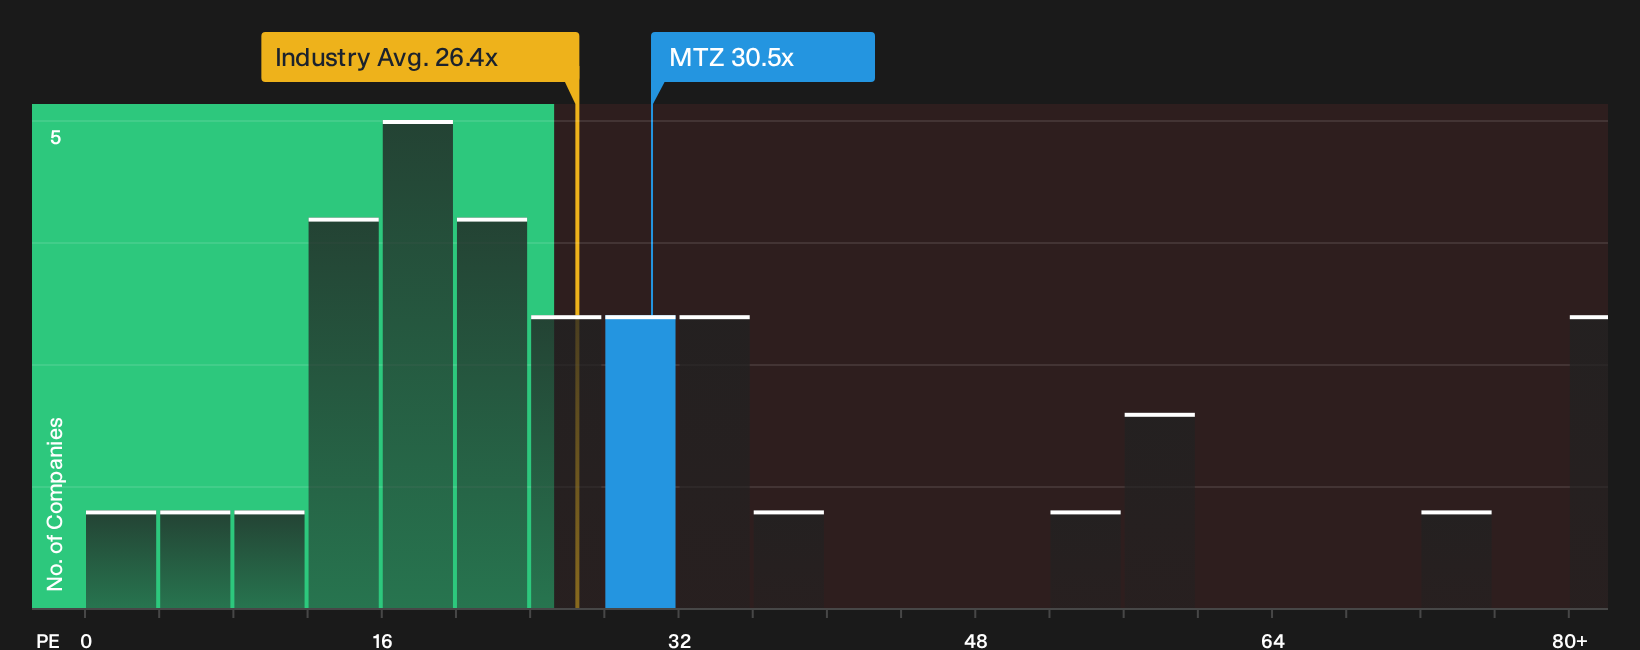
P/E suits MasTec because earnings remain a central yardstick for how investors value contractors in the Construction industry. The stock currently trades on a P/E of 30.5x, compared with roughly 26.4x for the wider Construction group and about 18.6x for close peers, so buyers today are paying a higher price for each dollar of profit than the typical competitor.
Because the recent guidance upgrades for 2026 earnings and the heavy order backlog feed into its earnings outlook, the Fair Ratio model that blends MasTec specific factors points to a higher multiple than the current one, which screens as undervalued on this framework. Despite record Q3 2026 revenue and a strong earnings beat lifting expectations, the P/E still sits below what that tailored yardstick suggests would fully reflect the business profile. Explore the numbers behind MasTec's P/E valuation.
The MasTec Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for MasTec pick up where the valuation puzzle leaves off. They spell out which assumptions about MasTec's future growth, margins and earnings would need to hold for the current P/E and Fair Ratio outputs to point higher or lower than today's price. They also turn a single model figure into a set of future checkpoints you can follow on the Community page to see whether that story is actually playing out.
One of the top community narratives on MasTec: 48% undervalued
"The main thing that has to go right is that MasTec converts its large Power Delivery, Clean Energy & Infrastructure, and Pipeline backlogs into projects at or above the EBITDA margin ranges management has outlined, while managing Communications volatility..."
Discover why this Narrative puts MasTec at 48% undervalued.
MasTec’s price is only one piece of your decision
Even with MasTec’s valuation story mapped out, the research flags separate risk checks that deserve space in your thinking. The details of those potential pressure points are for you to review next. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com