
Is Loews (L) Fairly Valued As Its Mixed Business Keeps P/E Above Insurance Peers?
Loews share performance and business mix
Loews (L) has delivered a 12.2% total return over the past year, with the share price at $111.32 as of the latest close in early November 2026.
Shorter term, the stock is roughly flat over the past week and up about 5% over the past month, while total return over the past 3 months has declined about 4%.
Over longer horizons, Loews shows sizeable compounded results, with total returns over the past 3 and 5 years that are both very large relative to the starting base.
The group sits on a market value of about $22.8b and reported revenue of $18.7b, with net income of $1.7b in the most recent full year disclosed in the data provided.
Loews operates as a diversified holding company with meaningful exposure to commercial property and casualty insurance alongside energy infrastructure, hotels and plastics manufacturing.
- CNA Financial generated $15.2b in revenue.
- Boardwalk Pipelines contributed $2.4b.
- Loews Hotels & Co added $976m.
- Segment adjustments totaled $195m.
This mix gives Loews a blend of insurance underwriting, fee-based pipeline operations, cyclical lodging activity and industrial plastics that can respond differently to shifts in pricing, demand and claims activity.
Investors tracking the value score, which sits at 0 in the data provided, may read that as a prompt to look more closely at how the current share price lines up with earnings power and asset exposure.
Loews has paired a strong long-term total shareholder return with more mixed recent share price moves. This suggests investors are reassessing how much they are willing to pay for its blend of insurance, pipelines, hotels and plastics at the current US$111.32 level.
Scan beyond Loews and line up other diversified, quality-focused businesses using our curated 29 resilient stocks with low risk scores as a starting universe for your watchlist.
Loews is only a touch below one intrinsic value estimate at about a 2% premium to book. Is the recent share price reset generous or tight compared with that range of fair value views?
Preferred P/E multiple of 13.5x: Is it justified for Loews?
Loews trades on a P/E of 13.5x at a share price of $111.32, which places the stock above both the US Insurance sector and its direct peer average on this metric.
The P/E ratio links the current share price to earnings per share and often reflects what investors are willing to pay for each dollar of profit. For a diversified group like Loews, which blends commercial insurance with pipelines, hotels and plastics, that single figure can capture how the market weighs the stability of insurance earnings against more cyclical or capital intensive activities.
With Loews flagged as "good value" versus the broader US market P/E of 18x, the higher multiple relative to insurance peers points to investors assigning a richer tag compared with pure-play insurers. The combination of 25.1% earnings growth over the past year, higher current net profit margin of 9% versus 7.5% a year earlier, and an 8.9% return on equity that is still described as low helps explain why the current valuation can be read as full rather than cheap.
Against the US Insurance industry average P/E of 11.5x and a peer group at 11.8x, Loews trades at a clear premium on earnings even though its P/E remains below the overall US market. That spread suggests the market is pricing in relatively stronger profitability or business mix benefits than the typical insurer while stopping short of granting the stock a market wide rating.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 13.5x (OVERVALUED).
Still, concentrated exposure to commercial insurance and energy infrastructure leaves Loews sensitive to large loss events and to regulatory or contract changes that could challenge its current earnings power.
Find out about the key risks to this Loews narrative.
Another view on Loews using cash flows
The earnings multiple paints Loews as expensive versus insurers, yet the SWS DCF model points to something softer. At $111.32 the shares sit only modestly above an estimated future cash flow value of $109.41, which implies a small premium instead of a stretched valuation. Could that narrow gap close in either direction as new information lands?
Look into how the SWS DCF model arrives at its fair value.
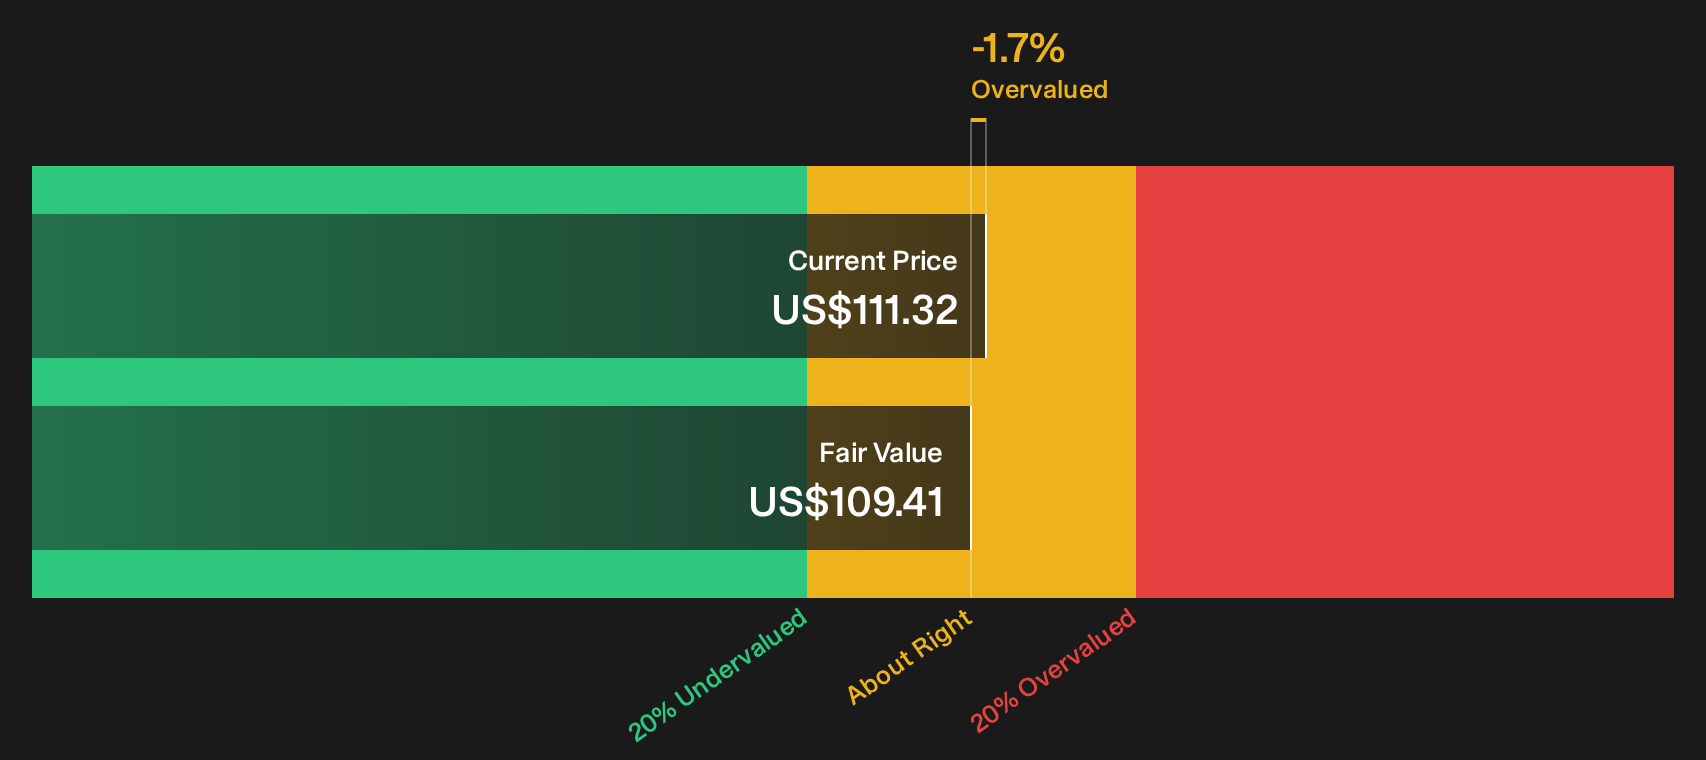
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Loews for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Loews so far. If you want to move quickly and make up your own mind, start by weighing its rewards through the 2 key rewards
Looking for more investment ideas beyond Loews?
If Loews has you rethinking your portfolio, do not stop here. Fresh ideas often come from comparing it with other high quality, differently positioned businesses.
- Target stability by scanning a hand picked list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with stronger financial footing.
- Hunt for potential mispricing through our curated 33 high quality undervalued stocks that may highlight opportunities the broader market has not fully priced in yet.
- Build out your watchlist with differentiated prospects using the carefully filtered 19 high quality undiscovered gems so you are not always chasing the same crowded tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com