
Did Earnings Beat Just Shift Incyte's (INCY) Investment Narrative?
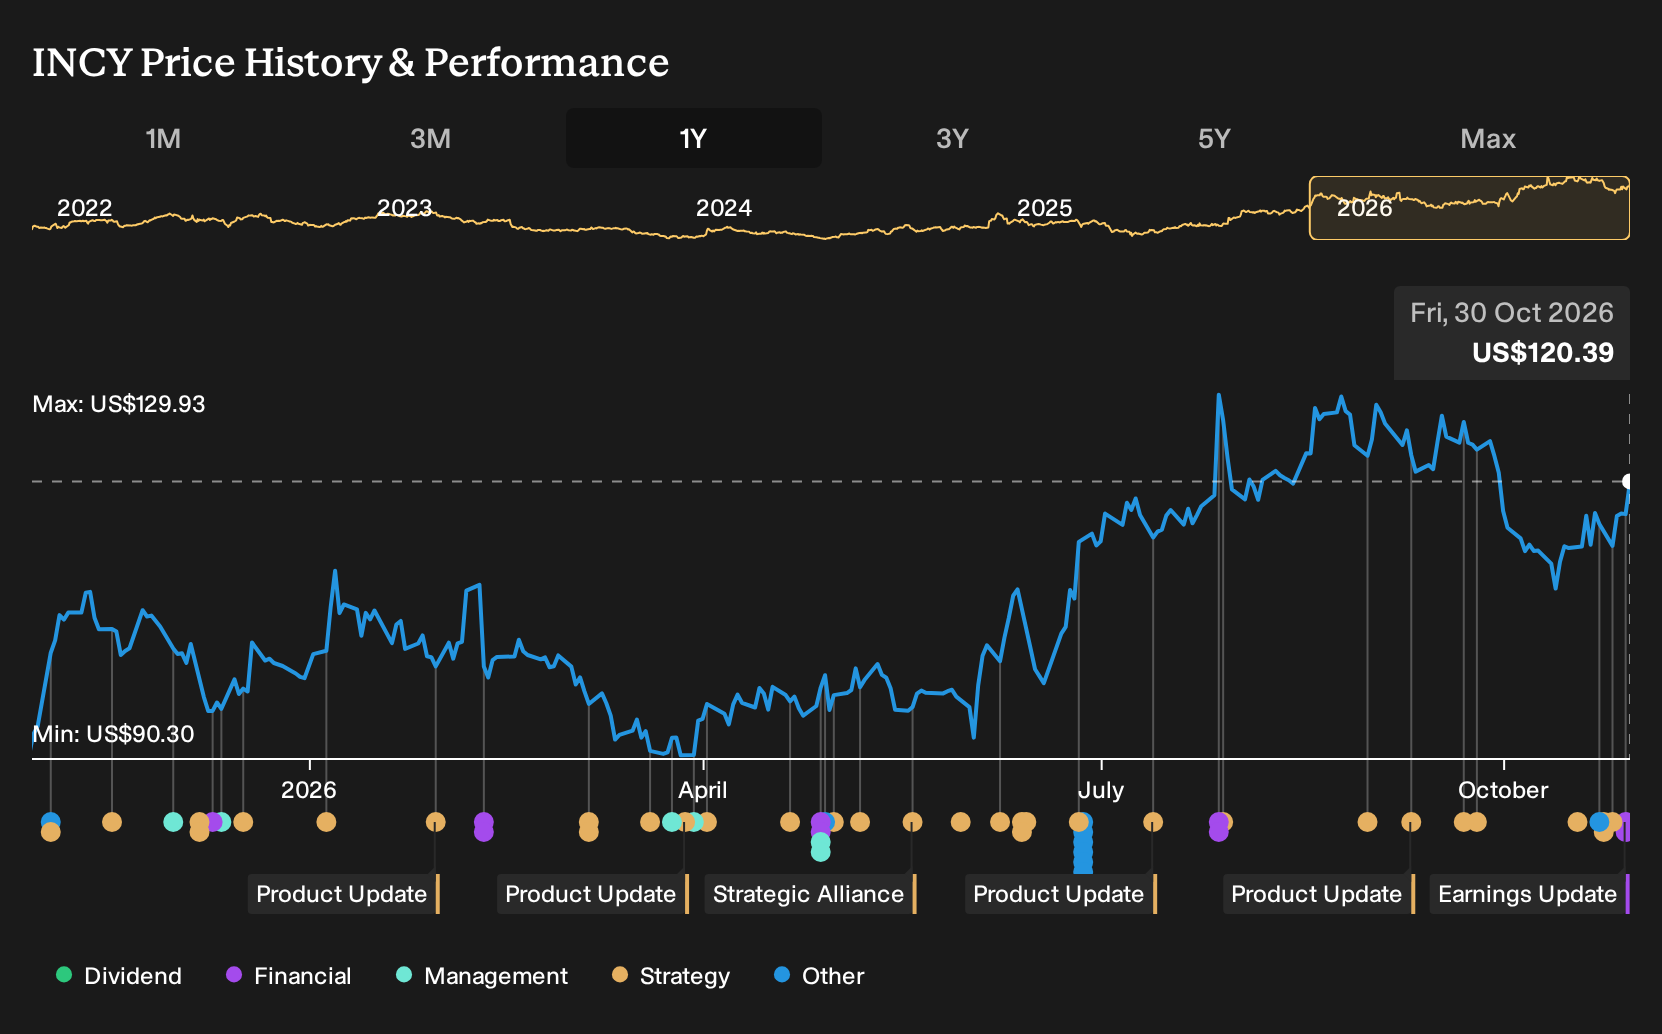
- Incyte reported Q3 2026 revenue of US$1,557.2m and a quarterly net loss of US$784.8m, while still raising full year 2026 sales guidance to a range of US$5,210m to US$5,300m.
- The company paired higher expenses and in-process R&D charges with fresh gastrointestinal oncology data and new collaborations that expand its pipeline beyond Jakafi.
- We will now see how Incyte's raised 2026 sales guidance reshapes the broader investment narrative around its multi-franchise ambitions.
See how Incyte’s R&D-heavy quarter compares with other research-led opportunities by reviewing our curated list of 19 high quality undiscovered gems across the market.
Incyte Investment Narrative Recap
To stay invested in Incyte, you need to believe the shift from a Jakafi centric model to a broader mix across dermatology, hematology and gastrointestinal oncology can support the business while R&D stays high. Q3 2026 showed that trade off clearly. Revenue reached US$1,557.2m, yet the quarter swung to a net loss of US$784.8m as upfront and in process R&D charges hit earnings.
In the short term, the key swing factor is whether execution on newer products and franchises is strong enough to support the raised 2026 sales outlook of US$5,210m to US$5,300m despite compressed margins. The biggest risk right now is that heavy R&D and SG&A spending, including costs tied to acquisitions, keeps profitability under pressure without a matching uplift from late stage assets.
The most relevant recent update for this quarter is the raised full year 2026 net sales guidance. Management now expects US$5,210m to US$5,300m in total sales compared with the prior range of US$5,130m to US$5,260m. That change links directly to the operating story investors are reacting to in the latest earnings numbers.
That higher range, set against a Q3 net loss, underlines the current trade in Incyte between top line momentum and thinner margins. For catalysts, it puts more focus on how quickly non Jakafi products like Opzelura and the emerging GI oncology portfolio can translate R&D and business development spending into durable revenue, before loss of exclusivity pressure intensifies and while earnings quality is clouded by one off charges.
What The Analyst Forecasts Mean For Incyte
Analysts are effectively indicating that Incyte needs to do more with roughly the same revenue base. They are modeling relatively flat sales over the next three years, with profit margins moving from 27.7% today to 19.9% by 2029. That combination points to a story where product mix, R&D intensity, and operating costs matter as much as top line guidance.
On earnings, the consensus view is that Incyte generates about US$1.6b today and could be at US$1.2b by 2029. That is a US$0.4b earnings decline over the period, shaped by heavier investment and lower modeled profitability. For investors tracking the Q3 2026 net loss and raised sales outlook side by side, these numbers frame a scenario where higher spending and margin compression remain central questions rather than short term anomalies.
Valuation expectations build directly on those forecasts. To align with the analyst targets, you would need to accept a 2029 profile of roughly US$5.8b in revenue and US$1.2b in earnings, alongside a P/E of 30.9x compared with about 14.7x today and 17.6x for the wider US biotech peer group. This represents a materially richer multiple for a business that consensus expects to earn less than it does now. That is where the debate about Incyte’s multi franchise potential versus near term profitability really starts.
Incyte's narrative projects US$5.8b revenue and US$1.2b earnings by 2029. This implies flat yearly revenue growth and an earnings decrease of about US$0.4b from current earnings of roughly US$1.6b.
Uncover why Incyte's fair value indicates a 7% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One alternative view focuses on earnings pressure rather than pipeline promise. The most bearish analysts were already assuming revenue would trend down about 2.4% a year and earnings would settle near US$1.2b by 2029 before this Incyte update. You can use that more cautious stance as a reference point to test how today’s raised sales guidance and GI oncology data might shift expectations from here.
Explore 4 other Incyte fair value estimates, including one that suggests the potential for as much as 20% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and research.
- A great starting point for your Incyte research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Incyte. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which allows you to evaluate Incyte's overall financial health at a glance.
Looking For More Investment Ideas Beyond Incyte?
If the Incyte story has you rethinking how you balance risk, quality, and income in your portfolio, it can help to scan a broader set of opportunities side by side using the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, review companies highlighted in our 33 high quality undervalued stocks and compare how their valuations stack up against current fundamentals.
- If capital preservation and balance sheet resilience are top of mind, focus on businesses identified in our 29 resilient stocks with low risk scores that score well on financial strength and risk metrics.
- For those hunting for stronger income streams, check out stocks featured in our 5 dividend fortresses that combine higher yields with disciplined payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com