
New York Times (NYT), What Is Behind The Fresh Attention?
Recent share performance and business snapshot
New York Times (NYT) has drawn fresh attention after recent trading, with the stock closing at US$70.17 and showing mixed short term returns alongside stronger figures over the past year and multi year periods.
Over the past month, the share price return was 11.9%, while the past 3 months showed a decline of 7.2%. Year to date, the total return sits near 0.5%, compared with 24.5% over the past year and roughly 75% across 3 years.
The media group reports annual revenue of US$2.95b and net income of US$392.83m, supported by a broad portfolio that includes The New York Times, The Athletic, Cooking, Games, Audio, Wirecutter, and advertising and licensing activities.
For New York Times, that mix of an 11.9% 1 month share price return, a recent 3 month pullback and a 1 year total shareholder return of 24.5% points to longer term momentum that has paused rather than reversed.
The recent upswing in the share price toward US$70.17 suggests investors are reassessing growth prospects and risk around its subscription driven model, and using the shorter term weakness as a chance to reset expectations after a period of strong multi year total shareholder returns.
Seize this pause in New York Times momentum to compare it with hand picked media and content stocks on the 19 high quality undiscovered gems.New York Times now trades around US$70 with a long record of subscription driven revenue behind it. The real issue is whether that resilience is already fully baked into the price.
Most Popular Narrative: 9% Undervalued
On the most followed view, New York Times carries a fair value of about $76.89 against the recent $70.17 close. This puts the spotlight on whether its subscription and content engine can keep supporting that gap as cash flows evolve under a 9.18% discount rate.
Robust growth in digital-only subscriptions at The New York Times, with year-over-year revenue increases in the mid-teens, rising ARPU and a subscriber base already above 13 million toward a 15 million 2027 goal, supports the view that the multi-product bundle can keep lifting recurring revenue and operating margins.
See why 13 investors see New York Times as 9% undervalued.
Result: Fair Value of $76.89 (UNDERVALUED)
Still, the New York Times narrative could be knocked off course if referral traffic from large tech platforms keeps shrinking, or if heavy video and technology spending pushes costs ahead of revenue for too long.
Find out about the key risks to this New York Times narrative.
Another View on New York Times Valuation
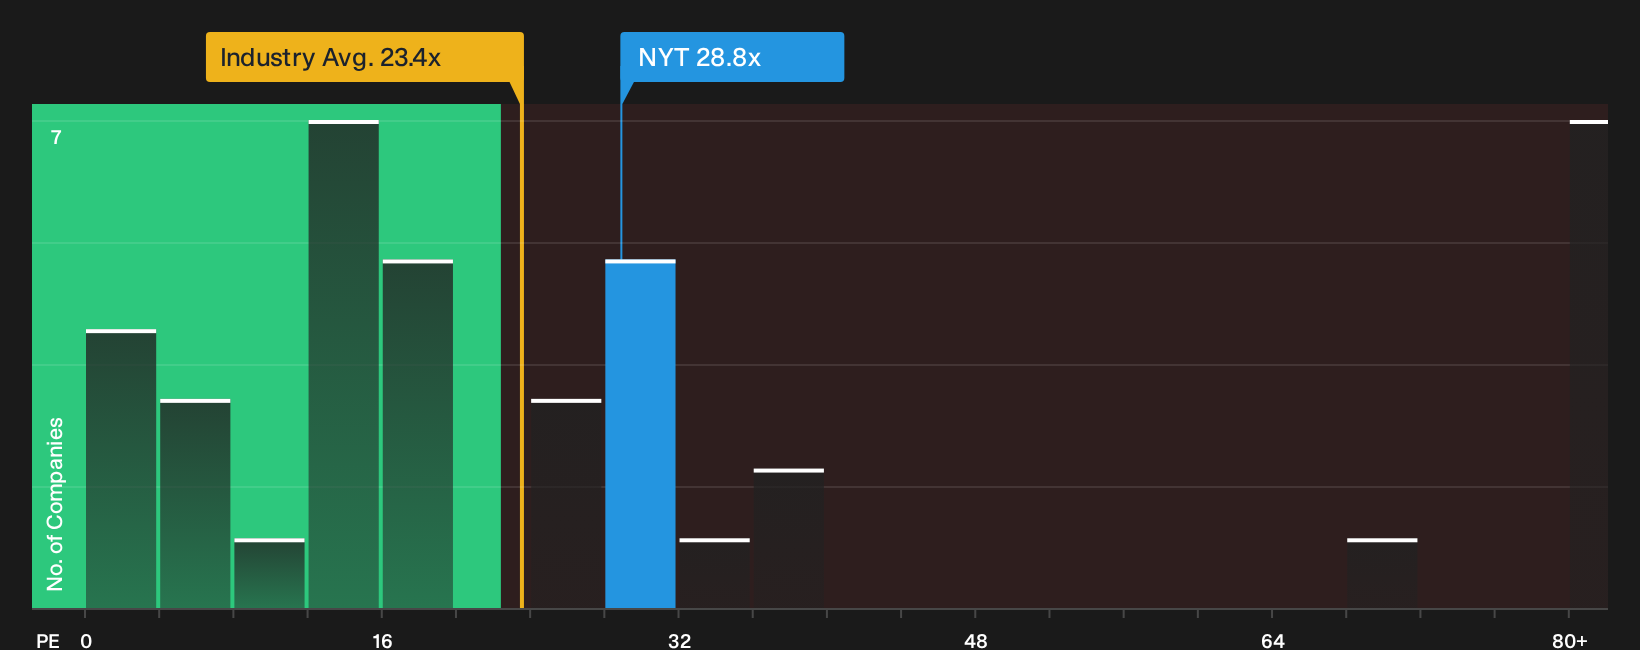
While the SWS DCF model tags New York Times as around 8.6% undervalued at $70.17 versus an estimated $76.79 future cash flow value, the picture is less forgiving when looking at earnings multiples. The stock trades on a 28.8x P/E, above the US Media industry at 23.4x and a fair ratio of 18.3x. That gap points to less margin for error around the growth story, so which signal do you put more weight on?
For a closer look at why the current P/E sits well above both peers and the fair ratio, and what that might mean for future re rating risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mostly optimistic tone around New York Times match your own reaction to the numbers, or does it raise new questions you want answered? Act quickly, review the full breakdown of rewards and risks, and pressure test your view against the 3 key rewards.
Looking for more New York Times sized investment ideas?
If New York Times has you rethinking your watchlist, do not stop here. Use this momentum to line up the next set of opportunities.
- Target potential mispricing by scanning for quality companies trading below intrinsic estimates through the 33 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with robust finances and clean balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Lock in potential income streams by reviewing reliable payers and higher yield opportunities through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com