
How Investors Are Reacting To Medtronic (MDT) Strong Ablation Registry Results
- Medtronic reported positive real world registry data for its Affera Mapping and Ablation System and PulseSelect Pulsed Field Ablation System, with large global cohorts of atrial fibrillation and ventricular tachycardia patients showing high acute success and low major complication rates.
- The Sphere-9 catheter’s combined high definition mapping, pulsed field, and radiofrequency ablation profile, along with real world data in hard to treat ventricular tachycardia patients, highlights how Medtronic is trying to build a differentiated cardiac ablation platform within electrophysiology.
- We will now look at how Medtronic's investment narrative could be influenced by these real world cardiac ablation outcomes.
Compare Medtronic's focus on cardiac technology with a curated group of peers by scanning 34 healthcare AI stocks that link medical devices, data and procedure outcomes in different ways.
Medtronic Investment Narrative Recap
To be comfortable as a Medtronic shareholder, you need to buy into a story where higher growth platforms in cardiac ablation, cardiac rhythm management and connected surgery steadily shift the mix toward therapies with stronger long term demand. The recent registry data points to real world use of Affera, Sphere 9 and PulseSelect, which can support that cardiac ablation thesis, but does not change the near term picture on its own.
The biggest near term swing factor still looks like execution on portfolio reshaping and margin work, including the diabetes separation and cost programs. At the same time, the company needs to manage mix pressure from fast growing but lower margin franchises such as Cardiac Ablation Solutions. Key risks remain potential underperformance in larger cardiovascular areas such as Structural Heart and any earnings drag from litigation costs tied to legacy Covidien products.
Among the recent announcements, the most relevant for this story is the positive real world data for Medtronic cardiac ablation systems in atrial fibrillation and ventricular tachycardia. These therapies sit directly in one of the franchises analysts already see as important for supporting organic revenue growth over time, alongside renal denervation and pelvic health.
For you as an investor, the question is whether Medtronic can turn that clinical experience into sustained procedure volumes and attractive economics while still lifting margins. Strong registry outcomes can help defend share and support Cardiac Ablation Solutions as a growth catalyst, but mix effects, Structural Heart softness and potential litigation cash outflows still sit in the background as key execution and earnings risks.
Medtronic's narrative projects US$42.8b revenue and US$7.1b earnings by 2029. This is based on an assumed 4.4% yearly revenue growth rate and an anticipated US$1.9b increase in earnings from US$5.2b today.
Uncover why Medtronic's fair value indicates a 9% potential upside to its current price that could narrow quickly.
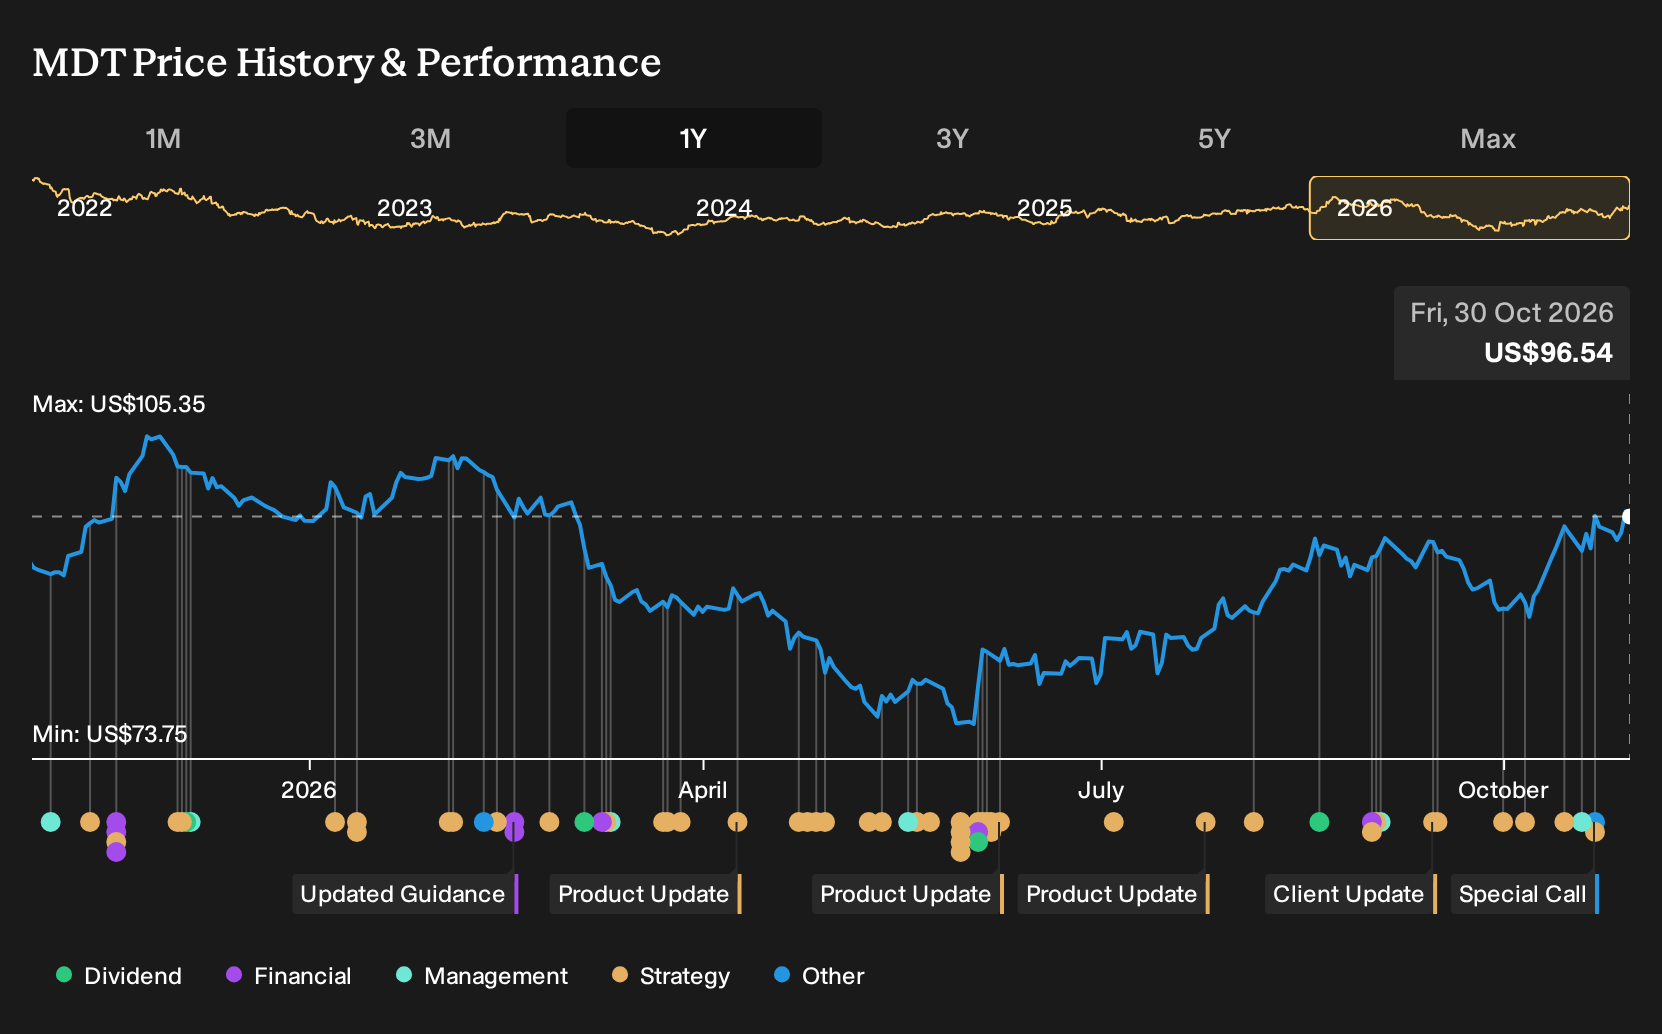
Exploring Other Perspectives
One alternate angle on Medtronic focuses on the risk that all these electrophysiology investments underwhelm financially. The lowest analysts were only penciling in roughly 1.7% yearly revenue growth and about US$6.4b in earnings by 2029 before this registry news. That is a much cooler narrative. These differences may help investors compare several viewpoints before considering how this new data might influence expectations.
Explore 8 other Medtronic fair value estimates, including one that suggests as much as 6% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Medtronic research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Medtronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Medtronic's overall financial health at a glance.
Looking For More Ideas Beyond Medtronic?
If you want to stress test your Medtronic view against alternatives, it can help to scan a broader field of companies with different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about resilient balance sheets and steady fundamentals, review a list of solid balance sheet and fundamentals (24 results) that may better fit a capital preservation mindset.
- If you are hunting for opportunities that screens flag as attractively priced relative to quality, scan a curated group of 33 high quality undervalued stocks that could complement a position in Medtronic.
- Income focused investors who want yield with support from underlying business strength can scan a focused set of 5 dividend fortresses that might align with a long term dividend strategy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com